

Trading
Explore a wide range of markets with competitive pricing, deep liquidity, and advanced trading tools.
Learn More 
Platform
Trade seamlessly with TMGM's powerful platform, built for speed, precision, and a superior trading experience.
Learn More Trading Platform
Academy
Learn the fundamentals of trading with beginner-friendly resources, including guides, webinars, and market insights.
Learn More News & Analysis
Get real-time market updates and expert analysis to stay ahead of trading opportunities
Learn More News & Analysis
About
Learn what sets TMGM apart — our global presence, regulatory strength, and commitment to innovation in trading.
Learn More Why Choose TMGM
Sponsorship
1.10: Euro inches back from 19-month low as Dollar softens
- 1.1000 is back in view for EUR/USD. The pair has recovered to that level after hitting a 19-month low below it.
- Despite stronger-than-expected ZEW sentiment, the Euro found no support and hit its low following US data.
- Wednesday brings the final Eurozone inflation figures alongside the Fed's meeting minutes.
EUR/USD is trading at 1.1000. That leaves it close to Monday's closing level after a decline to just above 1.0950, a 19-month low. The Euro looks set to end five consecutive sessions of losses, largely because the Dollar failed to sustain its own 19-month peak. The Pound is also ending a losing streak of the same length, with a larger recovery.
US retail sales exceeded forecasts when autos were excluded, driving the Dollar Index to its peak as EUR/USD reached its low. The pair then recovered as the Dollar surrendered those gains and extended its decline following a 0.4% fall in industrial production. At 3.75%-4.00%, the Fed's rate already exceeds the European Central Bank (ECB) deposit rate of 2.50% by 1.25-1.50 percentage points. Markets have fully priced in a Fed increase on December 9.
November's ZEW economic sentiment index reached 26.5, up from 18.5 and above the 19.1 forecast. Even so, the Euro subsequently registered its session low. Recent ECB remarks strongly signal a December rate increase, according to ING analysts. The ECB's December 17 decision follows the Fed's by eight days. Quarter-point increases from both would leave the rate differential unchanged, explaining why the prospect of an ECB hike has failed to support the Euro.
December 17 decision: data and speakers ahead
Wednesday's schedule starts with the final October Eurozone inflation figures at 10:00 GMT. The core rate is expected to remain at 2.5%. ECB President Lagarde then speaks at 14:25 GMT, with further appearances on Thursday at 13:30 GMT and Friday at 08:30 GMT. Friday also brings the first November consumer confidence reading at 15:00 GMT, with the forecast steady at -17.9. These releases and remarks all feed into the ECB's December 17 decision.
The US calendar features the Fed minutes at 19:00 GMT on Wednesday, coinciding with the day of the Eurozone releases. Initial jobless claims follow on Thursday at 13:30 GMT, with 196K expected against the previous 200K. The University of Michigan survey rounds off the schedule on Friday.
1.1250 area: 50-day EMA and November high
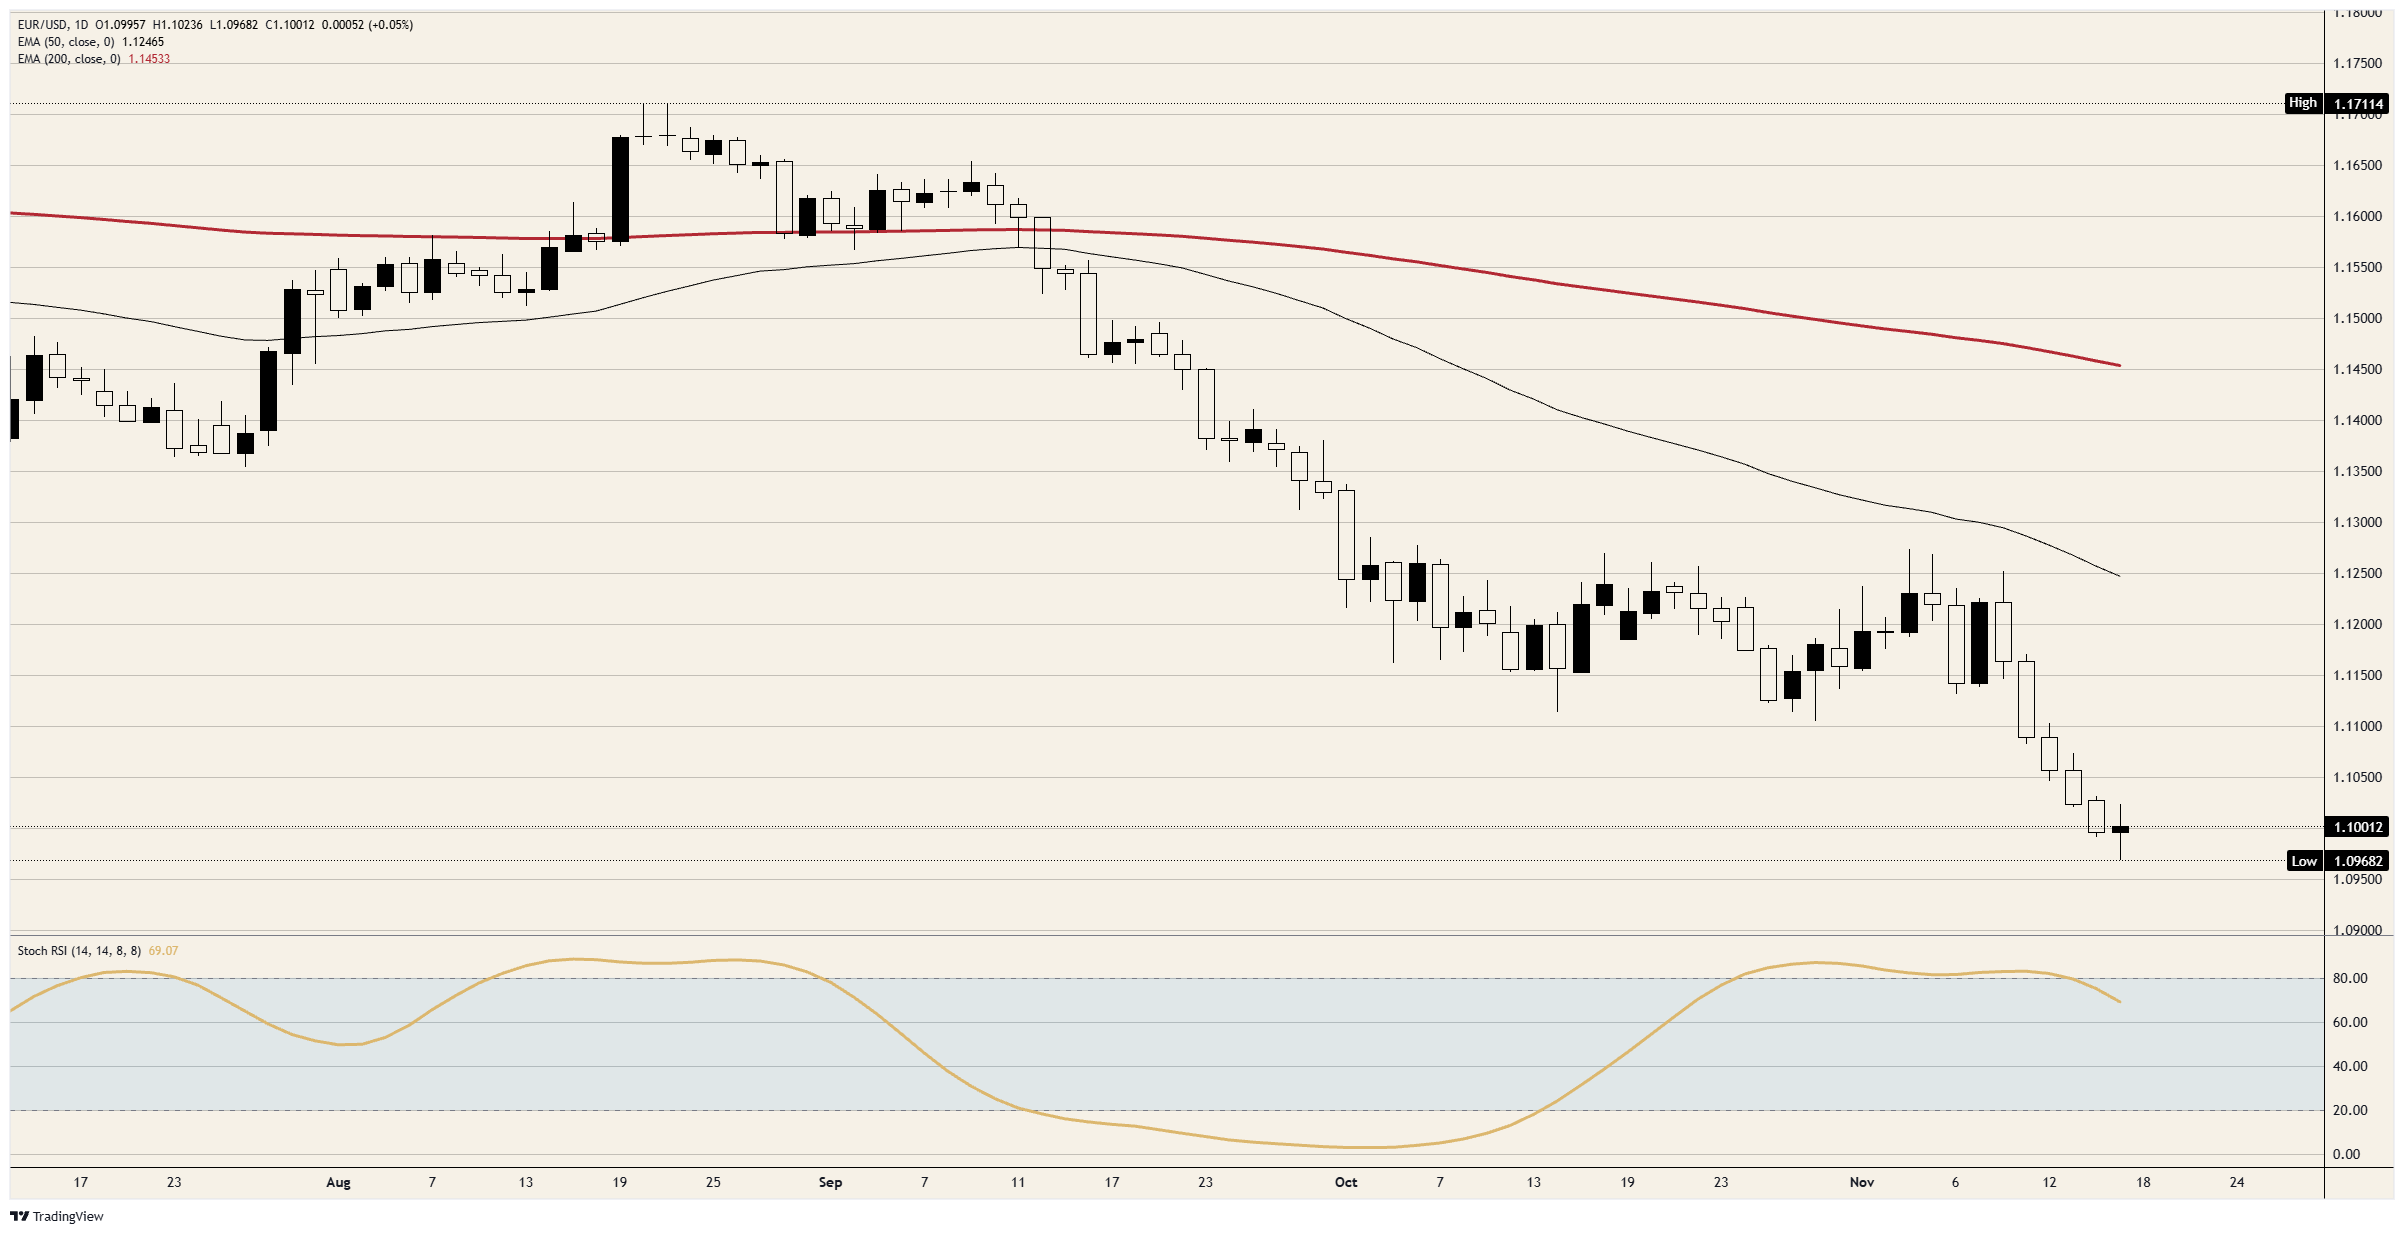
Tuesday's recovery has reversed very little of the Euro's five-session slide from its November 10 high near 1.1250. On the chart, the August peak just above 1.1700 marks the upper end, while the current session's low marks the lower end. The 50-day Exponential Moving Average (EMA) sits just below 1.1250; the 200-day EMA stands just above 1.1450.
EUR/USD: daily price chart
Euro: key questions answered
The 20 European Union countries within the Eurozone share the Euro as their currency. Only the US Dollar is traded more heavily worldwide. The Euro represented 31% of all foreign exchange transactions in 2022, with daily turnover averaging more than $2.2 trillion. An estimated 30% of all transactions involve EUR/USD, making it the world's most actively traded currency pair. Next come EUR/JPY at 4%, EUR/GBP at 3% and EUR/AUD at 2%.
Based in Frankfurt, Germany, the European Central Bank (ECB) serves as the Eurozone's reserve bank. Responsibility for setting interest rates and managing monetary policy rests with the ECB. Maintaining price stability is its central mandate, whether through containing inflation or supporting growth. Interest rate increases and cuts are its main policy instrument. Higher relative rates, or expectations of rate increases, generally support the Euro; the reverse also applies. Monetary policy is decided by the ECB Governing Council at eight meetings each year. The decision-makers comprise the heads of the Eurozone's national banks and six permanent members, among them ECB President Christine Lagarde.
The Harmonized Index of Consumer Prices (HICP), which measures Eurozone inflation, provides an important economic indicator for the Euro. An unexpectedly strong rise in inflation, particularly beyond the ECB's 2% target, requires the central bank to increase interest rates to bring price pressures back under control. When the region's interest rates are relatively high compared with those elsewhere, the Euro usually benefits. Such rates increase the region's appeal to global investors seeking a place to hold their funds.
By indicating the economy's condition, data releases can move the Euro. GDP, Manufacturing and Services PMIs, employment figures and consumer sentiment surveys can each influence the single currency's direction. Economic strength supports the Euro by attracting additional foreign investment. It may also prompt the ECB to raise interest rates, directly strengthening the currency. Weak economic readings, by contrast, are likely to weigh on the Euro. Particular attention goes to Germany, France, Italy and Spain, the euro area's four largest economies. Together they represent 75% of the Eurozone economy, making their data especially important.
The Trade Balance is another important release for the Euro. Over a specified period, it records the difference between a country's export earnings and its import spending. Strong overseas demand for a country's exports generates additional demand for its currency as foreign buyers seek to purchase those goods. That demand alone increases the currency's value. A positive net Trade Balance therefore supports a currency, while a negative balance has the opposite effect.
POPULAR ARTICLES
1Five-session slide ends for Pound on UK jobs data and softer Dollar21.10: Euro inches back from 19-month low as Dollar softens351% of Bitcoin supply underwater as sell-off intensifies4Dow Jones Industrial Average Falls on NSA Outage Before Nvidia Beats Expectations5US natural gas demand decline brings limited relief to Europe - Commerzbank6UOB: Chinese Yuan likely to extend gains against US Dollar72028 Outlook: Copper Set for Gradual Gains – Commerzbank8Below $1,800: Ethereum Price Forecast as ETH Drops Ahead of Nvidia's Earnings9Taiwan Dollar: TWD faces pressure from equity outflows – OCBC


Get Started!
Sign up and access the Global Markets in less than 3 minutes

Connect With Us









Contacts
Phone: +61 2 8036 8388
Fax: +61 2 8036 8388
Email: support@tmgm.com



The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved