

Trading
Explore a wide range of markets with competitive pricing, deep liquidity, and advanced trading tools.
Learn More 
Platform
Trade seamlessly with TMGM's powerful platform, built for speed, precision, and a superior trading experience.
Learn More Trading Platform
Academy
Learn the fundamentals of trading with beginner-friendly resources, including guides, webinars, and market insights.
Learn More News & Analysis
Get real-time market updates and expert analysis to stay ahead of trading opportunities
Learn More News & Analysis
About
Learn what sets TMGM apart — our global presence, regulatory strength, and commitment to innovation in trading.
Learn More Why Choose TMGM
Sponsorship
Federal Reserve poised to leave interest rates unchanged despite stubborn inflation
- October is widely expected to bring no change in US Federal Reserve interest rates.
- A December rate increase remains a strong probability in market pricing.
- US Dollar volatility could increase as Fed Chair Warsh addresses the press conference.
Wednesday brings the United States (US) Federal Reserve (Fed) announcement of its Interest Rate Decision, after another crucial policy meeting that could clarify the central bank’s monetary policy outlook for the final months of the year.
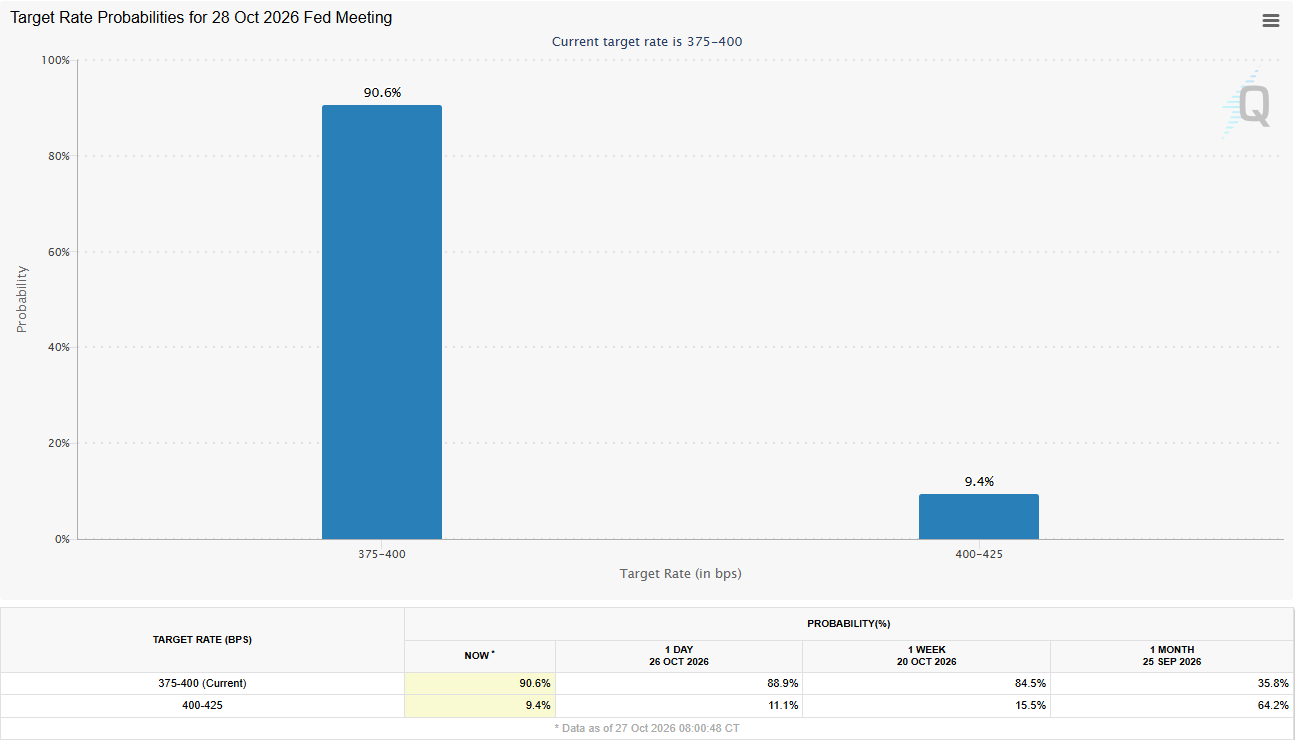
The broad market consensus is for the Federal Open Market Committee (FOMC) to maintain its policy rate at 3.75%-4% after September’s announced increase of 25 basis points (bps).
About a 9% probability of higher borrowing costs is indicated by the CME FedWatch Tool. An unchanged decision is therefore almost entirely priced in. Attention could instead centre on Fed Chair Kevin Warsh’s post-meeting press conference, where his remarks could shape interest rate expectations and the US Dollar’s (USD) valuation.
At an International Monetary Fund (IMF) event earlier this month, Warsh reaffirmed the commitment to price stability while saying he does not believe in “pre-judging meetings.” Investors responded by effectively ruling out an October rate increase. That was despite September’s US Consumer Price Index (CPI) exceeding expectations, as annual headline inflation accelerated from 3.4% to 3.7%.
With a rate change largely ruled out at the forthcoming meeting, Deutsche Bank economists expect the tone of the Fed’s communication to take centre stage. They say “the interest will therefore be in Chair Warsh’s press conference and how the Fed balances still-elevated inflation and solid growth against the recent tightening in financial conditions.” In their assessment, the policy message will depend on how persuasively the Fed recognises sustained price pressures and resilient activity, while accounting for the effect of tighter market conditions on the wider outlook.
18:00 GMT Fed rate decision: Timing and potential EUR/USD impact
Wednesday’s Fed schedule includes its Interest Rate Decision and Monetary Policy Statement, both due at 18:00 GMT. Afterwards, Fed Chair Kevin Warsh will hold his press conference at 18:30 GMT.
12 of 18 officials forecast one further 25-basis-point (bps) rate increase this year in September’s updated Summary of Economic Projections (SEP). Four members anticipated two increases, while the remaining two expected no further hikes.
Only a 25 bps increase in 2026 was implied by policymakers’ forecasts in June’s dot plot, the SEP component setting out their interest rate projections. Those forecasts then pointed to a 25 bps cut in 2027 and a further 25 bps reduction in 2028.
About a 17% probability of an unchanged year-end policy rate is priced in, according to the CME FedWatch Tool. This positioning leaves scope for fresh USD gains if Warsh departs from his earlier IMF remarks and signals a December increase on the grounds of persistently high inflation. EUR/USD could face immediate selling pressure in that scenario. However, Thursday also brings a policy decision from the European Central Bank (ECB). Any decline in the pair prompted by a hawkish Fed message could therefore pause ahead of the ECB announcement.
With “the final FOMC meeting of the year is not until 9th December,” MUFG/BTMU analysts point out that “the signs of tightening financial conditions continue to build,” leaving “certainly a chance that Fed rate hike expectations for December could ease.” They argue that “the willingness of Warsh to signal the Fed remains on the path highlighted by the dots will be important.” Their broader assessment is that “in circumstances of tightening financial conditions and bond market volatility in Europe we would assume the Dollar will remain underpinned, and the risks remain skewed to the upside.”
A different message from Warsh could put the Greenback under pressure against its major peers. That could happen if he plays down recent inflation developments and avoids signalling a December increase. Reiterating that he will not pre-judge the year’s final meeting could deter investors from fully pricing in a hike, allowing EUR/USD to move higher. Even so, a substantial improvement in inflation figures or a very poor employment report would probably be needed before markets rule out that possibility.
Beneath EUR/USD’s recent resilience, Commerzbank’s Thu Lan Nguyen identifies a less favourable dynamic for the single currency. She observes that “short-term inflation expectations have risen more strongly in the Euro Area than in the US,” while “higher inflation expectations are currently not being offset by a corresponding shift in relative interest-rate expectations.” This gap “is, in principle, a negative signal for the Euro,” according to Commerzbank. It indicates that markets are not allowing for enough policy tightening to offset rising Euro Area inflation expectations, potentially exposing the currency to weakness if sentiment deteriorates.
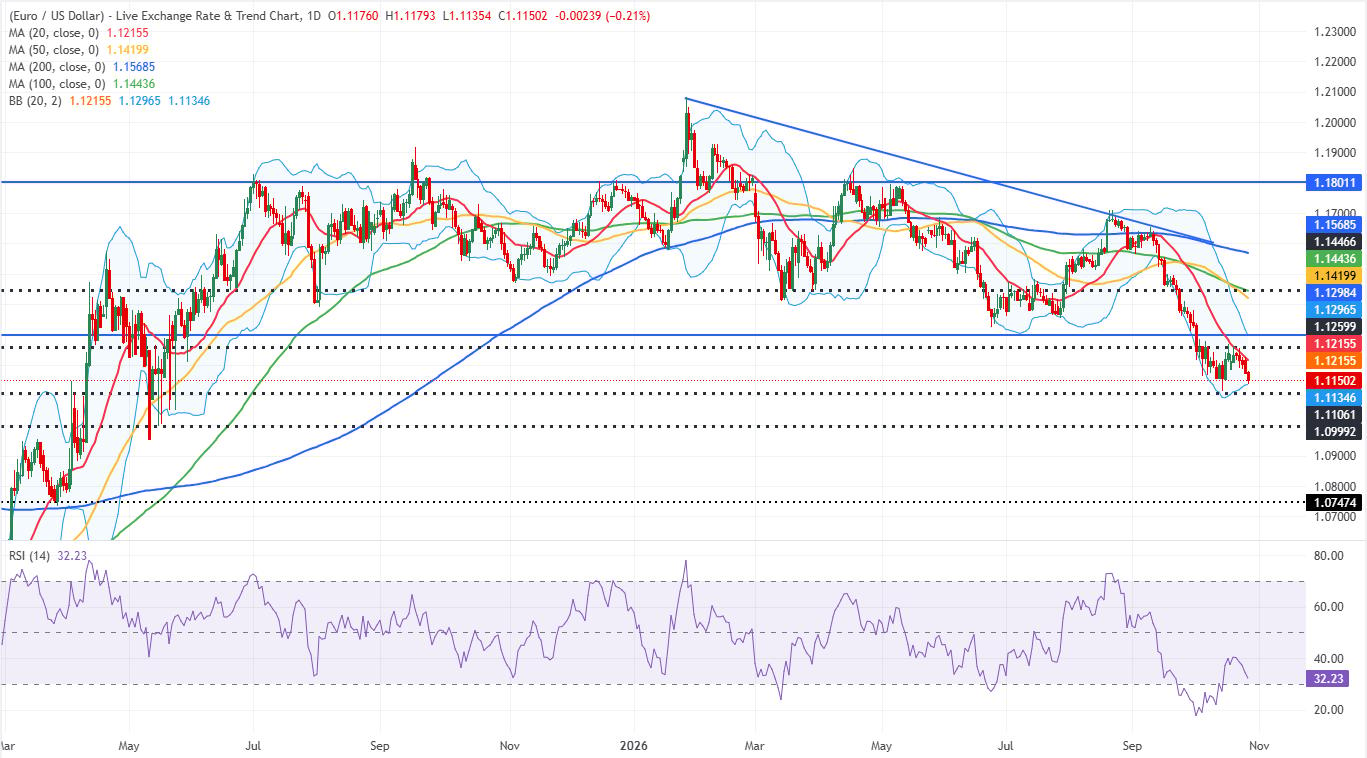
For the short-term EUR/USD technical outlook, FXStreet European Session Lead Analyst Eren Sengezer offers the following assessment:
“The near-term technical outlook for EUR/USD highlights a bearish bias as the pair remains in the lower half of the Bollinger Band on the daily chart and the Relative Strength Index stays well below 40. On the downside, 1.1130-1.1100 (lower limit of the Bollinger Band, static level) aligns as the immediate support level ahead of 1.1000 (psychological level, static level). If this latter support fails, a deeper pullback toward 1.0750 (static level) could be witnessed. If the daily RSI falls into the oversold territory below 30 and EUR/USD stays below the lower limit of the Bollinger Band, investors could wait for a technical correction before committing to an extended decline.”
“Looking north, an interim resistance area could be spotted at 1.1260 - 1.1300 (static level, upper limit of the Bollinger Band). In case the pair manages to stabilize above this region, the 50-day and the 100-day Simple Moving Averages in the 1.1420-1.1440 area could become the next difficult hurdle to clear.”
Fed: Key questions answered
Two mandates guide the Federal Reserve (Fed), which sets US monetary policy: price stability and full employment. Interest rate adjustments are its main means of pursuing these objectives. If prices climb too rapidly and inflation exceeds the Fed’s 2% target, the central bank increases rates. Borrowing becomes more expensive across the economy, while the US becomes a more attractive destination for international investment. The result is a stronger US Dollar (USD). By contrast, inflation below 2% or an excessively high Unemployment Rate may prompt the Fed to cut rates to stimulate borrowing, putting pressure on the Greenback.
Eight times each year, the Federal Reserve (Fed) convenes policy meetings at which the Federal Open Market Committee (FOMC) reviews economic conditions and decides monetary policy. Twelve Fed officials participate in the FOMC: seven Board of Governors members, the Federal Reserve Bank of New York president and four presidents drawn from the other eleven regional Reserve Banks. Those four serve rotating one-year terms.
To restore credit flows in a stalled financial system, the Federal Reserve may use Quantitative Easing (QE) in extreme circumstances. The policy substantially expands the flow of credit. Reserved for crises or exceptionally low inflation, QE is an unconventional policy measure. During the Great Financial Crisis in 2008, it was the Fed’s preferred tool. The central bank creates more Dollars and uses them to purchase high-grade bonds from financial institutions. This process generally weakens the US Dollar.
By reversing QE, quantitative tightening (QT) generally supports the US Dollar’s value. Under QT, the Federal Reserve ceases bond purchases from financial institutions and does not use principal repaid on its maturing bond holdings to buy new bonds.
POPULAR ARTICLES
11.3300: British Pound holds on with UK budget in focus before Fed decision20.7060 Cap in Sight: Australian Dollar Has Room to Gain Against US Dollar – UOB3BoC rate hike offers little traction for Canadian Dollar4United Kingdom: Neutral Budget leaves fiscal risks intact - Deutsche Bank5December risk persists for US Dollar as Fed pauses – BBH6BoC hike matches expectations: Euro firms against CAD as attention turns to ECB7October hold likely, December rate rise anticipated: Federal Reserve outlook - ABN AMRO8New Zealand Dollar: Inflation mounts while RBNZ postpones rate rises – Standard Chartered917-month lows remain close as euro stabilises ahead of Fed rate decision
LIVE QUOTES

Get Started!
Sign up and access the Global Markets in less than 3 minutes

Connect With Us









Contacts
Phone: +61 2 8036 8388
Fax: +61 2 8036 8388
Email: support@tmgm.com



The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved