

Trading
Explore a wide range of markets with competitive pricing, deep liquidity, and advanced trading tools.
Learn More 
Platform
Trade seamlessly with TMGM's powerful platform, built for speed, precision, and a superior trading experience.
Learn More Trading Platform
Academy
Learn the fundamentals of trading with beginner-friendly resources, including guides, webinars, and market insights.
Learn More News & Analysis
Get real-time market updates and expert analysis to stay ahead of trading opportunities
Learn More News & Analysis
About
Learn what sets TMGM apart — our global presence, regulatory strength, and commitment to innovation in trading.
Learn More Why Choose TMGM
Sponsorship
$4,000 gives way: gold retreats despite risk-off sentiment as hawkish Fed expectations weigh
- July low for Gold as hawkish Fed expectations sustain selling pressure.
Gold (XAU/USD) hit $3,965, its lowest since July. The decline came during Friday’s Asian session as expectations of further Federal Reserve (Fed) interest rate increases outweighed the risk-off mood across markets. With rate expectations driving prices, the metal remains under pressure and is heading for a monthly loss. At the time of writing, XAU/USD is near $3,979, a decline of nearly 1% on the day.
Disappointing technology earnings have revived doubts about heavy AI expenditure and whether it will deliver adequate returns, prompting traders to reduce risk. Demand for government bonds is pulling US Treasury yields lower, with the US Dollar also losing ground.
A third consecutive day of losses leaves the US Dollar Index (DXY) near 101.65. The index measures the Greenback against a basket of six major currencies.
Positioning could matter more than fundamentals for the Dollar in the near term, according to analysts at ING. They warn that “the main risk for the dollar today is some precautionary unwinding of net-long positions ahead of Tuesday’s US midterm elections.” The analysts add that “a Democratic sweep is trading around 68% in prediction markets,” describing that outcome as “slightly negative for the US dollar from a few angles, from higher risk of government shutdown and gridlock on debt ceiling negotiations to potential damage to already shaky AI-related sentiment.”
ING consequently warns that “resurgent AI-related jitters and the upcoming US midterms are increasing downside risks for the dollar,” while acknowledging that “a still-hawkish Fed argues against major corrections.”
Reports of a major security breach at cryptocurrency exchange Binance are putting digital assets under pressure and adding to investor unease. Yet the defensive mood has not supported Gold so far. Traders remain focused on rising Oil prices linked to Middle East tensions and the implications for inflation and interest rates.
Concerns that the US may restart military strikes against Iran after next week’s US midterm elections have lifted Oil prices to their highest since May. With West Texas Intermediate (WTI) above $103 a barrel, energy-related inflation risks remain in focus.
The Fed faces a risk that higher energy costs will prolong inflation above its 2% target. Thursday’s data showed September headline Personal Consumption Expenditures (PCE) inflation increasing 0.5% MoM and 3.6% YoY. The core measure rose 0.3% MoM and 3.1% YoY.
Following the Fed’s decision to hold rates steady in October, traders now assign around a 75% probability to a December increase, according to the CME FedWatch Tool. Gold pays no interest, making higher borrowing costs a typical source of pressure on the metal.
Below $4000: XAU/USD faces further downside in technical analysis
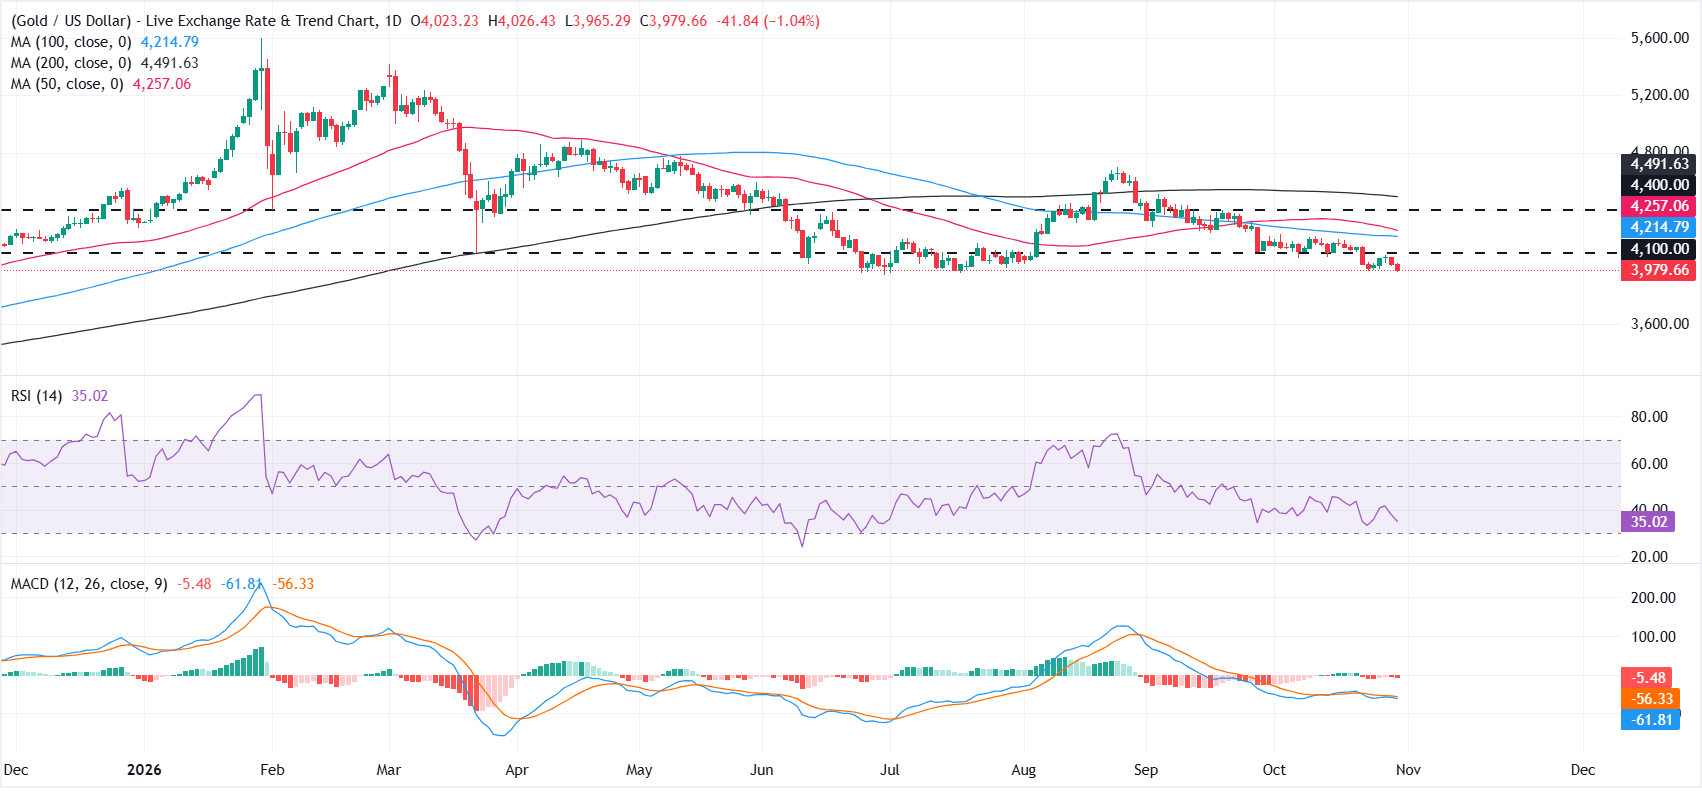
Lower highs and lower lows have defined the daily XAU/USD chart since the late-August peak near $4,700. Sellers retain control as the metal sits beneath its 50-day, 100-day and 200-day Simple Moving Averages (SMAs). Buying interest remains weak, with the Relative Strength Index (RSI) near 34. Meanwhile, a negative Moving Average Convergence Divergence (MACD) reading points to continued downside pressure.
The first resistance level is $4,000, ahead of $4,100. Beyond those levels sit the 100-day SMA near $4,218 and the nearby 50-day SMA at $4,257. A more substantial rebound could put horizontal resistance at $4,400 in view, with the 200-day SMA around $4,491 next.
Below the already-breached $4,000 level, Gold’s nearest support is $3,950, ahead of the July low near $3,941. A clear break beneath this zone would leave scope for additional declines.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
Gold: frequently asked questions
Widely used both to store value and facilitate exchange, Gold has held an important place throughout human history. Beyond its lustre and use in jewellery, the precious metal is now commonly regarded as a safe-haven asset: an investment considered attractive during periods of turmoil. Its independence from any particular issuer or government also underpins its widespread role as a hedge against inflation and currency depreciation.
The largest holders of Gold are central banks. To support their currencies during turbulent periods, they typically diversify reserves and purchase Gold, reinforcing perceptions of economic and currency strength. Substantial Gold reserves can bolster confidence in a country’s solvency. According to the World Gold Council, central banks increased their reserves by 1,136 tonnes in 2022, worth around $70 billion. No larger annual purchase has been recorded. Emerging-economy central banks, including those in China, India and Turkey, are expanding their Gold reserves rapidly.
Both the US Dollar and US Treasuries are major reserve and safe-haven assets, and Gold is inversely correlated with them. Dollar weakness typically supports Gold, allowing investors and central banks to diversify their holdings during turbulent periods. The metal also tends to move in the opposite direction to risk assets. Stock market gains generally weigh on Gold prices, whereas selling in riskier markets tends to support the precious metal.
Numerous factors influence Gold prices. Its safe-haven appeal means geopolitical instability or concerns about a severe recession can trigger rapid gains. Because Gold generates no yield, lower interest rates tend to support it, while higher borrowing costs generally put it under pressure. Even so, the US Dollar (USD) drives most price movements, as Gold is denominated in dollars (XAU/USD). A stronger Dollar usually restrains Gold prices; a weaker Dollar is more likely to lift them.
POPULAR ARTICLES
12.8% in October: Germany’s annual CPI inflation eases2United States: Sticky inflation underpinned by demand – TD Securities3Japanese Yen to remain weak against US Dollar despite hawkish BoJ – ING4Tech sell-off leaves US Dollar Index struggling despite hawkish Fed5$1.20 Defence: Ripple Price Forecast as XRP Bulls Hold Support While Selling Pressure Forces Liquidations6Euro: Limited Policy Divergence Underpins Support Against US Dollar – BBH7Above $103.00: WTI Oil stays near five-month highs amid fresh attacks in the Strait of Hormuz8December hike before a possible pause: European Central Bank – Rabobank9Swiss Franc: Sharp sell-off followed by further gains against US Dollar – UOB

Get Started!
Sign up and access the Global Markets in less than 3 minutes

Connect With Us









Contacts
Phone: +61 2 8036 8388
Fax: +61 2 8036 8388
Email: support@tmgm.com



The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved