

Trading
Explore a wide range of markets with competitive pricing, deep liquidity, and advanced trading tools.
Learn More 
Platform
Trade seamlessly with TMGM's powerful platform, built for speed, precision, and a superior trading experience.
Learn More Trading Platform
Academy
Learn the fundamentals of trading with beginner-friendly resources, including guides, webinars, and market insights.
Learn More News & Analysis
Get real-time market updates and expert analysis to stay ahead of trading opportunities
Learn More News & Analysis
About
Learn what sets TMGM apart — our global presence, regulatory strength, and commitment to innovation in trading.
Learn More Why Choose TMGM
Sponsorship
Two-week low for Indian Rupee as elevated oil prices sustain pressure
- High oil prices drive further Indian Rupee losses against the US Dollar.
- Following elections, a joint military operation against Iran is being prepared by the US and Iran.
- 3.75%-4.00% remained the Fed’s interest rate range on Wednesday.
USD/INR edges up towards 95.30 in Thursday’s opening session. The Indian Rupee (INR) returns to a two-week low against the US Dollar (USD), with persistently high oil prices weighing on the South Asian currency.
At the time of writing, the November 19 MCX Crude Oil contract has fallen 1.5% to around Rs. 9,650. Despite that decline, prices remain near the recent high of Rs. 9,828.
When oil prices are high, currencies of economies heavily dependent on imported oil for their energy requirements, including India, typically lag.
Oil Holds High on Supply Risks
Fears of a further increase in energy supply risks continue to underpin elevated oil prices. Reports suggest Israel and the United States (US) are preparing new attacks on Iran following their respective elections.
According to strategists at Deutsche Bank, oil prices remain broadly higher following a Wall Street Journal (WSJ) report that United States (US) President Donald Trump’s administration had told Gulf states to prepare for a new operation against Iran after the midterms. Danske Bank’s research team identifies another source of geopolitical support: in his post-election address, Israeli Prime Minister (PM) Benjamin Netanyahu raised the possibility of “renewed joint action with President Trump against Iran”.
Energy supply worries are also being reinforced by persistent tensions between Saudi Arabia and the Iran-aligned Houthis. A military spokesperson for Yemen’s Iran-aligned Houthis said on Tuesday that the group had fired a ballistic missile towards the Ras Tanura oil refinery in eastern Saudi Arabia, the kingdom’s largest refinery, according to Reuters.
US Dollar Recovers Following Fed Decision
A modest US Dollar rebound following the Federal Reserve’s (Fed) monetary policy announcement provides additional support for USD/INR. At the time of writing, the US Dollar Index (DXY) is slightly higher at around 102.20. The index measures the Greenback against six major currencies.
Following Wednesday’s Fed decision, the USD Index slipped back towards 102.00, failing to build on its three-day run of gains.
As expected, the Fed maintained its 3.75%-4.00% interest rate range at the meeting and reaffirmed its commitment to achieving price stability. According to Fed Chairman Kevin Warsh, there would be only six monetary policy decisions starting in 2028.
USD/INR Technical Outlook
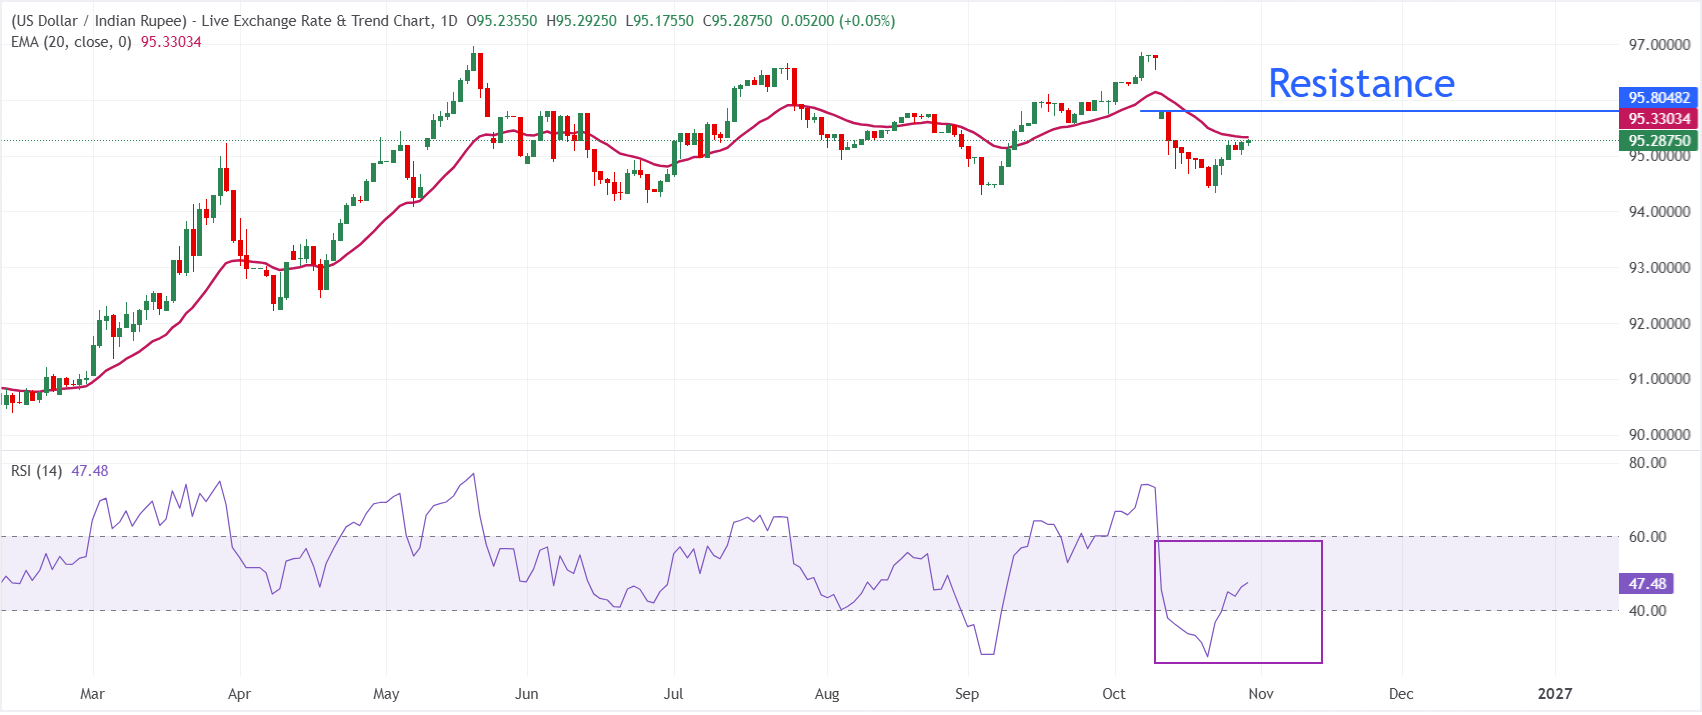
At 95.2875 on the daily chart, USD/INR remains below its 20-day Exponential Moving Average (EMA) of 95.3303, leaving the near-term outlook mildly bearish. Failure to regain this short-term EMA indicates that nearby dynamic resistance continues to constrain rallies. Meanwhile, a Relative Strength Index (RSI) reading around 47 signals neutral-to-soft momentum, rather than oversold conditions, restricting the potential for a sharp rebound.
The 20-day EMA at 95.3303 provides immediate resistance and the first obstacle to a recovery. A sustained move above it would reduce downside pressure and allow a broader consolidation phase. The current dataset offers no clear structural support levels. Traders may therefore watch the recent closing-low area just below 95.10 as an indicative zone where buying demand could return if selling pressure resumes.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
Indian Rupee: Frequently Asked Questions
External developments have a particularly strong influence on the Indian Rupee (INR). Key drivers include Crude Oil prices, given India’s heavy reliance on imported Oil, the US Dollar’s value, as most trade is settled in USD, and foreign investment levels. The Reserve Bank of India (RBI) also plays a major role through direct FX market intervention to stabilise the exchange rate and through the interest rates it sets.
To support trade, the Reserve Bank of India (RBI) intervenes actively in currency markets to keep the exchange rate stable. It also adjusts interest rates in an effort to maintain inflation at its 4% target. Rate increases generally support the Rupee through the ‘carry trade’: investors borrow in lower-interest-rate countries and invest the proceeds in countries offering relatively higher rates, earning the difference.
Inflation, interest rates, economic growth (GDP), the trade balance and foreign investment inflows all help determine the Rupee’s value. Faster growth can attract additional overseas investment and lift demand for the currency. A narrowing trade deficit will eventually strengthen the Rupee. Higher interest rates are also supportive, particularly higher real rates, which are interest rates minus inflation. Greater Foreign Direct and Indirect Investment (FDI and FII) inflows in a risk-on environment can likewise benefit the Rupee.
Inflation generally weighs on the Rupee, especially when it exceeds levels in India’s peer economies, because it reflects a loss of currency value through oversupply. By making exports more expensive, inflation also results in more Rupees being sold to pay for foreign imports, adding pressure on the currency. However, higher inflation typically prompts the Reserve Bank of India (RBI) to raise interest rates. This can support the Rupee by increasing demand from international investors. Lower inflation has the reverse effect.
POPULAR ARTICLES
1Euro drifts lower vs Yen; remains confined in a range ahead of ECB, BoJ policy updates2Japanese Yen: Trading against US Dollar remains range-bound – UOB3Forex Today: Major pairs stay rangebound after Fed as ECB and key US data take focus4Equities: AI trade gains remain intact following hyperscaler earnings – Danske Bank5Euro holds lower against British Pound ahead of ECB decision6New Zealand Dollar: RBNZ surprise leaves limited scope for losses – OCBC7$1.6M by 2036: Why does Bitwise think Bitcoin could reach that level?80.7040 in Focus: AUD/USD Price Forecast as Pair Tests Breakout From Consolidation9Above 102.00: US Dollar Index Price Forecast remains bullish as gains hold


Get Started!
Sign up and access the Global Markets in less than 3 minutes

Connect With Us









Contacts
Phone: +61 2 8036 8388
Fax: +61 2 8036 8388
Email: support@tmgm.com



The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved