

Trading
Explore a wide range of markets with competitive pricing, deep liquidity, and advanced trading tools.
Learn More 
Platform
Trade seamlessly with TMGM's powerful platform, built for speed, precision, and a superior trading experience.
Learn More Trading Platform
Academy
Learn the fundamentals of trading with beginner-friendly resources, including guides, webinars, and market insights.
Learn More News & Analysis
Get real-time market updates and expert analysis to stay ahead of trading opportunities
Learn More News & Analysis
About
Learn what sets TMGM apart — our global presence, regulatory strength, and commitment to innovation in trading.
Learn More Why Choose TMGM
Sponsorship
EUR/USD Price Forecast: Why are fears of aggressive Fed tightening lifting the US Dollar?
- EUR/USD slips into marginal losses after surrendering early gains before the US CPI release.
- A warning from Fed’s Waller about aggressive tightening if October core CPI accelerates drives a sharp US Dollar recovery.
- Upside inflation risks prompt ECB’s Lane to back a December interest rate increase.
Renewed US Dollar (USD) strength pushes the Euro (EUR) marginally lower near 1.1220 in Tuesday’s European trading, wiping out the single currency’s earlier gains. The reversal in the major currency pair follows a warning that the Federal Reserve (Fed) could tighten monetary policy aggressively should inflationary pressures in the United States (US) keep building.
An early decline in the US Dollar Index (DXY) also reversed during European trading, with the index edging into positive territory above 101.70. The index tracks the Greenback against six major currencies.
Speaking during European trading, Fed Governor Christopher Waller said: “Half-point Fed rate hike may be needed in December, if October core CPI inflation comes in around 0.3% or higher,”
Could inflation concerns prompt Waller’s half-point December hike?
A notably hawkish message from Fed’s Waller lifted the FXS Speechtracker score to 9/10, against a historical average of 7.3/10, marking a clear strengthening of the tightening bias relative to the established baseline. Waller explicitly backed a half-point Fed rate increase in December if October core CPI comes in at around 0.3% or higher, while supporting at least a quarter-point increase even if the data improve. That stance indicates little tolerance for any renewed deviation from the inflation target. His focus on broad-based price rises, expectations of additional producer price pressures and assessment that policy has been less restrictive than previously believed all point to likely further rate increases. The message is that real rates need to rise to bring inflation back under control, a setting that typically favours the Dollar while weighing on risk-sensitive assets.
With a 3.17-point increase to 145.50, the FXS Fed Sentiment Index moved further into hawkish territory, comfortably above the neutral 100 mark and consistent with the high FXS Speechtracker score. Together, the readings suggest renewed determination to tighten policy. If forthcoming inflation figures do not demonstrate convincing progress towards the Fed’s target, traders are likely to price in a greater probability of a higher terminal rate and a stronger trajectory for the Dollar.
Attention now turns to October’s US Consumer Price Index (CPI) figures, scheduled for release at 13:30 GMT.
Will US inflation ease before the key Fed meeting?
A marked easing in price pressures is now expected by economists at Deutsche Bank, following September’s strong reading. Explaining their outlook, they note that “this time, our US economists expect inflation to have come down from its September pace, with both headline and core at +0.20% on the month,” pointing to a more moderate October CPI backdrop ahead of the next Fed meeting.
For the Euro, support for further monetary tightening has also come from European Central Bank (ECB) officials.
Can Lane’s hawkish stance support Euro bulls as inflation risks persist?
At 7.6, compared with a historical average of 6.3, the FXS Speechtracker score indicates that this speech had a greater-than-usual impact and a distinctly hawkish slant. References to Europe’s “reassuring” resilience, alongside the call for French fiscal problems to be addressed in Paris, suggest little tolerance for fiscal slippage and favour a firmer Euro.
Upside inflation risks are reinforced by guidance that core and food price inflation will accelerate, with year-end inflation likely to be “a little bit” above 4% and “more to come” before inflation peaks. The observation that a December rate increase would be prudent unless the data change underpins expectations of additional tightening. This supports the Euro through interest rate differentials while leaving rate-sensitive assets under pressure.
EUR/USD Technical Analysis: Can Near-Term Support Hold?
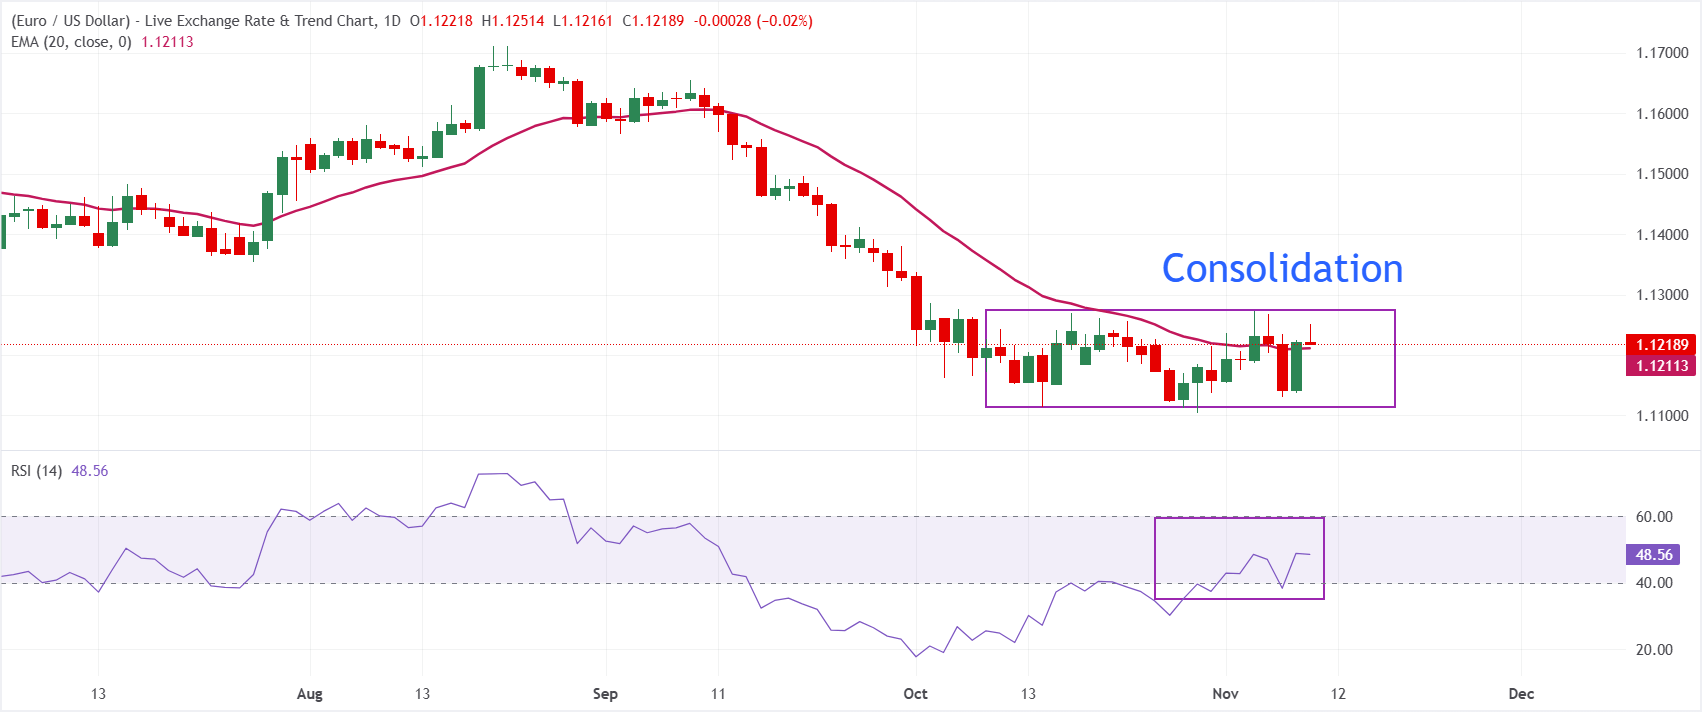
Trading at 1.1219 on the daily chart, EUR/USD retains a mildly positive near-term outlook. Its position just above the 20-day exponential moving average (EMA) of 1.1211 points to support developing around the recent breakout zone. Meanwhile, the Relative Strength Index (RSI) reading of 48.6 is close to neutral, suggesting that downward momentum has eased without indicating either overbought conditions or a strong directional trend.
The first support on a decline lies near the 20-day EMA at 1.1211. A daily close beneath this level would leave the pair vulnerable to a deeper correction and undermine its current stabilisation. Conversely, holding above this moving average on a sustained basis would preserve the short-term structure, keeping buyers in control as momentum consolidates.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
Economic Data Indicator
Consumer Price Index excluding Food & Energy (MoM)
The Consumer Price Index (CPI) tracks inflationary or deflationary trends by periodically adding together the prices of a representative basket of goods and services. Compiled monthly, the figures are published by the US Department of Labor Statistics. The MoM reading compares goods prices in the reference month with those in the preceding month. By leaving out the more volatile components, the CPI excluding Food & Energy offers a more accurate gauge of underlying price pressures. A high reading is generally regarded as positive for the US Dollar (USD), whereas a low reading is viewed as negative.
Read further.Next publication: Tue, 10 Nov 2026 13:30
Release frequency: Every month
Consensus estimate: 0.2%
Previous reading: 0.3%
Data source: US Bureau of Labor Statistics
Persistent inflationary pressures have prompted action by the US Federal Reserve, which is expected to retain an aggressive policy stance for the foreseeable future. Supply-chain disruptions and bottlenecks continue to push prices higher, leaving the Consumer Price Index (CPI) at multi-decade highs. The central bank’s dual mandate calls for price stability and maximum employment, with inflation intended to stay around 2% YoY. Since the onset of the pandemic, which continues to affect the world, inflation has become the weakest pillar of that mandate.
POPULAR ARTICLES
1Will Australia’s Unemployment Rate Remain at 4.7% as Expected?2Singapore Dollar: Can Export Support Sustain a Stable Range? – Commerzbank3Indonesian Rupiah: Why has BI’s surprise hike eased pressure only partly? – BBH4Singapore Dollar: What do US yields mean for SGD recovery prospects? - OCBC5Chinese Yuan: Is a gradual rise towards 6.6520 against the US Dollar likely? – UOB6Silver Price Forecast: What does an oversold RSI signal as the downtrend intensifies?7United Kingdom: Societe Generale forecasts inflation peak of 4.5% in Q1 20278US Dollar: Is Upside Pressure Building on Fed Tightening Expectations? – ING9Why has the New Zealand Dollar hit pandemic-era lows as Fed and RBNZ policies diverge?


Get Started!
Sign up and access the Global Markets in less than 3 minutes

Connect With Us









Contacts
Phone: +61 2 8036 8388
Fax: +61 2 8036 8388
Email: support@tmgm.com



The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved