

Сауда
Бәсекеге қабілетті бағалар, жоғары өтімділік және озық сауда құралдары арқылы нарықтардың кең ауқымын зерттеңіз.
Толығырақ 
Платформа
TMGM-нің жылдамдыққа, дәлдікке және жоғары деңгейлі сауда тәжірибесіне арналған қуатты платформасымен сауданы кедергісіз жүргізіңіз.
Толығырақ Сауда платформасы
Академия
Бастауыштарға арналған нұсқаулықтар, вебинарлар және нарық талдаулары сияқты ресурстар арқылы сауданың негіздерін үйреніңіз.
Толығырақ TMGM Академиясы
Жаңалықтар және талдау
Сауда мүмкіндіктерінен алда болу үшін нақты уақыттағы нарық жаңартулары мен сараптамалық талдауды алыңыз
Толығырақ Жаңалықтар және талдау
Туралы
TMGM-ді ерекшелендіретін жайттарды біліңіз — біздің жаһандық ауқымымыз, реттеушілік беріктігіміз және трейдингтегі инновацияларға деген адалдығымыз.
Толығырақ Неліктен TMGM-ді таңдау керек
ADP Employment Report expected to show slower job growth in October
- The US ADP Employment Change report is forecast to show a 69K increase in net jobs in October.
- Barring a strong disappointment, October’s ADP is unlikely to hurt confidence in the upbeat US economic momentum.
- The impact on the US Dollar is likely to be limited, with the outcome of the midterm elections front and center and ahead of the NFP report on Friday.
The Automatic Data Processing (ADP) Research Institute is due to release October’s private-sector employment report on Wednesday. The market consensus anticipates a moderate slowdown in job creation, with the ADP Employment Change expected to show 69K new private jobs in October, down from 90K in September.
ADP data is closely watched by financial markets, as it sets the stakes for the all-important Nonfarm Payrolls (NFP) report, normally released a couple of days later by the US Bureau of Labor Statistics (BLS). On Wednesday, however, the ADP report will have to share the spotlight with the US ISM Services Purchasing Managers Index (PMI) and, above all, market speculation about the consequences of the Democrats' victory in the US midterm elections.
ADP Jobs Report set to show lower employment growth but a solid labour market
October’s ADP employment report comes after a string of strong US macroeconomic releases that have boosted investors’ confidence in the US economic outlook. Preliminary Gross Domestic Product (GDP) data released last week shows that the economy grew at a 3.4% annualised rate in the third quarter, with consumer spending, investment and government expenditure leading growth.
Beyond that, Monday’s US ISM Manufacturing PMI showed factory activity accelerated beyond expectations, suggesting that the economy entered the fourth quarter on a strong footing.
All this supports the theory of US economic exceptionalism, which, coupled with the strong inflation pressures, provides the ideal scenario for the Federal Reserve (Fed) to tighten its monetary policy further. According to the CME FedWatch tool, futures markets are pricing in a 75% chance of another quarter-point rate hike in December, a scenario that is keeping the US Dollar Index (DXY) relatively steady near year-to-date highs.
Against this background, October’s ADP employment report should show a strong setback to cause a major disruption. September’s Nonfarm Payrolls report showed a 29K increase in employment following 133K new jobs in August, which suggests that the labour market is stabilising, with no clear signs of a decline so far.
That said, the Greenback might remain on the defensive on Wednesday, amid the consequences of the sound Democratic win in the US midterm elections. Francesco Pesole, Analyst at ING assesses that “a Democratic sweep (...) could be seen as slightly negative for the US Dollar from a few angles, from higher risk of government shutdown and gridlock on debt ceiling negotiations to potential damage to already shaky AI-related sentiment.”
When will the ADP report be released, and how could it affect the US Dollar?
The US ADP Employment Change report will be out on Wednesday at 13:15 GMT, and it is expected to show that the private sector created 69K new jobs in October. The final data is unlikely to alter market expectations of a Fed rate hike in December, and therefore, its impact on the US Dollar (USD) is likely to be limited, with markets focused on the outcome of the midterm elections ahead of the all-important NFP report on Friday.
A few hours later on Wednesday, the US ISM Services PMI is expected to show a mild slowdown in October, yet at levels consistent with expansion and solid business activity in the sector. Again, it would require very disappointing figures to dent markets’ confidence in the strength of the US economy.
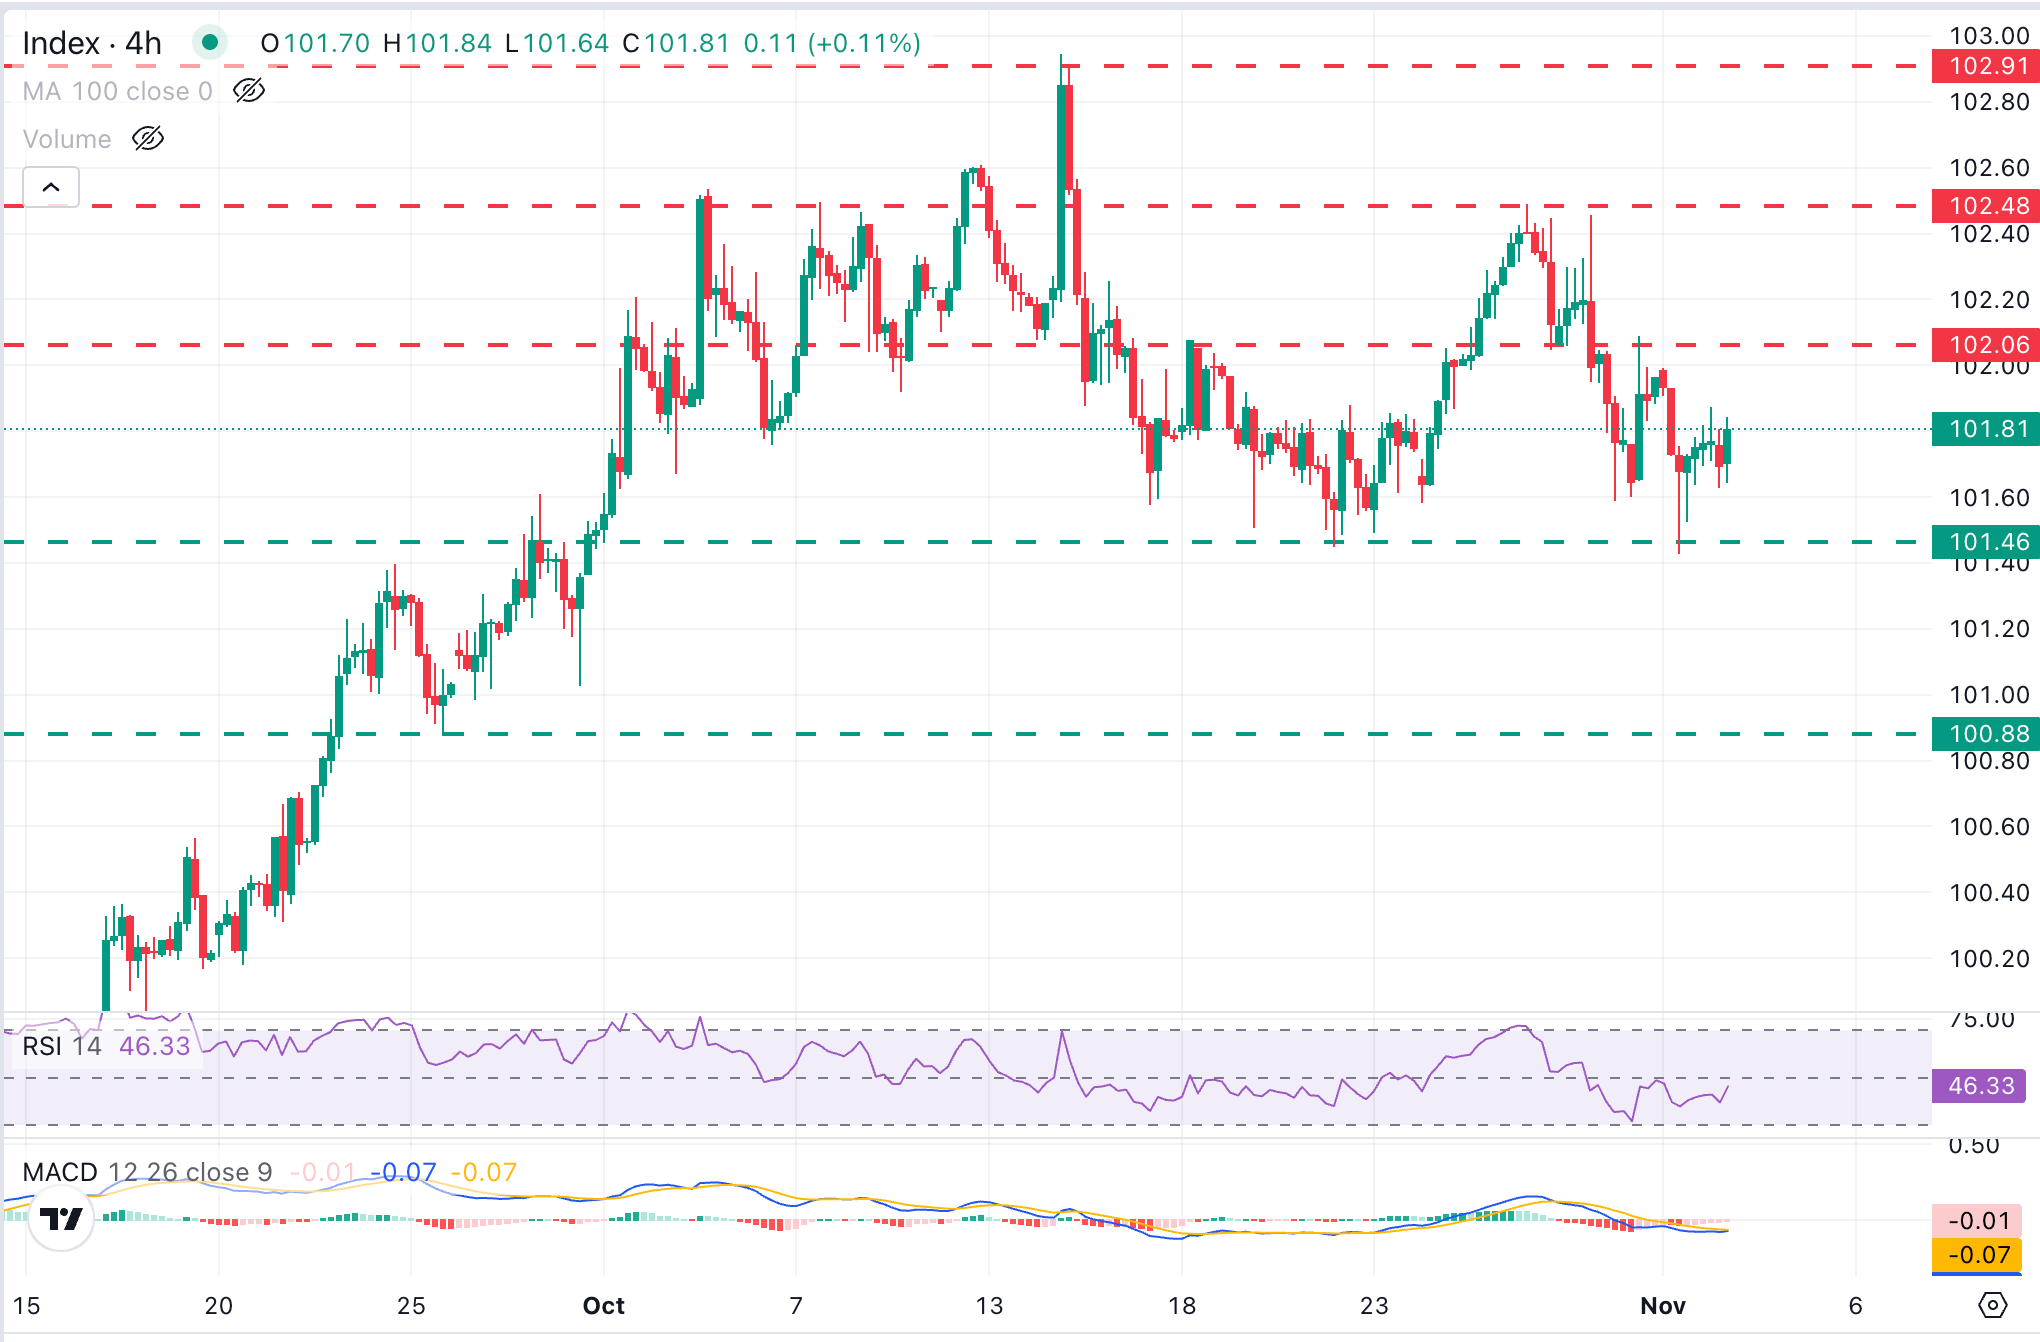
The US Dollar Index (DXY) technical picture shows the index hovering within the lower end of its trading range since early October, with the 4-hour chart showing a neutral-to-bearish near-term tone. The Relative Strength Index (14) sits below the mid-50 area, hinting at subdued directional conviction, while the Moving Average Convergence Divergence (MACD) histogram remains negative, all in all highlighting mild bearish pressure rather than a decisive negative trend.
According to Guillermo Alcalá, FX analyst at FXStreet, the DXY should break support at the 101.50 area (October 22 and November 2 lows) to confirm a trend shift and clear the path towards the late-September lows between 101.00 and 100.90.
On the upside, Alcalá sees the October 30 high, just above 102.00, and the October 28 and 29 highs around 102.50 as major resistances ahead of the 18-month high, at 102.95, hit in mid-October.
Employment FAQs
Labor market conditions are a key element to assess the health of an economy and thus a key driver for currency valuation. High employment, or low unemployment, has positive implications for consumer spending and thus economic growth, boosting the value of the local currency. Moreover, a very tight labor market – a situation in which there is a shortage of workers to fill open positions – can also have implications on inflation levels and thus monetary policy as low labor supply and high demand leads to higher wages.
The pace at which salaries are growing in an economy is key for policymakers. High wage growth means that households have more money to spend, usually leading to price increases in consumer goods. In contrast to more volatile sources of inflation such as energy prices, wage growth is seen as a key component of underlying and persisting inflation as salary increases are unlikely to be undone. Central banks around the world pay close attention to wage growth data when deciding on monetary policy.
The weight that each central bank assigns to labor market conditions depends on its objectives. Some central banks explicitly have mandates related to the labor market beyond controlling inflation levels. The US Federal Reserve (Fed), for example, has the dual mandate of promoting maximum employment and stable prices. Meanwhile, the European Central Bank’s (ECB) sole mandate is to keep inflation under control. Still, and despite whatever mandates they have, labor market conditions are an important factor for policymakers given its significance as a gauge of the health of the economy and their direct relationship to inflation.
Economic Indicator
ADP Employment Change
The ADP Employment Change is a gauge of employment in the private sector released by the largest payroll processor in the US, Automatic Data Processing Inc. It measures the change in the number of people privately employed in the US. Generally speaking, a rise in the indicator has positive implications for consumer spending and is stimulative of economic growth. So a high reading is traditionally seen as bullish for the US Dollar (USD), while a low reading is seen as bearish.
Read more.Next release: Wed Nov 04, 2026 13:15
Frequency: Monthly
Consensus: 69K
Previous: 90K
Source: ADP Research Institute
Traders often consider employment figures from ADP, America’s largest payrolls provider, report as the harbinger of the Bureau of Labor Statistics release on Nonfarm Payrolls (usually published two days later), because of the correlation between the two. The overlaying of both series is quite high, but on individual months, the discrepancy can be substantial. Another reason FX traders follow this report is the same as with the NFP – a persistent vigorous growth in employment figures increases inflationary pressures, and with it, the likelihood that the Fed will raise interest rates. Actual figures beating consensus tend to be USD bullish.
Үздік мақалалар
1Gold reclaims $4,000 as Democrats’ Congress win rattles US Dollar2British Pound extends rally as Republicans lose both US Houses3Polish Zloty: NBP caution keeps Zloty under pressure – Commerzbank4Crypto Today: Bitcoin, Ethereum, XRP extend advance as US Dollar slides on Democrats' US midterm victory5Euro extends gains nearing four-week highs amid hot Eurozone Inflation figures6Pi Network Price Forecast: Bullish breakout hopes fade as PI approaches record lows7Eurozone flash HICP grows faster by 4% YoY in October, as expected8Swedish Krona: Riksbank hikes support SEK – Societe Generale9Silver Price Forecast: XAG/USD rallies to $52.00 amid lower yields, weak US Dollar

Бастау!
Тіркеліп, 3 минуттан аз уақытта жаһандық нарықтарға қол жеткізіңіз

Бізбен байланысыңыз









Байланыстар
Телефон: +61 2 8036 8388
Факс: +61 2 8036 8388
Эл. пошта: support@tmgm.com



Осы веб-сайтта берілген ақпарат тек жалпы сипатта ғана ұсынылады және жеке қаржылық кеңес болып табылмайды. Осы веб-сайттағы кез келген ақпаратқа сүйенбес бұрын, оның сіздің мақсаттарыңызға, қаржылық жағдайыңызға және қажеттіліктеріңізге сәйкестігін бағалауыңыз керек. CFD және FX Margin Contracts-қа инвестиция салу елеулі тәуекелдермен байланысты және барлық инвесторлар үшін қолайлы емес. Сіз бастапқы салымыңыздан артық қаражат жоғалтуыңыз мүмкін. Сіз базалық активке ешқандай меншік құқығына немесе үлеске ие болмайсыз. Сауда жасамас бұрын тәуелсіз кеңес алуды және тәуекелдерді толық түсінуді ұсынамыз. Веб-сайтта көрсетілген кез келген өнімді сатып алмас бұрын, ақпараттық құжатты оқып, оны мұқият қарастыру маңызды. Осы веб-сайтта ұсынылған ақпарат пен жарнамалар жергілікті заңдар мен ережелерге қайшы келетін кез келген елде немесе юрисдикцияда тұратын адамдардың пайдалануына арналмаған. Осы веб-сайтта ұсынылатын Өнімдер мен Қызметтер Америка Құрама Штаттары, Малайзия және Таиланд тұрғындарына арналмаған.
TMGM әртүрлі юрисдикцияларда уәкілетті және реттеледі.
Trademax Australia Limited, TMGM атауымен жұмыс істейді, Австралияның Бағалы қағаздар және инвестициялар жөніндегі комиссиясымен (ASIC) реттеледі, AFSL № 436416 және мына мекенжайда орналасқан: Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Электрондық пошта: support@tmgm.com.au
Trademax Global Limited, TMGM атауымен жұмыс істейді, Вануату Қаржылық қызметтер комиссиясымен (VFSC) уәкілетті және реттеледі, тіркеу нөмірі 40356, тіркелген мекенжайы: 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Электрондық пошта: support@tmgm.com
Trademax Global Markets (SE) Limited, TMGM атауымен жұмыс істейді, Сейшел аралдарының Қаржылық қызметтер басқармасы (FSA) тарапынан уәкілетті және реттеледі, лицензия нөмірі SD224. Компания мына мекенжайда тіркелген: Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Электрондық пошта: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, TMGM атауымен жұмыс істейді, Mauritius Қаржылық қызметтер комиссиясымен (FSC) № GB22201012 лицензиясы бойынша уәкілетті және реттеледі, тіркелген мекенжайы: 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Электрондық пошта: support@tmgm.com
Авторлық құқық © TMGM. Барлық құқықтар қорғалған