

Trading
Explore a wide range of markets with competitive pricing, deep liquidity, and advanced trading tools.
Learn More 
Platform
Trade seamlessly with TMGM's powerful platform, built for speed, precision, and a superior trading experience.
Learn More Trading Platform
Academy
Learn the fundamentals of trading with beginner-friendly resources, including guides, webinars, and market insights.
Learn More News & Analysis
Get real-time market updates and expert analysis to stay ahead of trading opportunities
Learn More News & Analysis
About
Learn what sets TMGM apart — our global presence, regulatory strength, and commitment to innovation in trading.
Learn More Why Choose TMGM
Sponsorship
103.70: United States Dollar Index pulls back from 19-month high, retains bullish outlook
- 103.53 is the US Dollar Index’s latest level, approximately. It has eased from a 19-month peak of 103.70.
- Further interest rate increases are needed to curb upside inflation risks, several Fed policymakers have warned.
- Three successive Fed rate rises are priced into markets, according to MUFG.
103.53 is the US Dollar Index’s approximate level at the time of writing. After reaching a 19-month high of 103.70, the index is trading slightly lower. The US Dollar (USD) has entered a correction following an extension of its rally during Tuesday’s Asian session. The US Dollar Index (DXY) measures the Greenback against a basket of six major currencies.
Persistent inflation has convinced financial markets that the Federal Reserve (Fed) will maintain a prolonged monetary tightening cycle. Those expectations have helped the Greenback outperform its currency peers over recent weeks.
Recent comments from several Fed officials have also underscored their considerable concern over elevated inflation pressures.
7.1/10: Hammack warns of broader inflation, favours smaller rate rises
A FXS Speechtracker score of 7.1/10 put Fed’s Hammack’s Monday remarks slightly below the historical average of 7.6/10. The message remained moderately hawkish, with inflation risks clearly in focus. Hammack highlighted inflation “going in the wrong direction,” a widening of price pressures and greater willingness among businesses to pass on price increases. Together, these points reflect concern that underlying inflation dynamics remain problematic. Nevertheless, Hammack again favoured steady, smaller rate increases that give the economy time to adjust. Describing financial conditions as “still not restraining the economy” and arguing that the economy can withstand additional restraint reinforced the preference for further tightening, with the 2% inflation objective firmly intact.
At 147.36, the FXS Fed Sentiment Index recorded a 0.00-point change. Despite the slightly softer FXS Speechtracker reading, the speech therefore left the overall hawkish stance unchanged. The sentiment index remains comfortably above 100, confirming that Fed communication is still hawkish. That position reflects continued concern over inflation and the need to restrain the economy through higher market borrowing costs.
Kansas City Fed President Jeffrey Schmid voiced similar concerns over the weekend, saying, “Inflation is running too hot,” and that the central bank “has some work to do on inflation”.
7/10: Schmid’s inflation warning reinforces Fed’s hawkish tilt
Scoring 7/10 on FXS Speechtracker against a historical average of 6.9/10, Fed’s Schmid struck a distinctly hawkish tone that highlighted mounting concern about persistent price pressures. Schmid said containing inflation has “only gotten harder,” with inflation “uncomfortably above” the 2% target and still near 3% when energy is excluded. The message was that the Fed “has some work to do on inflation”, although the labour market was described as broadly balanced rather than a principal source of current price pressures. Schmid stressed demand management and rejected targeting individual prices, including those of AI-related technology goods. The assertion that influencing any single good or service is not the Fed’s role further supports a broad, policy-led approach to reducing inflation, a stance favourable to the Dollar.
An increase of 1.00 points took the FXS Fed Sentiment Index to 148.44, keeping it firmly in hawkish territory. That move matches the slightly above-baseline tone registered by FXS Speechtracker. Although Schmid did not explicitly advocate immediate tightening, market participants are likely to read the comments as leaving the Fed’s policy response tilted towards additional restraint. Such a backdrop typically supports the Dollar against the Euro and Yen.
The US rates market now reflects the sharp hawkish reassessment of Fed policy, analysts at MUFG/BTMU note. They highlight that it is "assigning a higher probability to three consecutive hikes in December, January and March, which would lift the effective Fed funds rate towards 4.6%."
103.52: US Dollar Index Technical Outlook
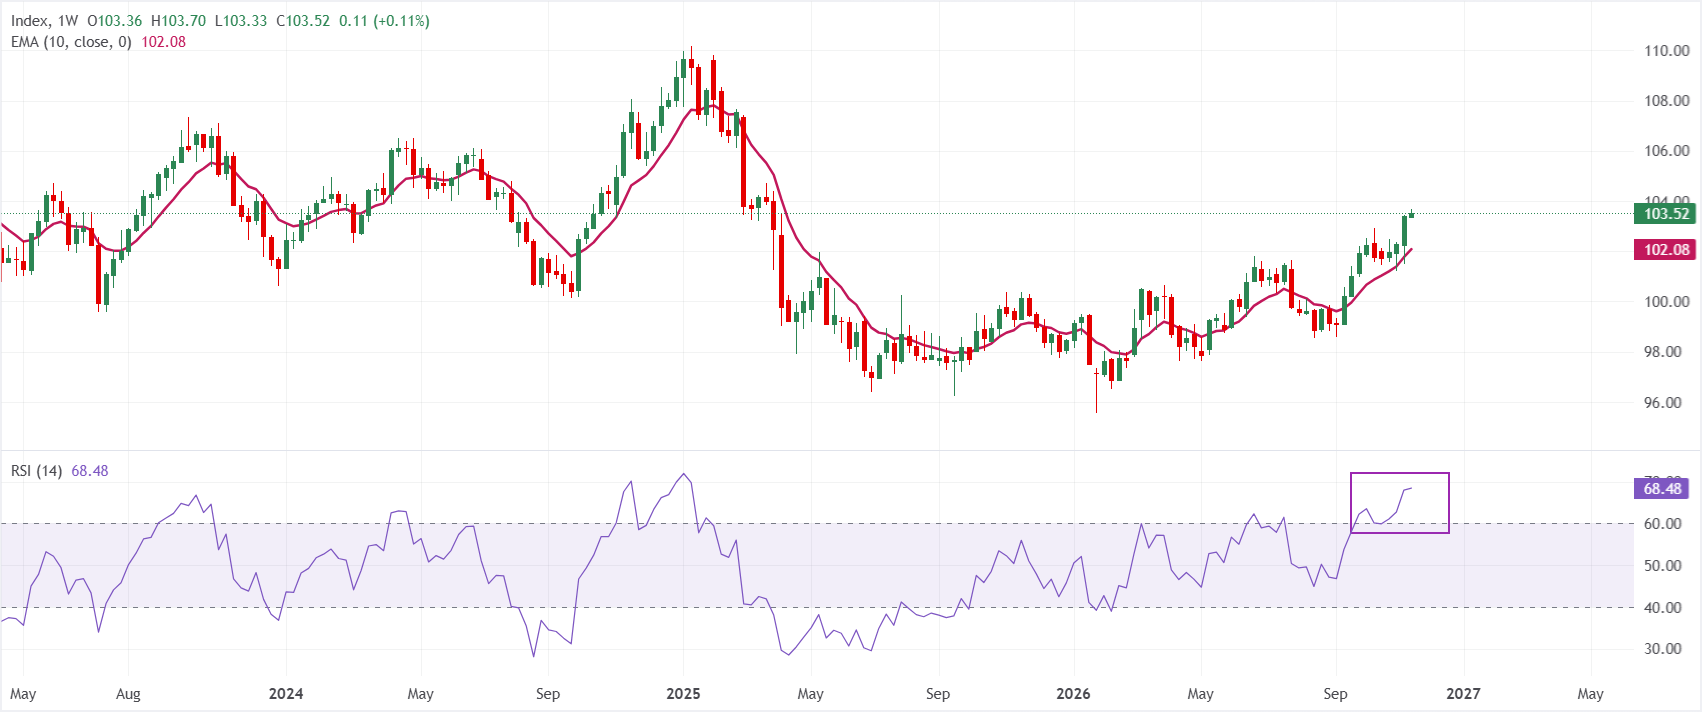
At 103.52 on the weekly chart, Dollar Index Spot remains above its 10-week exponential moving average (EMA) of 102.08. The near-term structure is therefore still bullish, with the index edging further above trend support. A Relative Strength Index (RSI) reading of 68.46 is just short of overbought territory. It points to strong upward momentum, although early signs of stretched conditions are emerging.
The 104.00 level represents the main upside obstacle. Below current levels, the first support lies at the 10-week EMA of 102.08. A corrective retreat would be expected to stabilise there, provided buyers continue to defend this dynamic support.
Fed: Key Questions Answered
The Federal Reserve (Fed) sets US monetary policy with two objectives: stable prices and full employment. Interest rate adjustments are its main tool for meeting those mandates. If prices increase too rapidly and inflation exceeds the Fed’s 2% target, the central bank raises rates. Higher borrowing costs across the economy make the US more attractive to international investors, strengthening the US Dollar (USD). Conversely, inflation below 2% or an excessively high unemployment rate may prompt the Fed to cut rates to stimulate borrowing. This puts pressure on the Greenback.
Eight times a year, the Federal Reserve (Fed) convenes policy meetings at which the Federal Open Market Committee (FOMC) reviews economic conditions and determines monetary policy. Twelve Fed officials attend the FOMC: seven Board of Governors members, the president of the Federal Reserve Bank of New York, and four presidents drawn from the other eleven regional Reserve Banks. The latter serve rotating one-year terms.
When conditions are extreme, the Federal Reserve may use Quantitative Easing (QE) to substantially expand credit flows through a financial system that has become blocked. This unconventional policy is deployed during crises or periods of exceptionally low inflation. During the Great Financial Crisis in 2008, it was the Fed’s preferred tool. Under QE, the Fed prints additional Dollars to purchase high-grade bonds from financial institutions. The policy generally weakens the US Dollar.
By reversing QE, quantitative tightening (QT) typically supports the US Dollar’s value. Under QT, the Federal Reserve halts bond purchases from financial institutions. It also refrains from using principal repaid on maturing bond holdings to buy new bonds.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
POPULAR ARTICLES
1Australia Unemployment Rate expected to remain at 4.7% 2Singapore Dollar: Export support underpins stable trading range outlook – Commerzbank3Indonesian Rupiah: Limited pressure relief from surprise BI rate hike – BBH4US yields steer Singapore Dollar (SGD) recovery outlook - OCBC56.6520 in View as Chinese Yuan Shows Gradual Upside Bias Against US Dollar – UOB6Silver Price Forecast: RSI turns oversold as downtrend intensifies74.5% inflation peak forecast for United Kingdom in Q1 2027 - Societe Generale8US Dollar: Fed tightening expectations fuel upside pressure – ING9Pandemic-era lows for New Zealand Dollar as Fed and RBNZ policy paths diverge


Get Started!
Sign up and access the Global Markets in less than 3 minutes

Connect With Us









Contacts
Phone: +61 2 8036 8388
Fax: +61 2 8036 8388
Email: support@tmgm.com



The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved