
News & AnalysisCareer

A recovery from the previous day’s six-month low of 93.25 leaves USD/INR marginally higher near 93.50 in early trading on Thursday. The move interrupts an almost six-week advance by the Indian Rupee (INR) against the US Dollar (USD).
Concerns that the Federal Reserve (Fed) will raise interest rates several times in the near term have prolonged the US Dollar’s advance, helping USD/INR recover ground.
During Asian trading, a fresh 19-month high near 104.00 is reached by the US Dollar Index (DXY), which measures the Greenback against a basket of six major currencies.
Interest rate increases of 25 basis points (bps) at both the December and January policy meetings are considered almost certain, according to the CME FedWatch Tool. It also puts the probability of a further increase in March 2027 at almost 50%.
Released on Wednesday, the minutes of the Federal Open Market Committee’s (FOMC) October policy meeting revealed explicit support among policymakers for additional interest rate rises. They also cautioned that “inflation may be more persistent than anticipated”.
A couple of policymakers also warned that a larger interest rate increase could be warranted at the December meeting if inflation data continued to be negative, the minutes showed.
Describing the Indian Rupee as “the surprise star performer in EMs this month,” analysts at Societe Generale say its advance has been “powered by FPI inflows” as investors diversify their market bets beyond “AI-themed markets like South Korea and Taiwan.” A further source of support for sentiment, they add, has been “optimism over Iran truce following US midterm election that has deflated Brent towards $90/b,” bolstering the favourable backdrop for INR.
Across every full trading day so far in November, Foreign Institutional Investors (FIIs) have been net buyers, adding holdings worth Rs. 94,229.56 crore.
Easing concerns about risks to energy supplies from the Middle East have also pushed oil prices lower, which is expected to help limit the INR’s losses. At the time of writing, the MCX Crude Oil contract expiring on 18 December is trading near Rs. 7,709, up 0.78%, although it remains close to its 11-week low of Rs. 7,850.
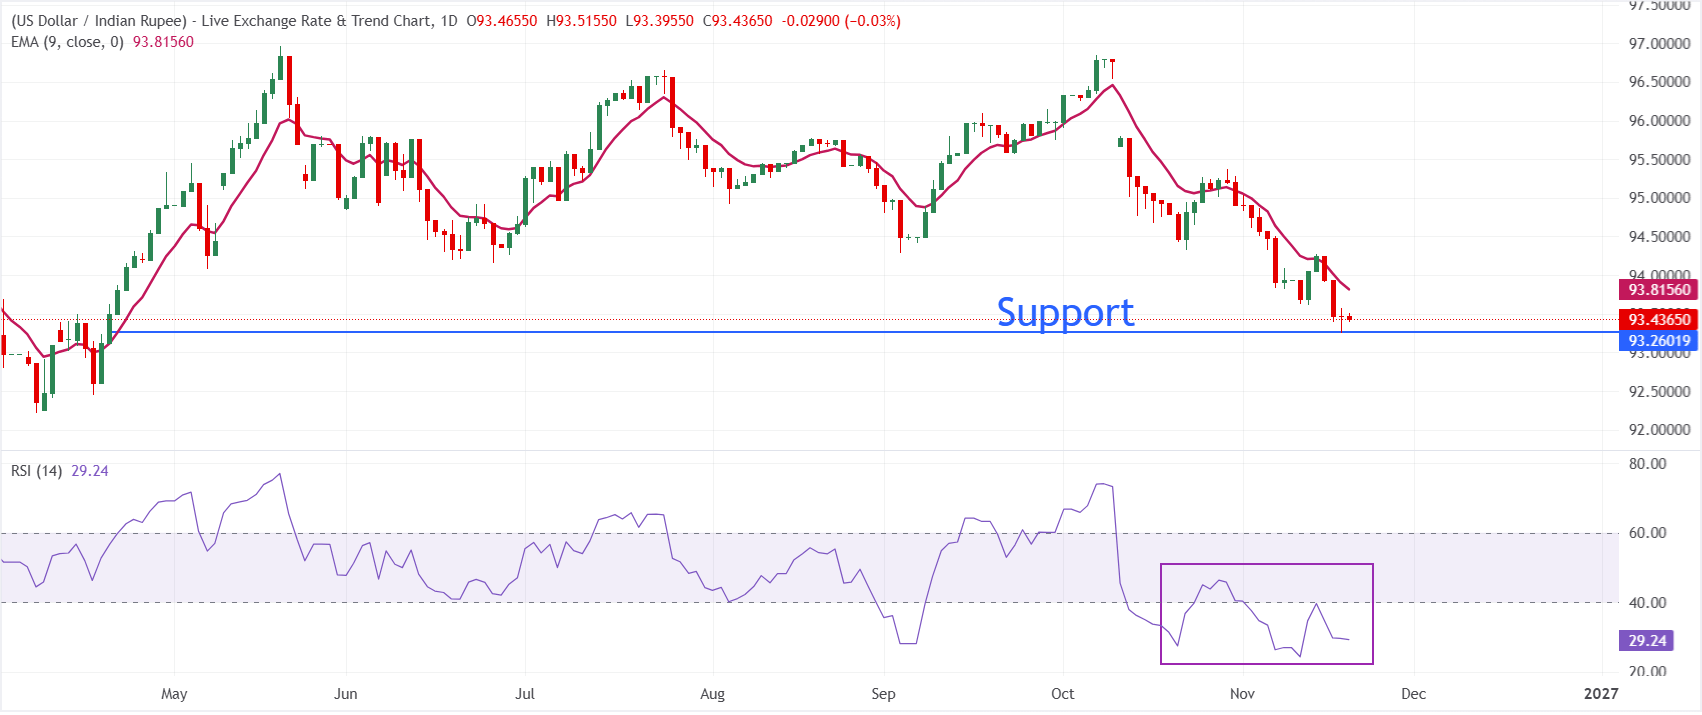
Trading at 93.44 on the daily chart, USD/INR retains a bearish near-term bias below its 9-period exponential moving average (EMA) of 93.82. That moving average continues to act as dynamic resistance overhead. Meanwhile, a Relative Strength Index (RSI) reading of 29.24 places the pair in oversold territory, suggesting that although the decline is stretched, sellers remain in control of the short-term structure.
A recovery above the 9-period EMA at 93.82, the nearest resistance to monitor, would be needed to temper the bearish bias and create scope for a corrective rebound. Initial support lies at the 18 November low of 93.25, followed by the key 93.00 level.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
External developments have a particularly strong influence on the Indian Rupee (INR). Among the main drivers are Crude Oil prices, given India’s heavy reliance on imported Oil, the US Dollar’s value, as most trade is settled in USD, and the scale of foreign investment. Interest rates set by the Reserve Bank of India (RBI), together with its direct intervention in FX markets to stabilise the exchange rate, are also important influences on the Rupee.
To facilitate trade, the Reserve Bank of India (RBI) intervenes actively in foreign exchange markets with the aim of keeping the exchange rate stable. It also adjusts interest rates to try to keep inflation at its 4% target. Rate increases generally support the Rupee through the ‘carry trade’: investors borrow in countries where interest rates are lower and invest the proceeds in countries offering relatively higher rates, profiting from the difference.
Inflation, interest rates, economic growth (GDP), the trade balance and foreign investment inflows all help determine the Rupee’s value. Faster growth can attract additional overseas investment and thereby increase demand for the currency, while a narrowing trade deficit will eventually strengthen it. Higher interest rates are supportive too, particularly when real rates, which are interest rates minus inflation, rise. When risk appetite improves, greater inflows of Foreign Direct and Indirect Investment (FDI and FII) can also benefit the Rupee.
When inflation rises, especially above the rates seen in India’s peers, it is usually unfavourable for the Rupee because it signals devaluation through oversupply. By making exports more expensive, inflation also results in more Rupees being sold to pay for imports, putting further pressure on the currency. However, higher inflation typically prompts the Reserve Bank of India (RBI) to increase interest rates. This can support the Rupee by drawing greater demand from international investors. Lower inflation has the reverse effect.







Phone: +61 2 8036 8388
Fax: +61 2 8036 8388
Email: support@tmgm.com



The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved


