
News & AnalysisCareer

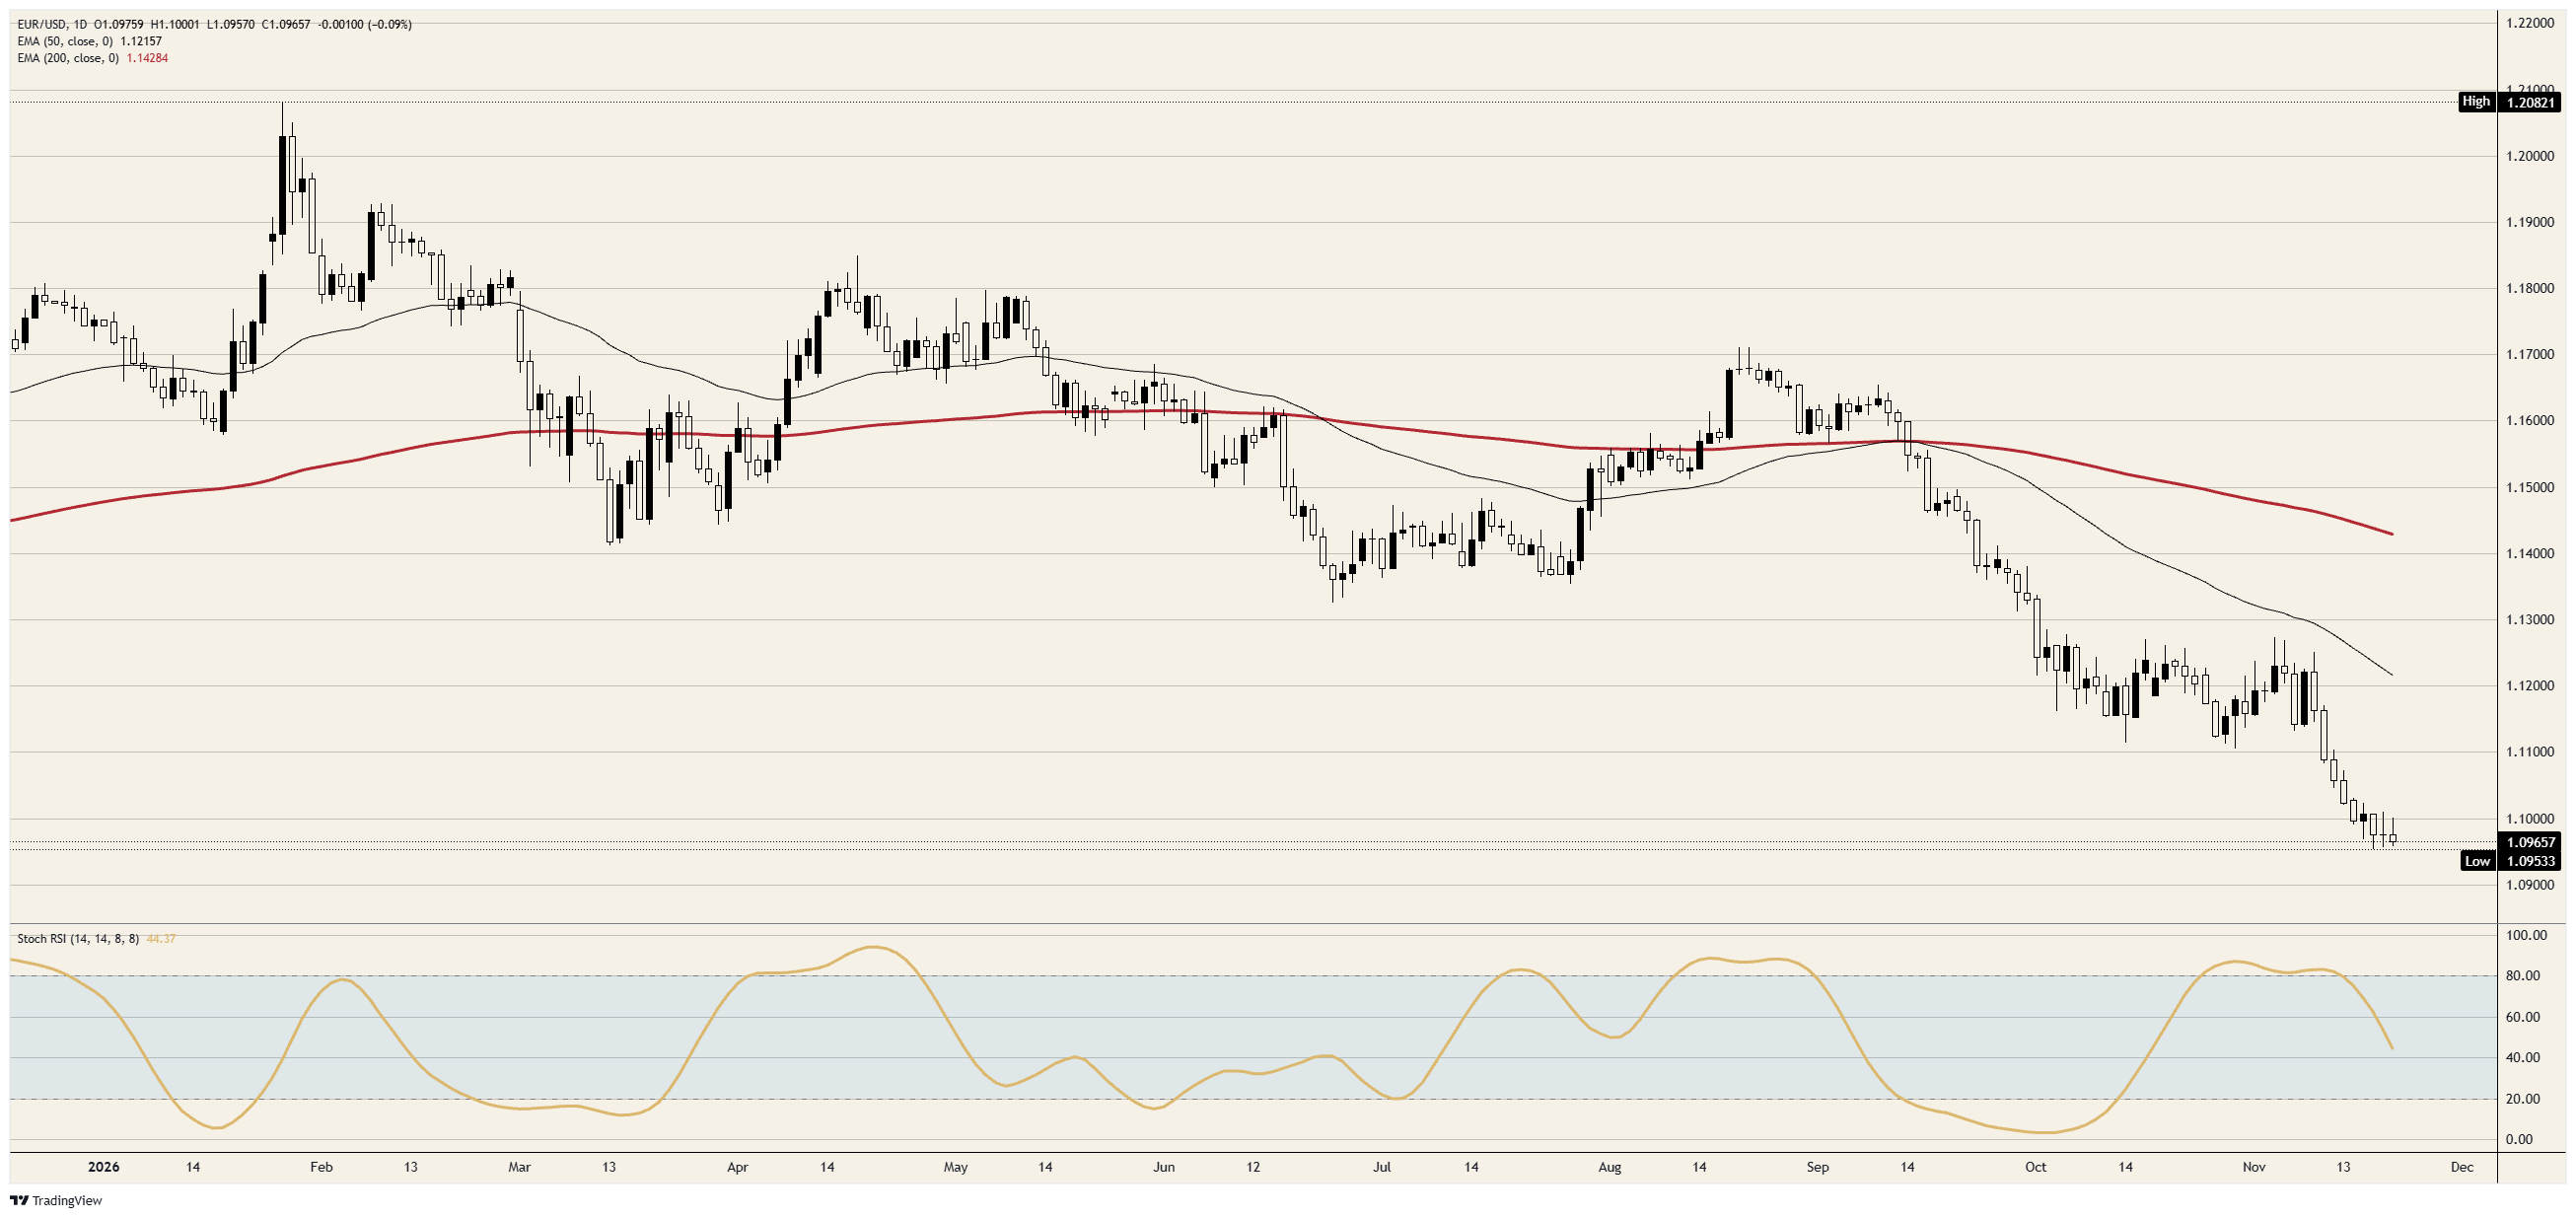
An upward revision to Eurozone core inflation, a better-than-forecast ZEW sentiment survey and weaker-than-expected US factory figures have done little for EUR/USD. Despite a week of largely favourable news for the Euro, the pair has been rebuffed at 1.1000 in each of the past three sessions. It remains just above 1.0950, its weakest level in 19 months, having made no progress since breaking below the round number on Monday.
Core inflation for October was revised to 2.6% YoY from an initial 2.5% in Eurostat's final figures on Wednesday, while the headline reading was confirmed at 4.0%. The previous day, the ZEW economic sentiment survey registered 26.5, beating the 19.1 forecast. Markets assign a probability of more than 90% to a European Central Bank (ECB) rate rise on December 17, which would lift the deposit rate to 2.75% from 2.50%.
Yet the inflation revision coincided with the pair's low for the year. With more than 90% of a rate rise already priced in, less than 10% remains to support the currency. Firmer inflation figures therefore serve to validate a decision that markets have already traded.
US releases also provided a favourable backdrop for the Euro. Both the Empire State and Philadelphia Fed manufacturing surveys delivered readings below half their forecasts. Meanwhile, October industrial production declined by 0.4% and weekly jobless claims climbed to 203K.
Support from the data was not necessary for the Dollar. Released on Wednesday, the minutes of the Fed's October meeting revealed that almost all officials anticipate additional rate rises, with a couple prepared to consider more than a quarter-point in December. Fed Governor Waller called for a half-point increase that same day. Before any further moves, the Fed's 3.75%-4.00% rate already stands at least 1.25 points above the ECB's 2.50%. October's decision to leave rates unchanged passed 10-2, with both dissenters favouring an increase. Since then, the committee has spent November discussing how rapidly to take the step it voted against.
The effects of an ECB increase are not uniform across the currency bloc. Earlier in November, the premium investors required to hold French 10-year debt rather than German debt widened to about 1.6 points, its highest since the Eurozone debt crisis. France's 2027 budget, meanwhile, remains contested in parliament. On Friday, Bank of France Governor Moulin said the country faces a budget crisis but is in a very different position from Greece. It was the second occasion since early October on which he had drawn the comparison to reject it.
Higher ECB rates increase both the return on holding Euros and the expense of refinancing French debt. That combination may explain why a heavily signalled rise has failed to establish a floor for EUR/USD. The budget dispute remains unresolved ahead of the European Union (EU) leaders' meeting on November 26 and 27.
Following October's composite reading of 51.7, the November Hamburg Commercial Bank (HCOB) Purchasing Managers Index (PMI) surveys are scheduled for Monday at 09:00 GMT. The US equivalents follow at 14:45 GMT, while ECB Chief Economist Lane is due to speak at 14:30 GMT that day.
The key release for EUR/USD arrives on Wednesday at 13:30 GMT. October core Personal Consumption Expenditures (PCE) inflation is expected to rise to 3.2% YoY from 3.1%, alongside an initial third-quarter Gross Domestic Product (GDP) estimate forecast at an annualised 3.5%. As US equities sold off on Friday, traders scaled back their December Fed bets. A core reading that meets or exceeds expectations could restore those positions and push the pair below 1.0950. A weaker result, by contrast, would give the Euro another opportunity to challenge 1.1000, supported by the Fed's preferred inflation gauge.
With US markets closed for Thanksgiving on Thursday, the ECB's account of its October 29 meeting will reach a thin market at 12:30 GMT. It will reveal how near the Governing Council came to raising rates in October, adding detail to a decision that traders have already taken on its behalf.
Resistance: Over three consecutive sessions, 1.1000 has contained gains, with every session high coming within about 10 pips of the level. A break above would bring 1.1050 into view, where trading paused on November 12 and 13 before the subsequent decline. Beyond that lies 1.1100, the October floor breached on November 11.
Support: The low set on Wednesday just above 1.0950 marks the weakest point in 19 months and has remained intact in the two sessions since. Below it, the daily chart offers no 2026 reference level, leaving the round number at 1.0900 next in line.
Bias: Below 1.1000, the outlook continues to favour short positions. Closing below 1.0950 on a daily basis would bring 1.0900 into focus first, followed by 1.0850. With the daily Stochastic Relative Strength Index (Stoch RSI) declining through the mid-40s, momentum is not sufficiently stretched to make the case for a rebound by itself. A daily close above 1.1050 would restore the pair to its former range and invalidate the short case.
Used by the 20 European Union countries within the Eurozone, the Euro ranks second only to the US Dollar among the world's most traded currencies. Its share of all foreign exchange transactions was 31% in 2022, when average daily turnover exceeded $2.2 trillion. The world's busiest currency pair is EUR/USD, with an estimated 30% of all transactions. Next come EUR/JPY at 4%, EUR/GBP at 3% and EUR/AUD at 2%.
Based in Frankfurt, Germany, the European Central Bank (ECB) serves as the Eurozone's reserve bank, setting interest rates and conducting monetary policy. Maintaining price stability is the ECB's principal mandate, whether through restraining inflation or supporting growth. Raising and lowering interest rates is its main policy instrument. Higher relative rates, or expectations that rates will rise, generally support the Euro; the reverse also applies. Monetary policy is decided by the ECB Governing Council at eight meetings each year. The decision-makers comprise the heads of the Eurozone's national central banks and six permanent members, among them ECB President Christine Lagarde.
Measured using the Harmonised Index of Consumer Prices (HICP), Eurozone inflation is a key economic indicator for the Euro. An increase above expectations, particularly beyond the ECB's 2% target, obliges the central bank to raise interest rates to bring inflation under control. Rates that are relatively high compared with those elsewhere typically support the Euro by making the region a more attractive destination for global investors' funds.
By signalling the economy's health, data releases can affect the Euro. GDP, Manufacturing and Services PMIs, employment figures and consumer sentiment surveys are among the indicators that can steer the single currency. Economic strength supports the Euro by drawing in foreign investment and potentially prompting the ECB to raise interest rates, which would strengthen the currency directly. Weak figures, conversely, are likely to weigh on the Euro. Particular attention is paid to releases from Germany, France, Italy and Spain. As the euro area's four largest economies, together they represent 75% of the Eurozone economy.
The Trade Balance is another release of importance to the Euro. Over a specified period, it records the gap between a country's export earnings and its spending on imports. Strong overseas demand for a country's exports generates additional demand for its currency as foreign buyers seek to purchase those goods, increasing its value. A positive net Trade Balance therefore supports a currency, whereas a negative balance has the opposite effect.







Phone: +61 2 8036 8388
Fax: +61 2 8036 8388
Email: support@tmgm.com



The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved

