

Trading
Explore a wide range of markets with competitive pricing, deep liquidity, and advanced trading tools.
Learn More 
Platform
Trade seamlessly with TMGM's powerful platform, built for speed, precision, and a superior trading experience.
Learn More Trading Platform
Academy
Learn the fundamentals of trading with beginner-friendly resources, including guides, webinars, and market insights.
Learn More News & Analysis
Get real-time market updates and expert analysis to stay ahead of trading opportunities
Learn More News & Analysis
About
Learn what sets TMGM apart — our global presence, regulatory strength, and commitment to innovation in trading.
Learn More Why Choose TMGM
Sponsorship
Will the BoJ deliver the expected hold on Friday after the Yen surrenders half its gain?
- A close above 157.50 sees USD/JPY recover roughly half its losses over two sessions.
- An October BoJ rate increase is not expected by any economist polled by Bloomberg.
- Wednesday's Fed statement precedes both Tokyo CPI and the BoJ policy decision.
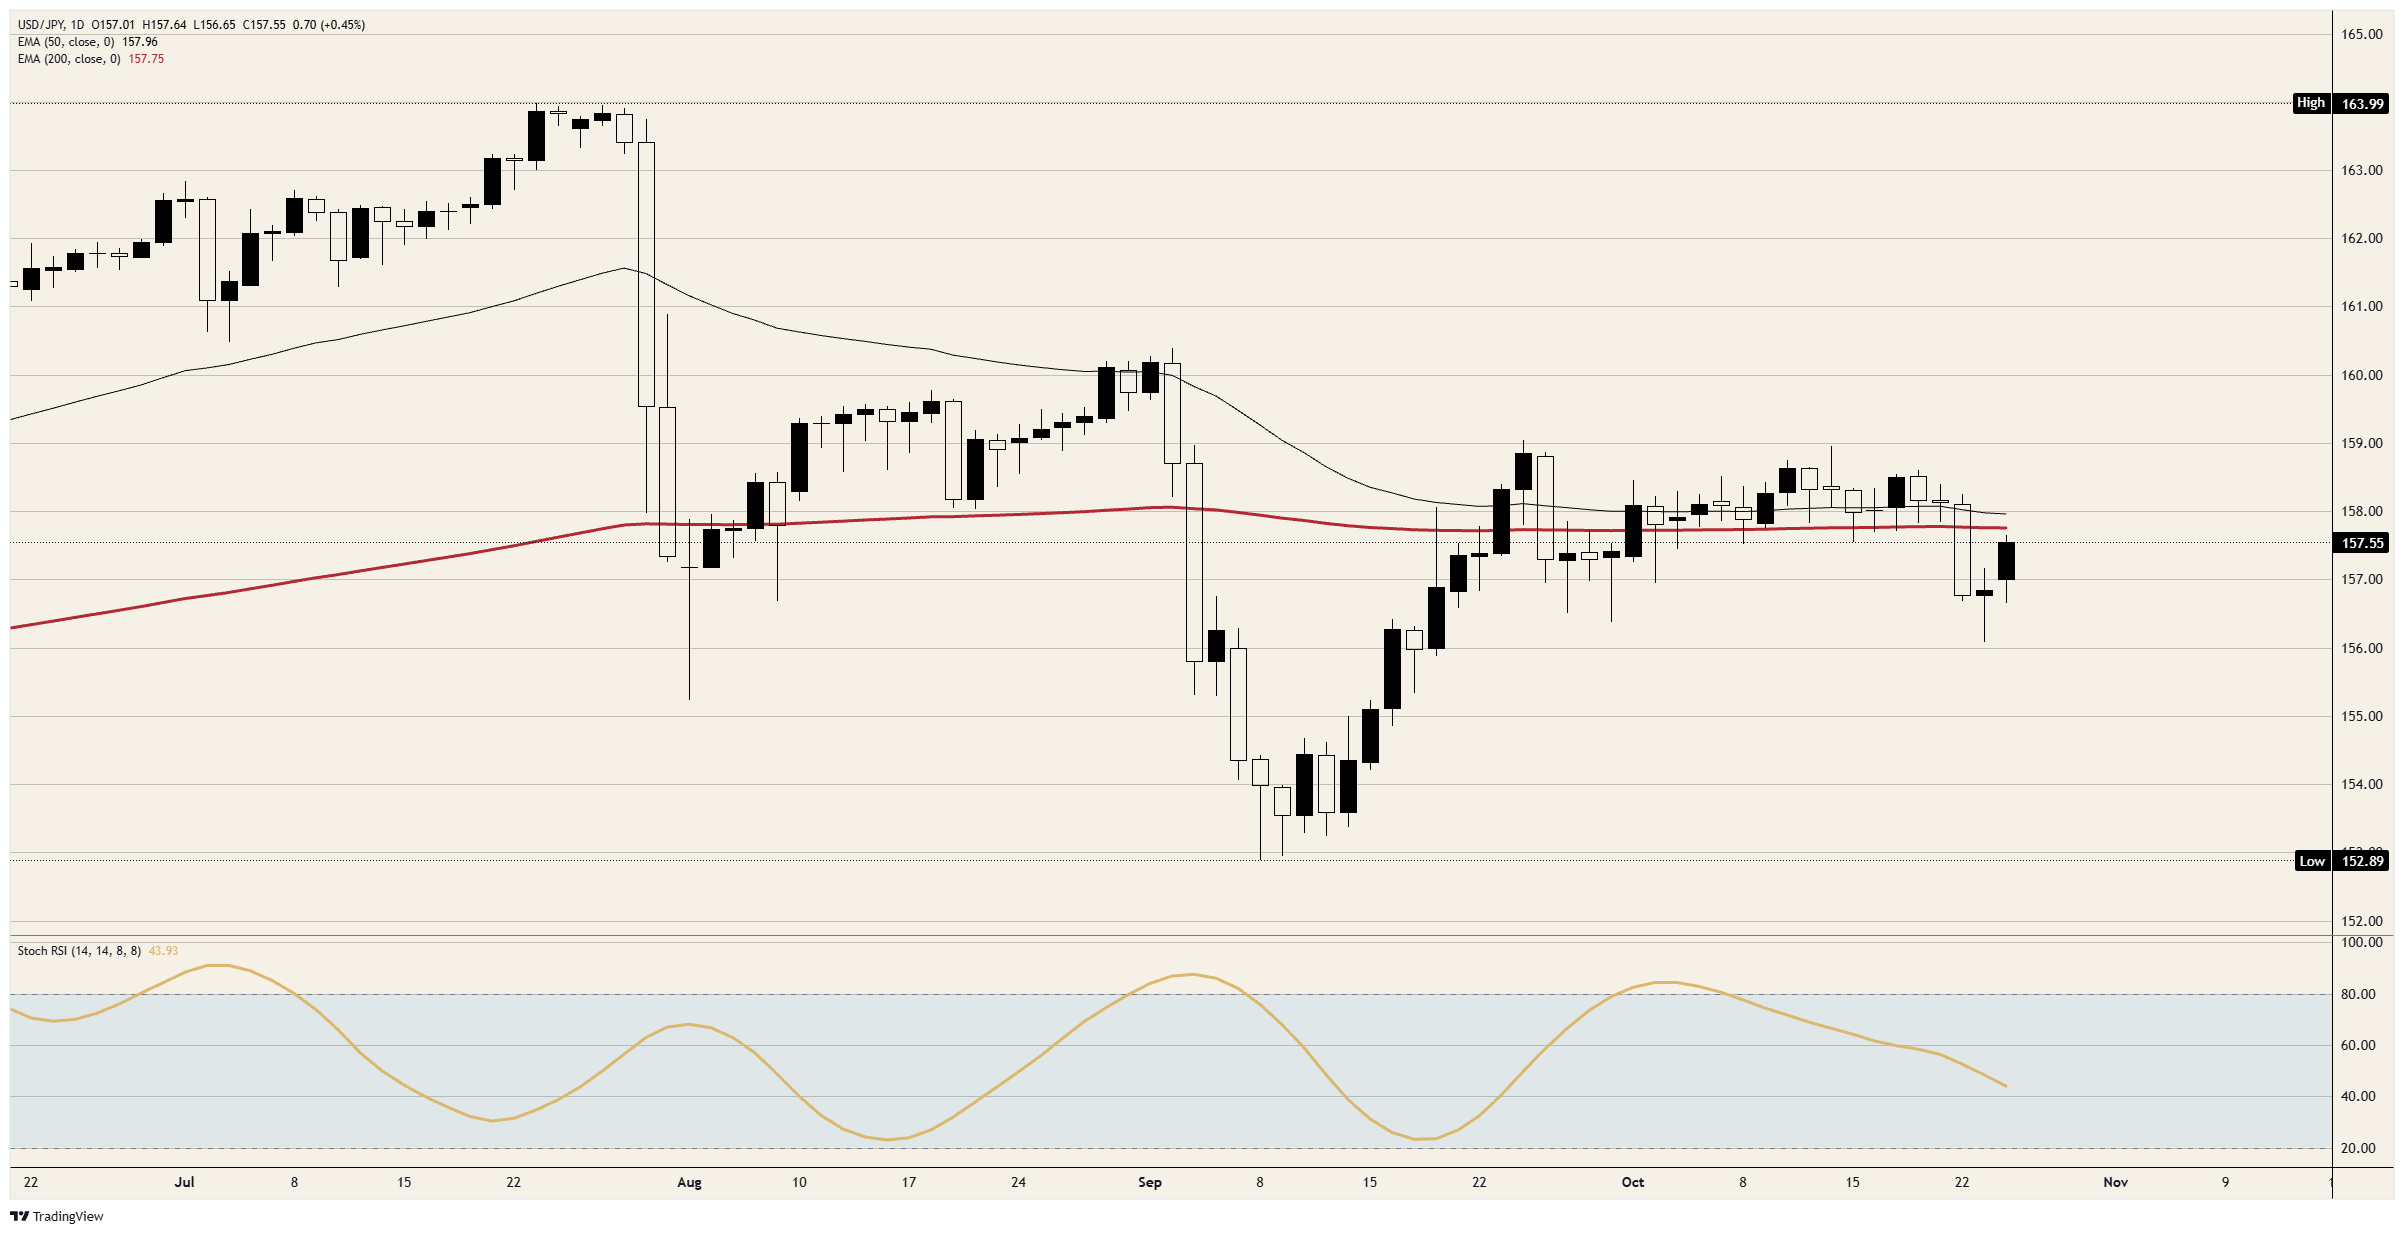
USD/JPY recovered roughly half its losses from 22 and 23 October on Monday, closing near the session high two days ahead of the Fed's decision. Earlier Yen buying in Tokyo had pushed the pair below 157.00 to its weakest level since 18 September. Monday's rebound took it from just above 156.50 to just above 157.50.
A BoJ rate increase is not expected to provide a trading catalyst for the Yen on Friday. After the Bank of Japan (BoJ) lifted its rate from 1% to 1.25% in September, BoJ Governor Ueda said consecutive hikes were unnecessary. A further increase on Friday would amount to back-to-back hikes following September's move. Of the economists surveyed by Bloomberg, none forecasts an October increase, while most anticipate one in December.
While September's 7-2 vote included two dissents opposing a rate increase, previews suggest any dissent on Friday will instead favour a hike, coming from BoJ board members Takata and Tamura. A vote supporting an increase could bring forward the December hike that Yen traders are awaiting.
Which releases could shape the next move?
The final data ahead of Friday's BoJ decision arrive at 23:30 GMT on Thursday: Tokyo's October Consumer Price Index (CPI) and Japan's September unemployment rate. At 06:30 GMT on Friday, BoJ Governor Ueda will hold his subsequent press conference. His guidance on December remains the Tokyo policy signal for USD/JPY to price in.
At 18:00 GMT Wednesday, the Fed is due to release its statement and is expected to leave its 3.75%-4.00% range unchanged. Attention then turns to US third-quarter growth and September's Personal Consumption Expenditures Price Index (PCE), both scheduled for 12:30 GMT Thursday. The two releases will inform the case for a December Fed rate increase.
What do the charts indicate?
Both the 200-day Exponential Moving Average (EMA) and the 50-day average sit just below 158.00, beyond Monday's session high. The decline on 22 October marked the first daily close under 157.00 since 18 September. Across six months, the chart's range extends from the 8 September low just below 153.00 to July's high just below 164.00.
Daily price chart: USD/JPY
Japanese Yen: frequently asked questions
Among the most actively traded currencies globally, the Japanese Yen (JPY) draws its value broadly from Japan's economic performance. More specific influences include the Bank of Japan's monetary policy, the gap between Japanese and US bond yields, and traders' appetite for risk, alongside other factors.
Currency control forms part of the Bank of Japan's mandate, making its actions an important influence on the Yen. On occasion, the BoJ has intervened directly in foreign exchange markets, usually to weaken the currency. However, political concerns among Japan's principal trading partners discourage frequent intervention. Between 2013 and 2024, the BoJ's ultra-loose monetary policy weakened the Yen against its major peers as policy increasingly diverged from that of other leading central banks. The more recent, gradual withdrawal of this ultra-loose stance has lent the Yen some support.
By maintaining ultra-loose monetary policy over the past decade, the BoJ moved further apart from other central banks, notably the US Federal Reserve. That divergence helped widen the yield gap between 10-year US and Japanese bonds, supporting the US Dollar relative to the Japanese Yen. The gap is now narrowing as the BoJ's 2024 decision to phase out ultra-loose policy combines with interest-rate cuts by other major central banks.
Investors often regard the Japanese Yen as a safe-haven asset, making them more inclined to move money into the currency during periods of market stress because of its perceived stability and reliability. As a result, market turbulence is likely to lift the Yen against currencies considered riskier investments.
POPULAR ARTICLES
1Middle East talks ease supply concerns, pushing WTI down to around $1002Can Bitcoin hold $77,000 support ahead of the Fed decision?3Iran says it and Mecca pact states agree to pursue peace4Ethereum Price Forecast: ETH drops below $2,355 as BitMine maintains buying spree5Will Canada change its stance in US trade talks? Carney says no6Gold climbs back above $4,000 as hopes rise for easing US‑Iran tensions7Will the BoJ deliver the expected hold on Friday after the Yen surrenders half its gain?8Aussie Dollar’s 0.70 rally falters as Fed, RBA inflation tests loom9Third consecutive RBNZ hike priced in by New Zealand Dollar traders
LIVE QUOTES


ALL ABOUT FOREX
What Is a Stop Loss, How Does It Work and How Do You Set One?
Margin Call Meaning: What It Is, What Triggers It, and How to Avoid One
What Is an Islamic Account in Forex?
Best Indicators for Forex Trading and How to Use Them
The Top 10 Most Traded Currency Pairs in the World
What are the Major Forex Pairs? 7 Major Currency Pairs in the World
5 Best Forex Trading Apps In India In 2026
Top 15 Weakest Currencies in the World
Best Time to Trade Forex
Get Started!
Sign up and access the Global Markets in less than 3 minutes

Connect With Us









Contacts
Phone: +61 2 8036 8388
Fax: +61 2 8036 8388
Email: support@tmgm.com



The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved