

Trading
Explore a wide range of markets with competitive pricing, deep liquidity, and advanced trading tools.
Learn More 
Platform
Trade seamlessly with TMGM's powerful platform, built for speed, precision, and a superior trading experience.
Learn More Trading Platform
Academy
Learn the fundamentals of trading with beginner-friendly resources, including guides, webinars, and market insights.
Learn More News & Analysis
Get real-time market updates and expert analysis to stay ahead of trading opportunities
Learn More News & Analysis
About
Learn what sets TMGM apart — our global presence, regulatory strength, and commitment to innovation in trading.
Learn More Why Choose TMGM
Sponsorship
British Pound slides further ahead of Fed decision and UK budget, extending 4-day decline
- Selling pressure keeps GBP/USD on a four-day losing streak, with the pair down 0.14% at 1.3321.
- A rise to 91.7 marks a sharp improvement in US Consumer Confidence, alongside a 1.6% increase in Durable Goods.
- Wednesday brings two key events into focus: the Fed decision and the UK Autumn Budget.
Sterling remains under pressure against the US Dollar for a fourth consecutive day, losing 0.14% as the Greenback posts modest gains before Wednesday’s Federal Reserve monetary policy decision. On Tuesday, GBP/USD is trading at 1.3321, confined to a 1.3307-1.3349 range.
Can GBP/USD hold near 1.3300 as firm US data underpins the Dollar before key policy decisions?
Despite continuing hostilities in the Middle East, sentiment across markets remains upbeat. Reports indicated that debris was falling over Riyadh in Saudi Arabia, causing damage, according to SPA. Iran’s supreme leader Mojtaba Khamenei, meanwhile, restated the country’s terms for ending the war with the US. Before peace talks can take place, Tehran wants the US naval blockade lifted and sanctions removed.
Housing figures on the US economic calendar showed a sharp slowdown in New Home Sales: September recorded -0.6% MoM, compared with 6.4% in August.
Greater household optimism about employment prospects and business conditions drove an unexpected improvement in Consumer Sentiment, the Conference Board (CB) reported. The reading climbed to 91.7 in October from 84.2. Within the survey, 12-month inflation expectations held at 5.8%, still substantially above the Fed’s target.
Robust business investment during the expansion of AI infrastructure accompanied a September jump of 1.6% in Durable Goods Orders, against the previous 0.1% rise. An earlier release pointed to a modest cooling in the labour market: the ADP Employment Change 4-week average eased to 16.8K from 18.5K.
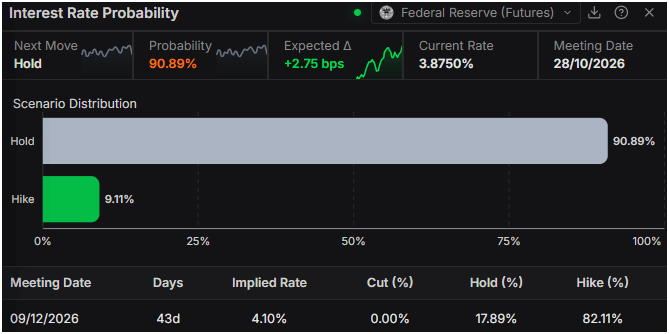
Money markets, meanwhile, point to unchanged Fed rates on Wednesday, while assigning a 19% probability to a hike. According to Prime Terminal, the odds for December have continued to decline, reaching 82% from around 90% last week.
Sterling’s performance in the UK is mixed: it is gaining against the Euro, which faces pressure from France’s fiscal problems, but losing ground to the Greenback.
Attention now turns to the UK Autumn Budget. Chancellor Healey is expected to deliver a sustainable fiscal plan that avoids unsettling the bond market while honouring some of Andy Burnham’s government’s promises. The Financial Times reports that John Healey is set to announce a 4% increase for low-wage workers.
Looking ahead, traders are preparing for Wednesday’s Fed meeting, while the UK budget is the main event on the domestic economic calendar.
GBP/USD Price Forecast: What does the technical outlook indicate?
A bearish short-term bias persists on the daily chart, where GBP/USD is trading at 1.3314 beneath the latest simple moving average cluster near 1.3396. A falling resistance trend line also lies close to that area. Although the pair has moved away from the former trend-line resistance that became support at 1.3257, it remains only slightly above this level. That positioning suggests sellers retain control of the broader structure. Meanwhile, a 14-period Relative Strength Index reading of around 48 points to momentum easing towards neutral, rather than signalling a forceful recovery.
The first resistance zone on the upside lies around 1.3396, the meeting point of the 50-, 100- and 200-day simple moving averages. Beyond it, rising trend supports that have become resistance create further hurdles near 1.3644 and 1.3823. Initial meaningful support on the downside is at the broken trend-line level near 1.3257. A daily close beneath that floor would likely pave the way for a steeper decline, extending the pair’s retreat from the dense resistance zone above.
(The technical analysis of this story was written with the help of an AI tool. Learn more.)
Pound Sterling: Frequently asked questions
As the United Kingdom’s official currency, the Pound Sterling (GBP) is also the world’s oldest currency, dating to 886 AD. Figures for 2022 place it fourth among the most traded currencies in the foreign exchange (FX) market, with a 12% share of all transactions and average daily turnover of $630 billion. Among its principal pairs, GBP/USD, known as ‘Cable’, represents 11% of FX trading. GBP/JPY, which traders call the ‘Dragon’, accounts for 3%, while EUR/GBP accounts for 2%. Responsibility for issuing the Pound Sterling rests with the Bank of England (BoE).
Monetary policy set by the Bank of England has the greatest influence on the Pound Sterling’s value. In making its decisions, the BoE assesses whether it has met its central objective of “price stability” – inflation holding steady at around 2%. Adjusting interest rates is its main means of pursuing that goal. If inflation runs too high, the BoE seeks to curb it through higher interest rates, increasing borrowing costs for households and businesses. GBP generally benefits because higher rates make the UK a more appealing destination for international investors’ funds. Conversely, excessively low inflation signals slowing economic growth. The BoE would then consider cutting interest rates to reduce the cost of credit, encouraging businesses to borrow and invest in projects that support growth.
By revealing the economy’s condition, data releases can affect the Pound Sterling’s value. GDP, Manufacturing and Services PMIs, and employment figures are among the indicators that can shape GBP’s direction. Economic strength supports Sterling by drawing in foreign investment and potentially prompting the BoE to raise interest rates, which directly strengthens GBP. Weak economic readings, by contrast, are likely to weigh on the Pound Sterling.
The Trade Balance is another important release for the Pound Sterling. Over a specified period, it compares a country’s export earnings with its expenditure on imports. Strong overseas demand for a country’s exports supports its currency through the additional demand from foreign buyers purchasing those goods. A positive net Trade Balance therefore strengthens the currency, while a negative balance has the opposite effect.
POPULAR ARTICLES
1Euro: Will key support at 1.1113 hold against US Dollar? – Scotiabank2Silver Price Forecast: Can XAG/USD Sustain Its Rebound From Year-to-Date Lows Ahead of the Fed Rate Decision?3British Pound slides further ahead of Fed decision and UK budget, extending 4-day decline4Dogecoin Price Forecast: Is a potential bottom in sight for DOGE bulls as retail interest holds steady?5Euro stays under pressure as Fed and ECB interest rate decisions draw near6Natural gas: Will persistent winter risk keep prices elevated? – Commerzbank7United Kingdom: How could Budget risks affect fiscal headroom and rates? - ING8Canadian Dollar: Is Consolidation Around 1.40 Holding? – Scotiabank9US CB Consumer Confidence Index: October Reading Rises to 91.7
LIVE QUOTES


ALL ABOUT FOREX
What Is a Stop Loss, How Does It Work and How Do You Set One?
Margin Call Meaning: What It Is, What Triggers It, and How to Avoid One
What Is an Islamic Account in Forex?
Best Indicators for Forex Trading and How to Use Them
The Top 10 Most Traded Currency Pairs in the World
What are the Major Forex Pairs? 7 Major Currency Pairs in the World
5 Best Forex Trading Apps In India In 2026
Top 15 Weakest Currencies in the World
Best Time to Trade Forex
Get Started!
Sign up and access the Global Markets in less than 3 minutes

Connect With Us









Contacts
Phone: +61 2 8036 8388
Fax: +61 2 8036 8388
Email: support@tmgm.com



The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved