

Trading
Explore a wide range of markets with competitive pricing, deep liquidity, and advanced trading tools.
Learn More 
Platform
Trade seamlessly with TMGM's powerful platform, built for speed, precision, and a superior trading experience.
Learn More Trading Platform
Academy
Learn the fundamentals of trading with beginner-friendly resources, including guides, webinars, and market insights.
Learn More News & Analysis
Get real-time market updates and expert analysis to stay ahead of trading opportunities
Learn More News & Analysis
About
Learn what sets TMGM apart — our global presence, regulatory strength, and commitment to innovation in trading.
Learn More Why Choose TMGM
Sponsorship
Why is the Dollar Index retreating from a 19-month high after a surge in retail sales?
- Why did DXY surrender its retail sales rally to a 19-month high?
- Yields retreated on weak factory figures, with a December Fed rate hike already fully priced in.
- Rate-hike expectations next face Wednesday's release of the Fed's October meeting minutes.
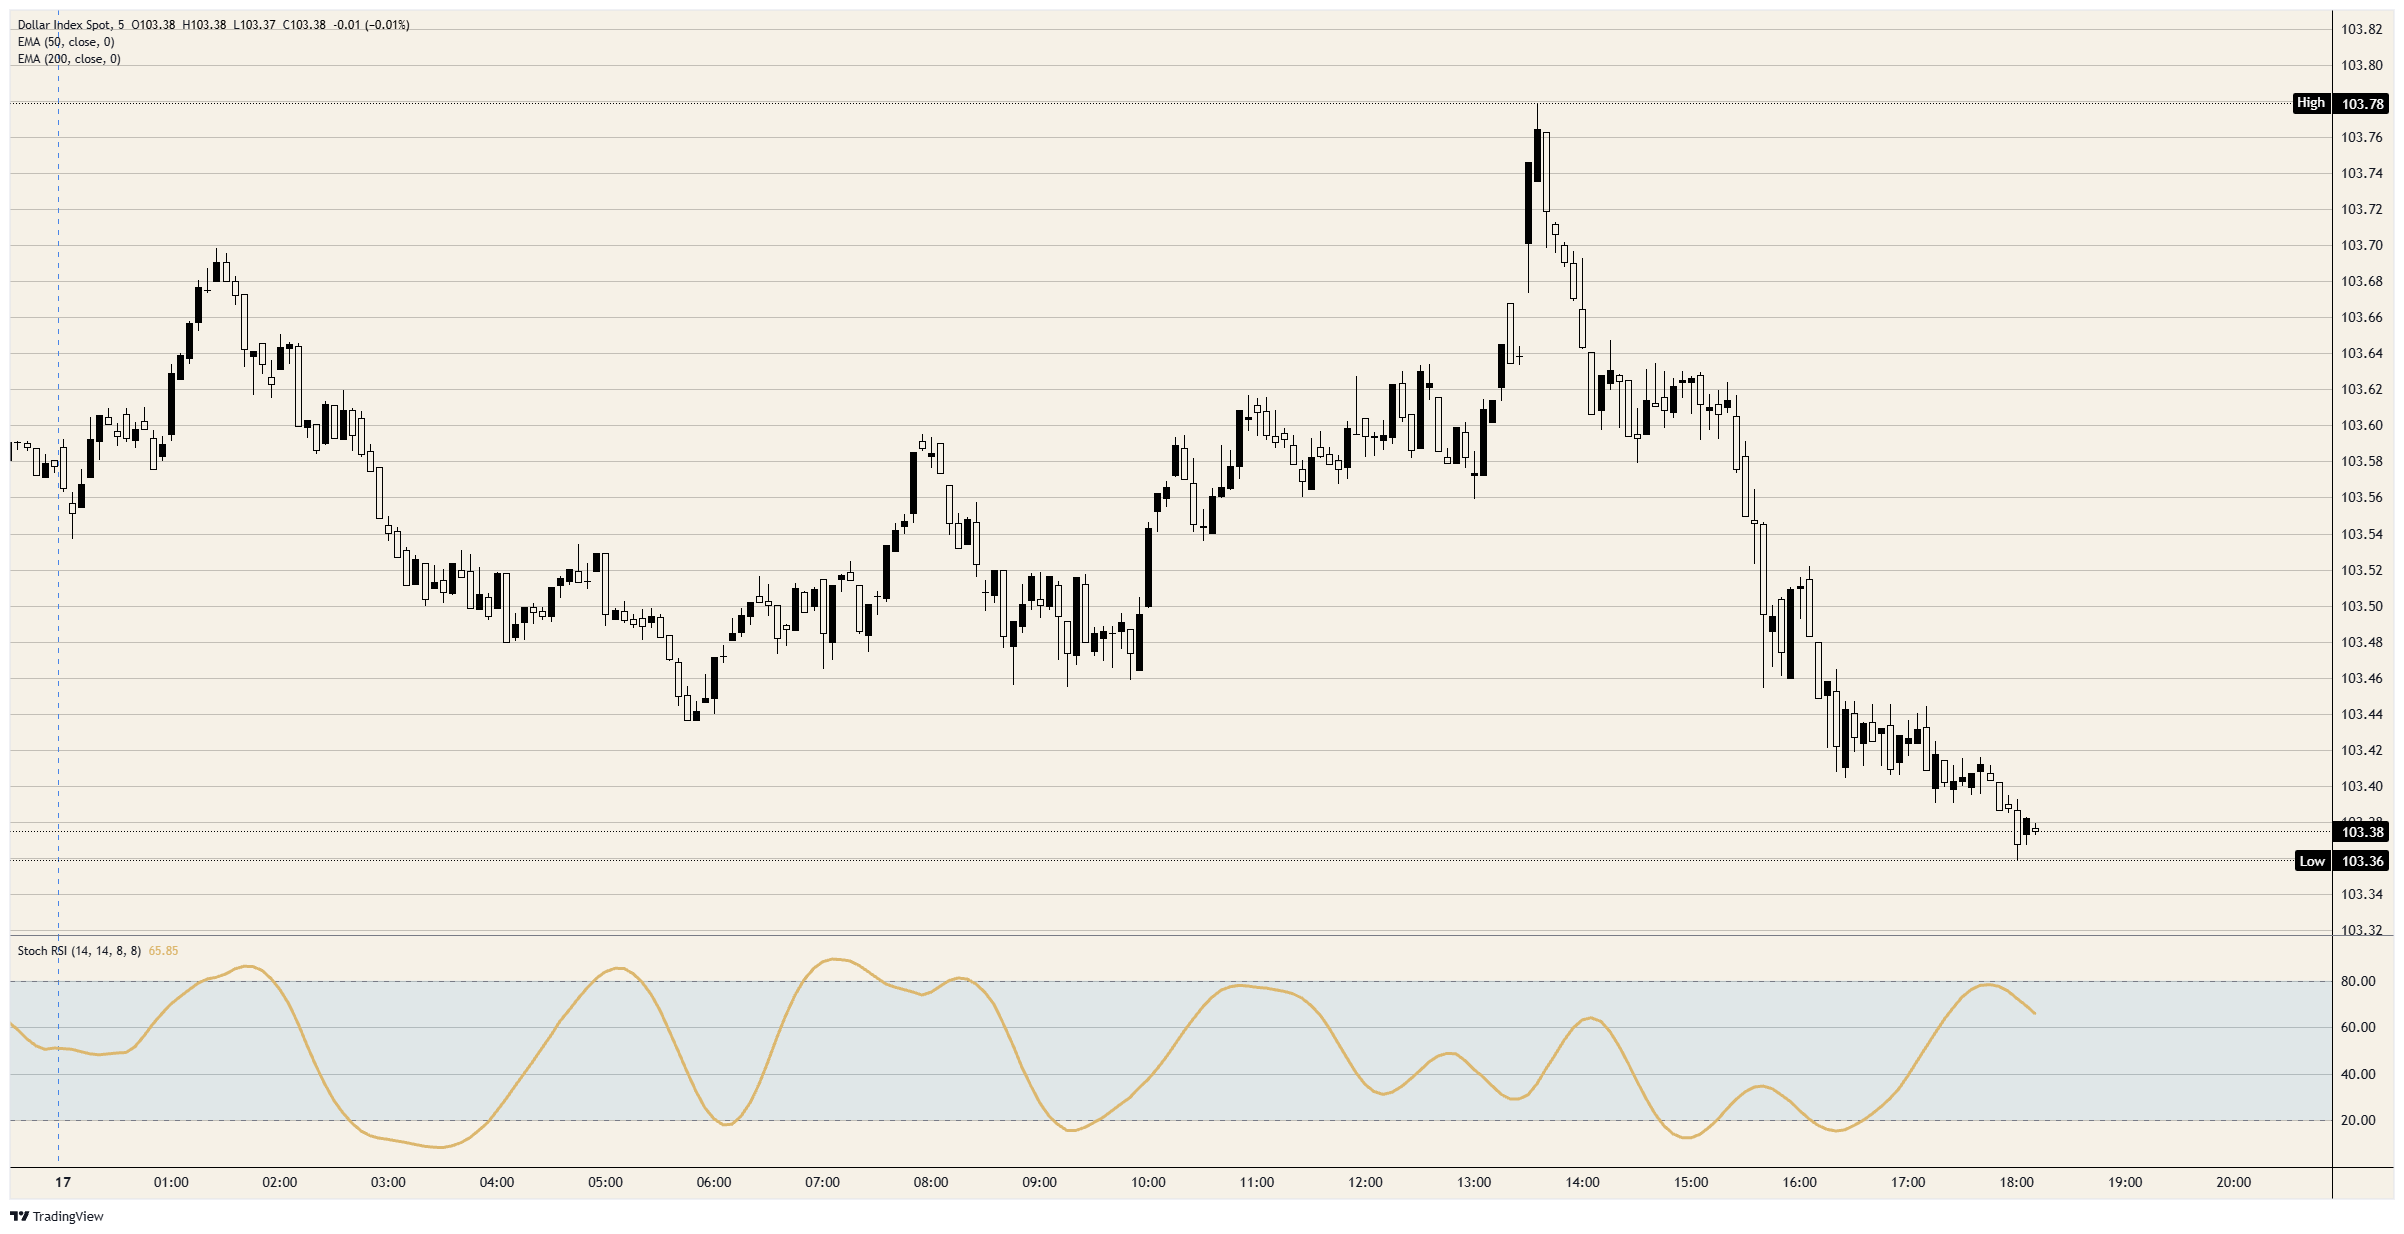
The Dollar Index looks set to end a five-session winning run after surrendering a fresh 19-month high before the next data release. October retail sales initially lifted it to just below 103.80, a level last seen in April 2025. That entire jump had reversed before industrial production figures arrived, and a further decline has since left the index around 103.40.
With traders already fully pricing in a December Fed rate increase, stronger figures offered limited scope for further Dollar gains. CME FedWatch put the probability of a quarter-point rise near 91%. October retail sales increased 0.2%, while the control group advanced 0.6% and its September increase was revised upwards to 0.5%. Import prices, meanwhile, climbed 1.1% for the second consecutive month.
Treasury yields erased their gains for the session, leaving the 10-year near 5.13%, as October industrial production contracted 0.4% following a 0.7% increase and the homebuilder sentiment index slipped from 29 to 25. The homebuilder reading triggered the Dollar's second leg lower. That decline persisted after Cleveland Fed President Hammack said inflation was heading in the wrong direction.
What could shift rate-hike expectations next?
Wednesday brings the minutes of the Fed's October 27-28 meeting at 19:00 GMT. At that meeting, the central bank left its rate unchanged at 3.75%-4.00%. New York Fed President Williams is also scheduled to speak on Wednesday, followed on Thursday by Cleveland Fed President Hammack, Chicago Fed President Goolsbee and Philadelphia Fed President Paulson. A December 9 increase is already fully priced in, leaving the probability of a half-point hike, near 9% on CME FedWatch, open to repricing on their remarks.
Tuesday's schedule includes Nvidia (NVDA) results at 21:20 GMT, while weekly jobless claims are due on Thursday at 13:30 GMT. According to analysts at ING, losses in US technology shares have reached enough other equity markets to support safe-haven demand for the Dollar.
Where does the pullback leave DXY technically?
Back within Monday's trading range, the index has surrendered less than a fifth of its advance from the November 10 low near 101.50. It remains above the October 14 high just below 103.00, a level it broke through on November 12. Its 50-day Exponential Moving Average (EMA) stands near 101.70, compared with around 100.40 for the 200-day EMA.
DXY chart: 5-minute timeframe
US Dollar: frequently asked questions
As the official currency of the United States of America, the US Dollar (USD) also circulates alongside domestic banknotes in a significant number of other countries, serving as their ‘de facto’ currency. No other currency is traded more widely: data from 2022 show that it accounts for over 88% of global foreign exchange turnover, equivalent to average daily transactions of $6.6 trillion. After the Second World War, the USD replaced the British Pound as the global reserve currency. Gold backed the US Dollar for most of its history, until the Gold Standard ended with the Bretton Woods Agreement in 1971.
Monetary policy set by the Federal Reserve (Fed) is the single biggest influence on the US Dollar's value. Adjusting interest rates is the Fed's main means of pursuing its two mandates: maintaining price stability by controlling inflation and promoting full employment. The Fed raises rates when prices climb too rapidly and inflation exceeds its 2% target, supporting the USD. Conversely, inflation below 2% or an excessively high unemployment rate may prompt the Fed to cut interest rates, putting pressure on the Greenback.
When conditions become extreme, the Federal Reserve can print additional Dollars and introduce quantitative easing (QE). Through QE, the Fed sharply expands the supply of credit in a financial system that has become blocked. This unconventional policy is used when credit dries up as banks refuse to lend to one another for fear of counterparty default. It serves as a last resort if interest rate cuts alone are unlikely to deliver the required outcome. During the Great Financial Crisis in 2008, QE was the Fed's preferred response to the credit crunch. The process entails printing additional Dollars to purchase US government bonds, mainly from financial institutions. The US Dollar typically weakens as a result of QE.
In the reverse process, known as quantitative tightening (QT), the Federal Reserve halts bond purchases from financial institutions and allows its existing bonds to mature without reinvesting the principal in further purchases. This generally supports the US Dollar.
POPULAR ARTICLES
1AUD/JPY Price Forecast: Softens to near 107.00, negative outlook prevails under 100-day SMA2Pi Network Price Forecast: How are major Pi Ecosystem Summit updates fuelling PI’s rebound?3Silver Price Forecast: Hawkish Fed outlook drives XAG/USD down to 13-month lows4Can the United States Dollar Index Rally Past 103.80 as FOMC Minutes Come Into Focus?5Is UK CPI set to show a 13-month inflation high as fuel costs climb?6Top 3 Price Prediction: Bitcoin, Ethereum, Ripple – ETH and XRP Struggle for Traction as BTC Consolidates7Australian Dollar Falls Below 0.6750 Under Hawkish Fed Pressure; Focus Turns to FOMC Minutes8Breaking: Gold sinks to lowest since September 2025 as hawkish Fed and strong USD push prices below $3,8009Can the New Zealand Dollar recover near 0.5500 as a dovish RBNZ and firm USD restrain gains?


Get Started!
Sign up and access the Global Markets in less than 3 minutes

Connect With Us









Contacts
Phone: +61 2 8036 8388
Fax: +61 2 8036 8388
Email: support@tmgm.com



The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved