

Trading
Explore a wide range of markets with competitive pricing, deep liquidity, and advanced trading tools.
Learn More 
Platform
Trade seamlessly with TMGM's powerful platform, built for speed, precision, and a superior trading experience.
Learn More Trading Platform
Academy
Learn the fundamentals of trading with beginner-friendly resources, including guides, webinars, and market insights.
Learn More News & Analysis
Get real-time market updates and expert analysis to stay ahead of trading opportunities
Learn More News & Analysis
About
Learn what sets TMGM apart — our global presence, regulatory strength, and commitment to innovation in trading.
Learn More Why Choose TMGM
Sponsorship
Can the United States Dollar Index Rally Past 103.80 as FOMC Minutes Come Into Focus?
- Early gains fade for the US Dollar Index, leaving it broadly unchanged near 103.60.
- After reporting robust Q3 earnings, Nvidia says business continues as usual despite Jensen Huang's departure.
- Minutes from the October FOMC policy meeting remain firmly in investors' focus.
Early buying interest in the US Dollar (USD) fades on Wednesday, with the currency surrendering modest opening gains to trade broadly unchanged. At the time of writing, the US Dollar Index (DXY) stands near 103.60, showing little movement. The index measures the Greenback against a basket of six major currencies.
Attempts to push the USD Index above 103.80 have met with selling pressure since the previous day, indicating that the rally has encountered resistance.
Weighing slightly on the US Dollar's safe-haven appeal, Nvidia's strong quarterly earnings following the ouster of CEO Jensen Huang have made it harder for the USD Index to build on its gains. Revenue from data centres, which account for a substantial share of Nvidia's business, doubled to $107 billion in the quarter ending September, the company reported.
Addressing Nvidia's business outlook following CEO Huang's resignation, interim CEO Colette Kress told analysts on a call that “business is usual”, according to the BBC. She added, "Our momentum is real. Our demand is accelerating. Our supply is growing. Our customers and our partners are with us, and employees are committed,"
Part of the US Dollar's recent rally reflected growing concerns over demand for Artificial Intelligence (AI) infrastructure after the Democrats' victory in the United States (US) midterm elections and Jensen Huang's departure.
Ahead of Nvidia's results, ING analysts observed that “the sell-off has spilled over sufficiently into broader US and global equities for the Dollar to benefit from its safe-haven role”.
Attention on monetary policy now turns to the minutes of the October Federal Open Market Committee (FOMC) meeting, due later in the day. At that meeting, the Fed kept interest rates unchanged in the 3.75%-4.00% range, describing the decision as a pause rather than the conclusion of its monetary tightening cycle.
US Dollar Index Technical Analysis: Can the Bullish Bias Hold?
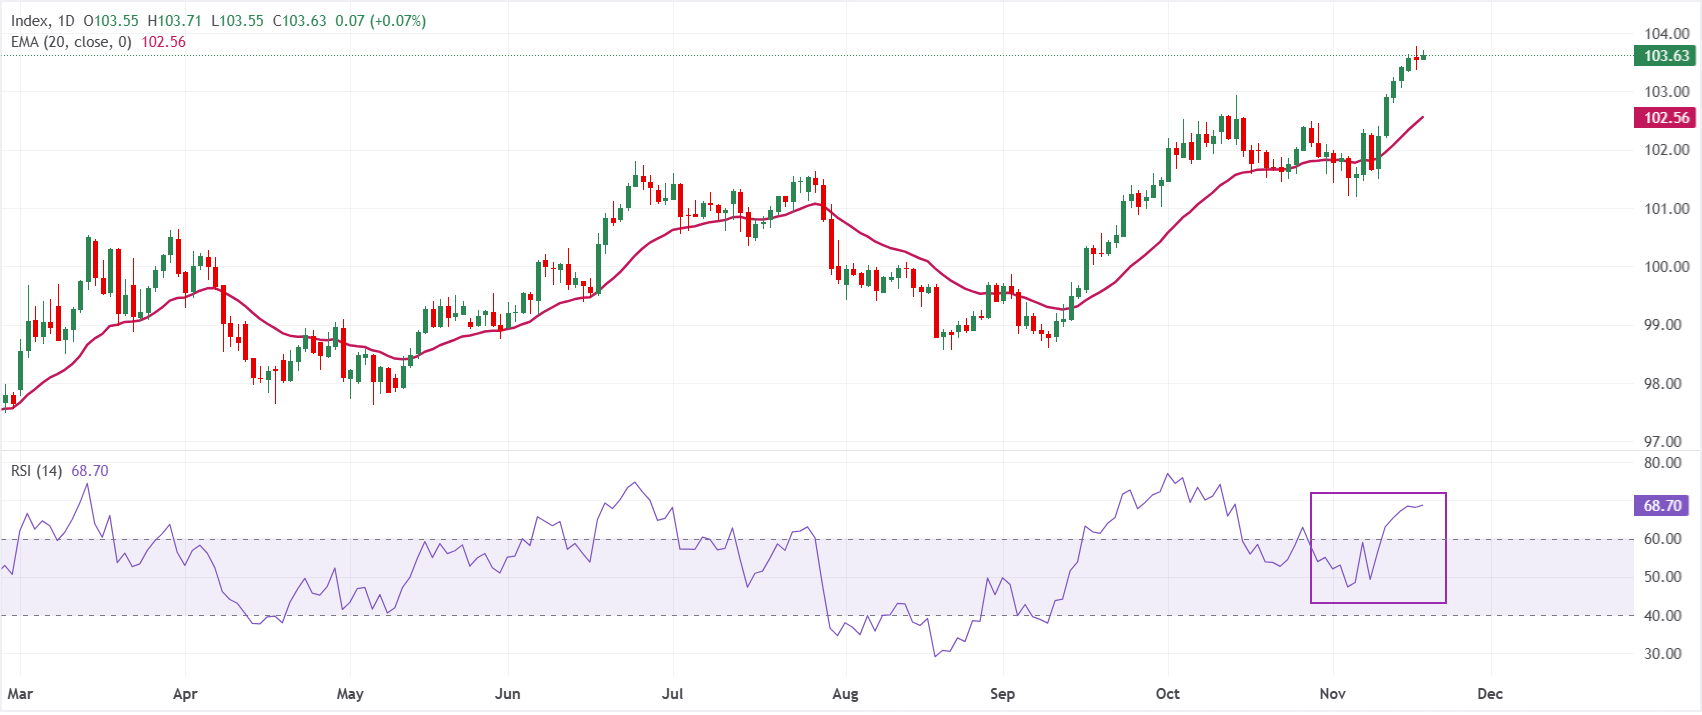
A near-term bullish bias remains intact on the daily chart, with Dollar Index Spot at 103.63, comfortably above its 20-day exponential moving average (EMA) of 102.56. The upward-sloping short-term EMA continues to support price action. Meanwhile, the Relative Strength Index (RSI), at 68.70, sits just short of overbought territory. This points to strong but stretched upward momentum that could temper the rally rather than trigger an immediate reversal.
The first support on a decline lies near 102.56 at the 20-day EMA. As long as that level holds, a pullback would be expected to draw buyers looking to enter on dips. Closing below this dynamic support on a daily basis would signal the possibility of a deeper correction. However, holding above 102.56 would keep the technical structure supportive of further gains following any consolidation.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
US Dollar: Frequently Asked Questions
As the official currency of the United States of America, the US Dollar (USD) also serves as the ‘de facto’ currency in a significant number of other countries, circulating alongside their local banknotes. No other currency is traded more widely. According to 2022 data, it accounts for over 88% of worldwide foreign exchange turnover, equivalent to average daily transactions of $6.6 trillion. The USD replaced the British Pound as the world's reserve currency after the Second World War. Gold backed the US Dollar for much of its history, until the Gold Standard ended with the Bretton Woods Agreement in 1971.
Monetary policy set by the Federal Reserve (Fed) is the single biggest influence on the US Dollar's value. The Fed pursues two objectives: maintaining price stability by controlling inflation and promoting full employment. Adjustments to interest rates are its main means of meeting these goals. If prices climb too rapidly and inflation exceeds the Fed's 2% target, the central bank will increase rates, supporting the USD. Conversely, inflation below 2% or an excessively high Unemployment Rate may prompt the Fed to cut rates, putting pressure on the Greenback.
When conditions become extreme, the Federal Reserve can print additional Dollars and introduce quantitative easing (QE). Through QE, the Fed substantially expands the supply of credit to a financial system that has become blocked. This unconventional policy is deployed when credit dries up because banks, fearing counterparty default, refuse to lend to one another. It serves as a last resort when interest rate cuts alone are unlikely to deliver the required outcome. During the Great Financial Crisis in 2008, the Fed chose QE to tackle the credit crunch. The process entails creating more Dollars to purchase US government bonds, primarily from financial institutions. The US Dollar typically weakens as a result of QE.
The opposite approach is quantitative tightening (QT). Under QT, the Federal Reserve ceases bond purchases from financial institutions and, as its existing bonds mature, does not reinvest the principal in fresh purchases. This process generally supports the US Dollar.
POPULAR ARTICLES
1United Kingdom: Inflation to peak at 4.5% in Q1 2027 - Societe Generale2US Dollar: Is Upside Pressure Building on Fed Tightening Expectations? – ING3Why has the New Zealand Dollar hit pandemic-era lows as Fed and RBNZ policies diverge?4Are lingering intervention risks supporting the Japanese Yen near 160.00?5Why is the pound hitting a five-week low amid a UK CPI miss and Fed hike expectations?6British Pound: Does the BoE path reinforce downside risks? – BBH7Why is the euro struggling as expectations of prolonged Fed tightening rise?8Bitcoin vs Gold Forecast: Why Are BTC and XAU Extending Losses Ahead of Fed Minutes?9Will Fed Minutes shed further light on the central bank’s pace of rate hikes?


Get Started!
Sign up and access the Global Markets in less than 3 minutes

Connect With Us









Contacts
Phone: +61 2 8036 8388
Fax: +61 2 8036 8388
Email: support@tmgm.com



The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved