

Trading
Explore a wide range of markets with competitive pricing, deep liquidity, and advanced trading tools.
Learn More 
Platform
Trade seamlessly with TMGM's powerful platform, built for speed, precision, and a superior trading experience.
Learn More Trading Platform
Academy
Learn the fundamentals of trading with beginner-friendly resources, including guides, webinars, and market insights.
Learn More News & Analysis
Get real-time market updates and expert analysis to stay ahead of trading opportunities
Learn More News & Analysis
About
Learn what sets TMGM apart — our global presence, regulatory strength, and commitment to innovation in trading.
Learn More Why Choose TMGM
Sponsorship
AI slowdown fears drive global sector rotation as Indian Rupee falls to fresh six-month low
- Gains in the Indian Rupee against the US Dollar extend as several supportive factors converge.
- The INR has drawn support from softer oil prices and global sector rotation driven by concerns over slowing AI spending.
- Over the last four trading days, FIIs have invested Rs. 32,210.20 crore in Indian equities.
Further gains in the Indian Rupee (INR) against the US Dollar (USD) on Friday have pushed USD/INR to a fresh low for nearly six months, around 94.08 at the time of writing.
Lower oil prices, alongside steady foreign fund inflows into Indian equities, have helped the domestic currency outperform.
Despite recovering from a fresh low for almost two months at Rs. 8,191, oil prices remain almost 13.5% below their multi-month peak of Rs. 9,972. At the time of writing, the MCX Crude Oil contract expiring on November 19 is trading near Rs. 8,670, up 1.36%.
When oil prices are low, currencies of economies heavily reliant on imported oil for their energy requirements, including India, generally outperform.
What is driving the sharp rise in FII inflows into India?
Concerns about dwindling foreign exchange (forex) reserves have eased as overseas capital has continued to flow strongly into Indian equities over the past few weeks.
Foreign Institutional Investors (FIIs) have invested Rs. 32,210.20 crore so far in November.
Global sector rotation has prompted a marked pick-up in FII buying after the Democrats’ victory in the United States (US) midterm elections fuelled concerns about slower spending on Artificial Intelligence (AI). A sharp correction in oil prices and robust Q2 corporate earnings from India Inc have provided additional impetus.
Whether this FII buying momentum can last, however, will depend largely on developments outside India, market experts caution. The New Indian Express quoted Akash Garg at Choice Wealth as saying: “Much of the capital that left chased the US-led AI and semiconductor trade; some returns only if that trade cools. For flows to turn durable, the rupee must stabilise, crude must stay soft, clarity must emerge on a US–India trade deal, and — above all — Indian corporate earnings must deliver upgrades. For now, this is welcome stabilisation, not yet a trend,"
How could US NFP data shape the Dollar’s outlook?
With the US Dollar’s outlook expected to be significantly influenced by the employment figures, investors are closely watching October’s US Nonfarm Payrolls (NFP) release, due at 12:30 GMT.
The US Dollar Index (DXY) is trading around 101.77, up 0.2%, before the US NFP release. The index tracks the Greenback against six major currencies.
Only modest job growth is likely in October’s US employment report, according to TD Securities, whose economists expect nonfarm payrolls to “remain subdued at 40K after job gains moderated to 29K in September.” Underlying momentum may nevertheless be stronger than the headline number suggests, with the economists noting that “despite the subdued, below-consensus print, our forecast would be within the range of breakeven job gains and result in an increase in the three-month moving average,” TD also highlights that “risks to our payrolls forecast are to the upside,” warning that “seasonal factors could reverse again more than expected and lead to a stronger print.”
USD/INR Technical Analysis: Can the decline extend towards 94.00?
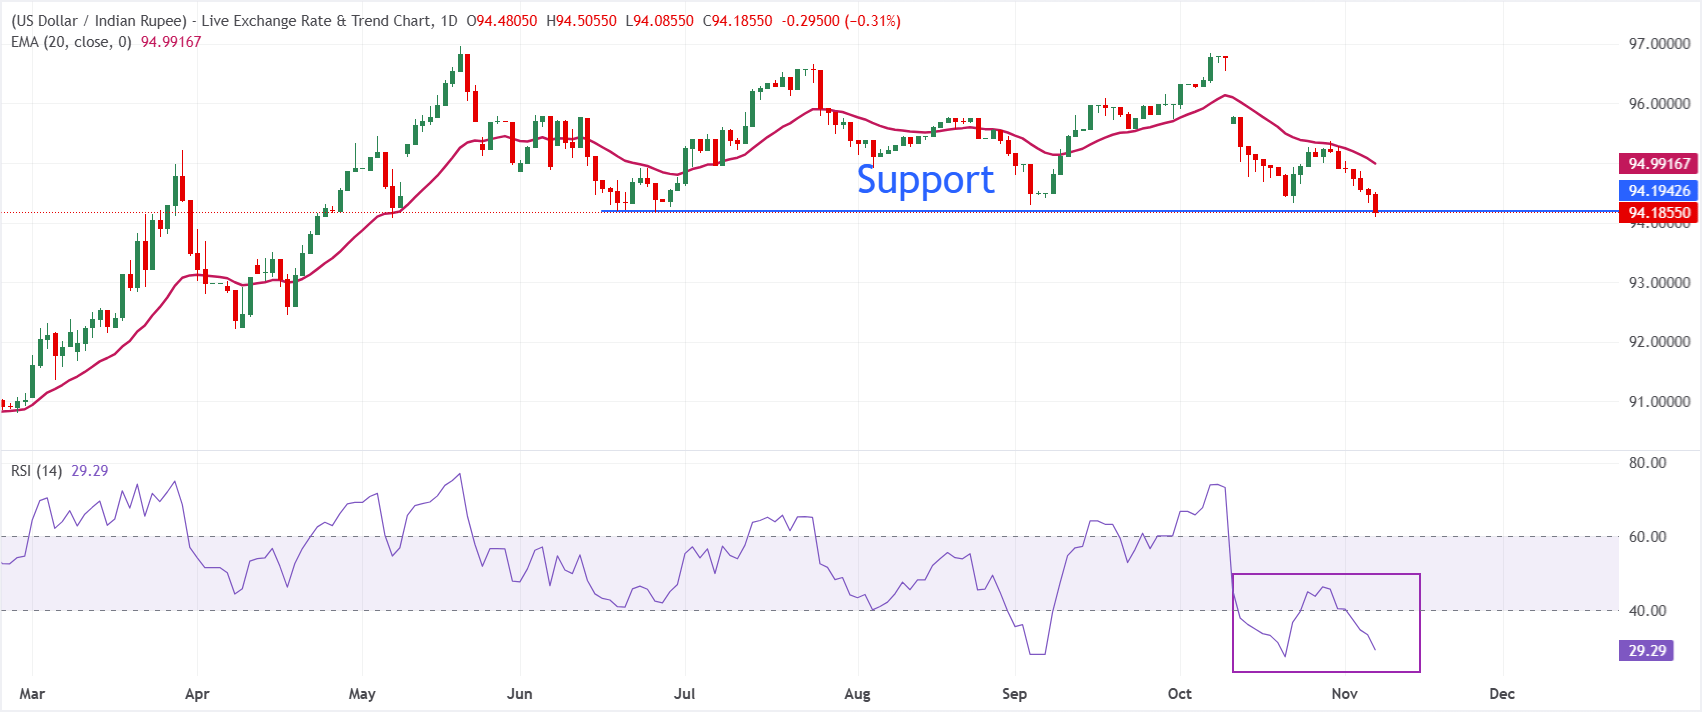
A move down to around 94.08 on Friday extends USD/INR’s retreat, with the pair remaining beneath its 20-day exponential moving average (EMA) of 94.99. This average continues to restrict gains and supports a bearish near-term outlook. At 29.29, the latest Relative Strength Index (RSI) reading is in oversold territory, indicating that selling may be stretched in the short term even as downside pressure prevails.
Further weakness could take the pair towards 94.00. Any rebound would first encounter resistance around the 20-day EMA at 94.99; a sustained move above that hurdle would be necessary to soften the prevailing bearish tone.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
Indian Rupee: Frequently asked questions
External developments have a particularly strong influence on the Indian Rupee (INR). Key drivers include Crude Oil prices, given India’s heavy reliance on imported Oil, the US Dollar’s value, as most trade is carried out in USD, and the scale of foreign investment. The Rupee is also significantly affected by the interest rates set by the Reserve Bank of India (RBI) and its direct intervention in FX markets to stabilise the exchange rate.
To facilitate trade, the Reserve Bank of India (RBI) actively participates in forex markets to keep the exchange rate stable. It also adjusts interest rates in an effort to maintain inflation at its 4% target. The Rupee typically gains when interest rates rise, partly because of the ‘carry trade’. Under this strategy, investors borrow in economies with lower interest rates and invest in those offering relatively higher rates, earning the difference.
Inflation, interest rates, economic growth (GDP), the trade balance and foreign investment inflows all help determine the Rupee’s value. Faster growth can attract additional overseas investment and lift demand for the currency, while a narrowing trade deficit will eventually strengthen it. Higher interest rates are supportive too, particularly real rates, which are interest rates adjusted for inflation. When risk appetite improves, greater inflows of Foreign Direct and Indirect Investment (FDI and FII) can also support the Rupee.
The Rupee generally suffers when inflation rises, especially when it exceeds levels in India’s peer economies, as this reflects a loss of value through oversupply. By making exports more expensive, inflation also results in more Rupees being sold to pay for imports, putting pressure on the currency. However, rising inflation usually prompts the Reserve Bank of India (RBI) to increase interest rates. This can support the Rupee by attracting stronger demand from overseas investors. Lower inflation has the reverse effect.
POPULAR ARTICLES
1USD/CHF Price Forecast: Can bulls overcome resistance at 0.8185 as bearish pressure eases?2Why is the British Pound still under pressure against the Yen as risk aversion offsets a hawkish BoE?3US Dollar: Safe haven demand offers support amid declines in AI shares – MUFG4Polish Zloty: Why is the PLN outlook weak despite hawkish rhetoric? – Commerzbank5US Dollar Index Price Forecast: How is safe-haven demand supporting a recovery above the 20-day EMA ahead of US NFP?6Why is the Euro wavering in a range against the British Pound despite upbeat German factory data?7Czech Koruna: Is range-bound trading against the Euro set to continue? – ING8USD/JPY Price Forecast: Are traders holding back below 158.00 as US NFP approaches?9Austria Wholesale Prices n.s.a (MoM) fell from previous 1.9% to -0.2% in October


Get Started!
Sign up and access the Global Markets in less than 3 minutes

Connect With Us









Contacts
Phone: +61 2 8036 8388
Fax: +61 2 8036 8388
Email: support@tmgm.com



The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved