

Trading
Explore a wide range of markets with competitive pricing, deep liquidity, and advanced trading tools.
Learn More 
Platform
Trade seamlessly with TMGM's powerful platform, built for speed, precision, and a superior trading experience.
Learn More Trading Platform
Academy
Learn the fundamentals of trading with beginner-friendly resources, including guides, webinars, and market insights.
Learn More News & Analysis
Get real-time market updates and expert analysis to stay ahead of trading opportunities
Learn More News & Analysis
About
Learn what sets TMGM apart — our global presence, regulatory strength, and commitment to innovation in trading.
Learn More Why Choose TMGM
Sponsorship
Yen faces Tokyo CPI and a BoJ decision as central bank week draws to a close
- Trading just below 158.00, USD/JPY has recovered the bulk of its October 22-23 decline.
- Most Fed officials do not view the economy as overheating, according to Fed Chair Warsh.
- Ahead of Friday's BoJ decision, markets assign a probability of nearly 86% to rates remaining at 1.25%.
USD/JPY has recouped most of its October 22-23 losses, with the Fed's decision to keep rates unchanged failing to extend that decline. Before the decision, the pair traded above 158.00; as Fed Chair Warsh's press conference opened, it reached a session peak below 158.50. It has since returned to just below 158.00, remaining above the session trough of slightly over 157.50.
The move above 158.00 unwound while Fed Chair Warsh answered questions, following the Fed's decision to retain rates at 3.75%-4.00%, compared with 1.25% at the Bank of Japan (BoJ). Warsh said most Fed officials did not consider the US economy to be overheating and that stronger growth did not, on its own, imply higher inflation.
A worldwide sell-off in technology shares accompanied USD/JPY's October 22-23 decline, as investors repurchased the Yen they had borrowed. The pair subsequently recovered alongside a rebound in chip stocks on Monday and Tuesday. Compared with Monday's chip-stock recovery, Wednesday's Fed announcement and press conference produced a narrower trading range in USD/JPY.
Which releases could shape the rate gap?
The Fed side of USD/JPY's interest-rate differential will be informed by Thursday's US third-quarter growth and September price releases at 12:30 GMT. At 23:30 GMT, attention turns to Tokyo's October Consumer Price Index (CPI): the reading excluding fresh food is projected at 2.6%, down from 2.7%. Japan's unemployment rate is expected to remain at 2.5%.
No fixed release time has been set for Friday's BoJ decision. The quarterly outlook report is scheduled for 03:00 GMT, followed by questions to BoJ Governor Ueda at 06:30 GMT. As markets price in nearly an 86% chance of unchanged rates, these events will have a bearing on when the next hike comes, shaping the BoJ side of the differential.
Where does USD/JPY stand on the charts?
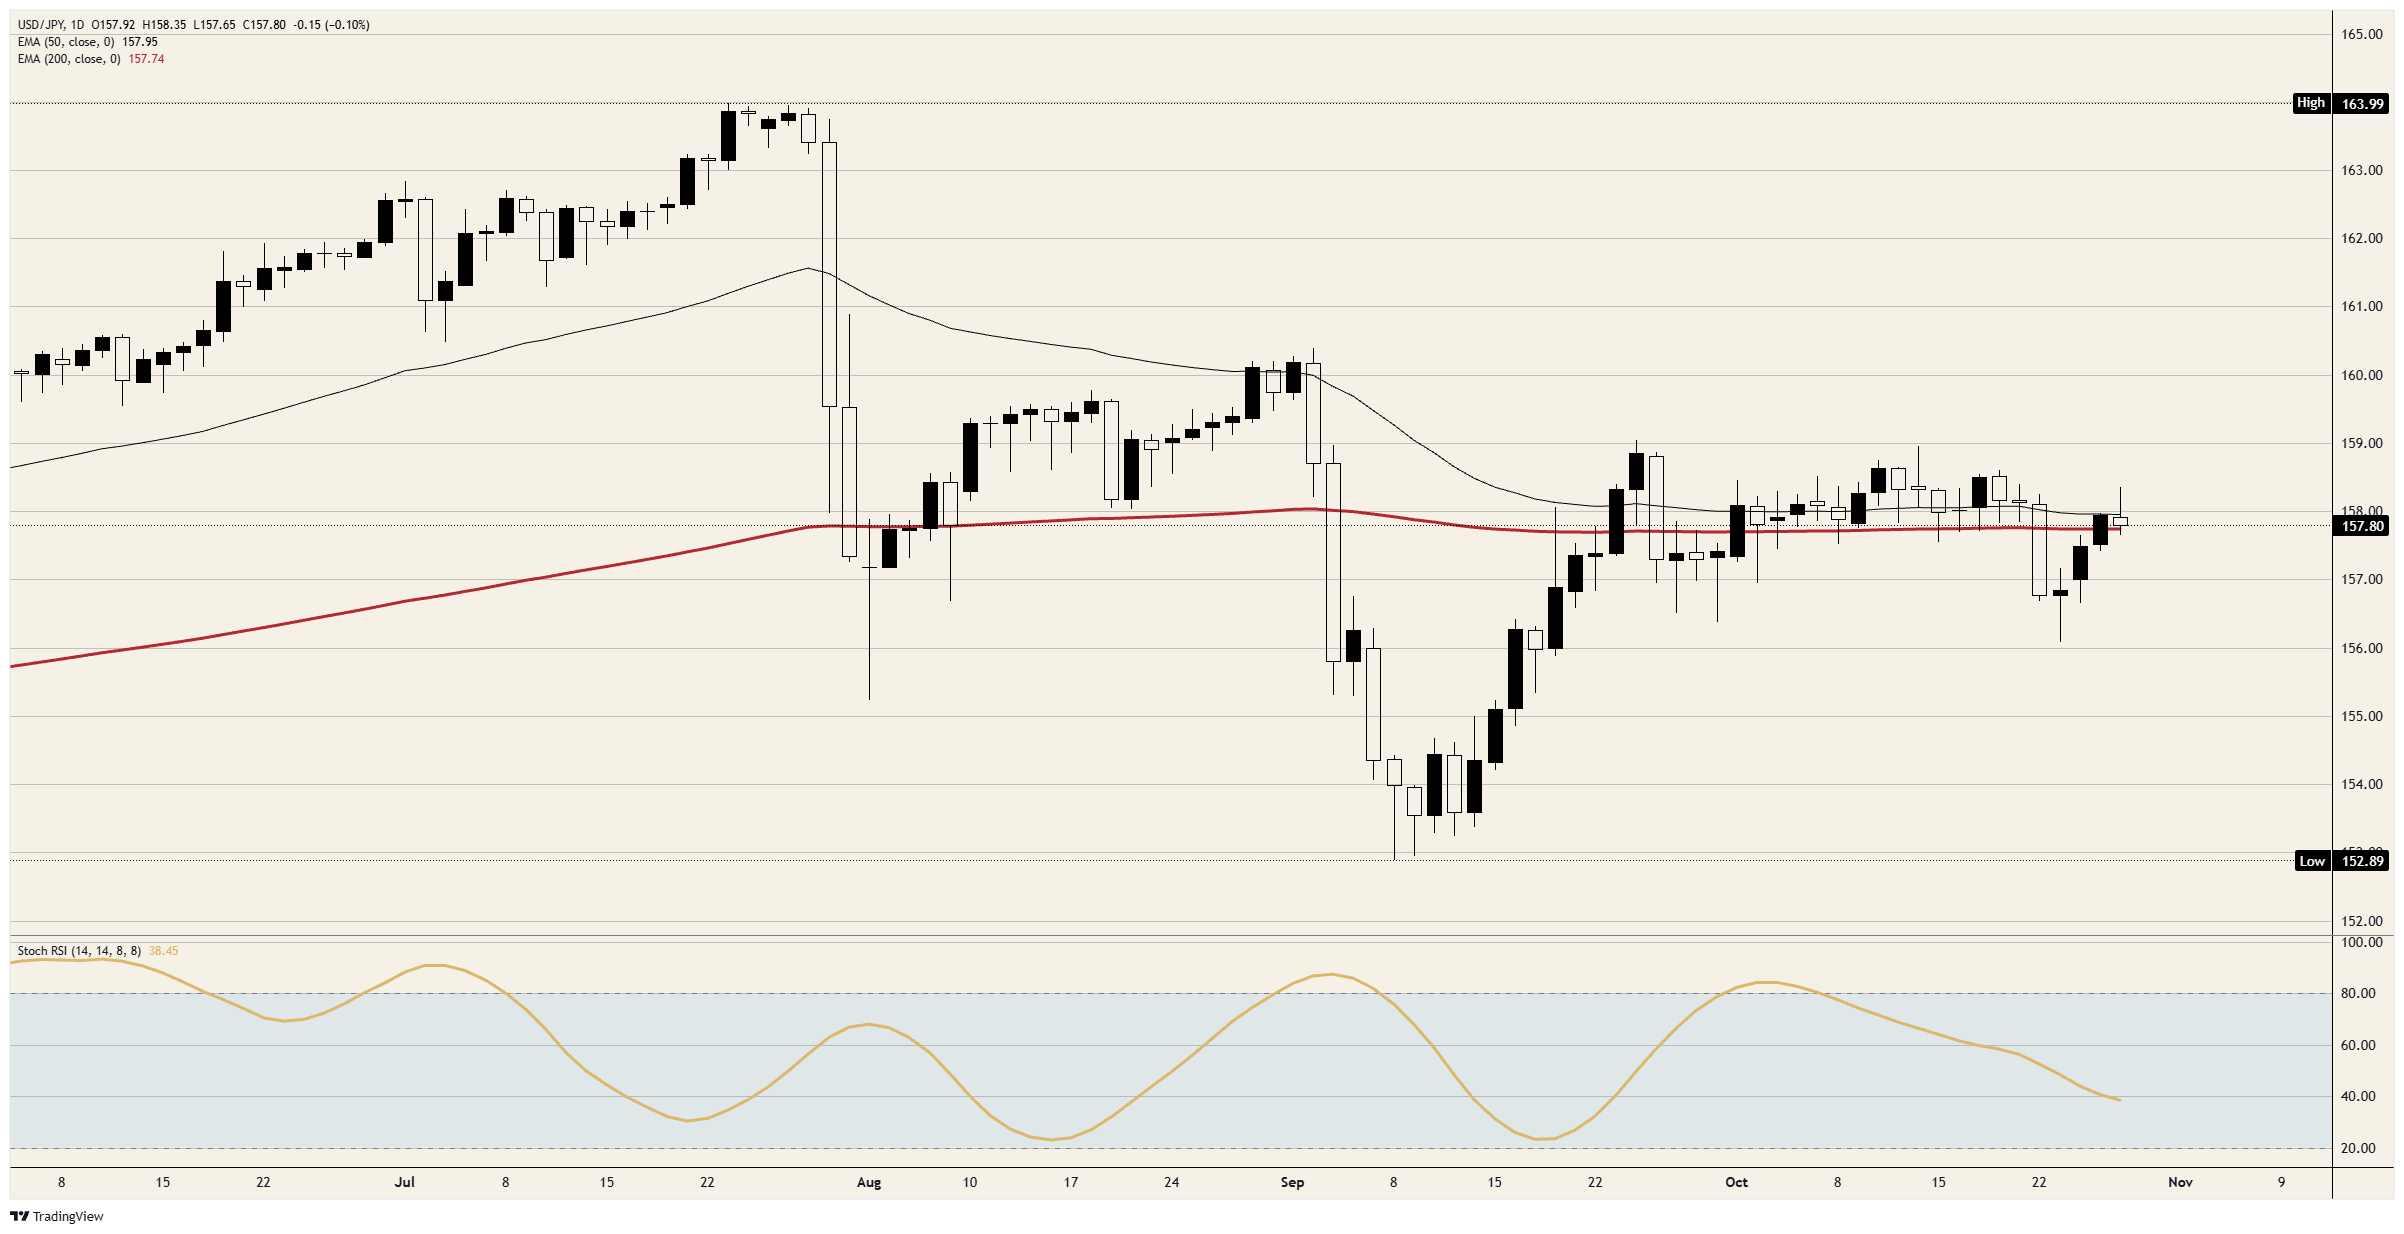
USD/JPY sits between its 50-day and 200-day Exponential Moving Averages (EMA), which are separated by roughly a fifth of a yen. Its trading range since October 1 extends from slightly above 156.00 to just below 159.00, with the October 23 trough marking the lowest point across those sessions.
Daily chart: USD/JPY
Japanese Yen: Common Questions
Among the most actively traded currencies globally, the Japanese Yen (JPY) broadly reflects Japan’s economic performance. More specifically, factors influencing its value include Bank of Japan policy, the gap between Japanese and US bond yields, and traders’ appetite for risk.
Currency control forms part of the Bank of Japan’s mandate, making its actions important for the Yen. On occasion, the BoJ has intervened directly in currency markets, usually to weaken the Yen, but political concerns among Japan’s main trading partners discourage frequent intervention. Between 2013 and 2024, its ultra-loose monetary stance weakened the Yen against major peers as policy increasingly diverged from that of other leading central banks. More recently, a gradual withdrawal of this ultra-loose policy has provided the Yen with some support.
By maintaining ultra-loose monetary policy over the past decade, the BoJ increasingly diverged from other central banks, especially the US Federal Reserve. That divergence helped widen the yield gap between 10-year US and Japanese bonds, benefiting the US Dollar relative to the Japanese Yen. The differential is now narrowing as the BoJ’s 2024 decision to gradually exit ultra-loose policy coincides with interest-rate reductions by other major central banks.
Investors often regard the Japanese Yen as a safe haven, making them more inclined to move money into the currency during periods of market stress because of its perceived dependability and stability. In turbulent conditions, the Yen is therefore likely to appreciate against currencies considered riskier investments.
POPULAR ARTICLES
1PBOC lowers USD/CNY reference rate to 6.7147 from 6.71652Why are US Dollar strength and safe-haven outflows dragging the Japanese Yen lower?3Middle East supply risks push WTI above $101.004Yen faces Tokyo CPI and a BoJ decision as central bank week draws to a close5Can US data steer the New Zealand Dollar after both central banks hold rates?6Gold Slips to Around $4,050 After Fed Keeps Rates Unchanged; Markets Await US PCE Data7Can the Australian Dollar hold above 0.7050 as hot CPI strengthens RBA hike bets?8Euro returns to its October low as the ECB looms9Pound back above 1.33: what lies ahead as US inflation figures approach?
LIVE QUOTES

ALL ABOUT FOREX
What Is a Stop Loss, How Does It Work and How Do You Set One?
Margin Call Meaning: What It Is, What Triggers It, and How to Avoid One
What Is an Islamic Account in Forex?
Best Indicators for Forex Trading and How to Use Them
The Top 10 Most Traded Currency Pairs in the World
What are the Major Forex Pairs? 7 Major Currency Pairs in the World
5 Best Forex Trading Apps In India In 2026
Top 15 Weakest Currencies in the World
Best Time to Trade Forex
Get Started!
Sign up and access the Global Markets in less than 3 minutes

Connect With Us









Contacts
Phone: +61 2 8036 8388
Fax: +61 2 8036 8388
Email: support@tmgm.com



The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved