

Trading
Explore a wide range of markets with competitive pricing, deep liquidity, and advanced trading tools.
Learn More 
Platform
Trade seamlessly with TMGM's powerful platform, built for speed, precision, and a superior trading experience.
Learn More Trading Platform
Academy
Learn the fundamentals of trading with beginner-friendly resources, including guides, webinars, and market insights.
Learn More News & Analysis
Get real-time market updates and expert analysis to stay ahead of trading opportunities
Learn More News & Analysis
About
Learn what sets TMGM apart — our global presence, regulatory strength, and commitment to innovation in trading.
Learn More Why Choose TMGM
Sponsorship
43.5K jobs lost in Australia: Aussie dollar drops to 2026 low
- 0.6700 gives way: AUD/USD hits a 2026 low just above 0.6650.
- 4.9% unemployment marks the highest rate since 2021 as expectations of an RBA hike recede.
- Friday brings China's central bank rate decision, followed by US sentiment data.
43.5K jobs were lost in Australia in October. Forecasts had pointed to a 25K increase. The Australian Dollar has since reached its lowest level of 2026. Following the release, AUD/USD broke below 0.6700 and extended its decline as US equities sold off. It now trades just above 0.6650, beneath January's trough, which had been the year's low.
Of the jobs lost, 40.6K were part-time positions. Unemployment climbed from 4.7% to 4.9%, a level last seen in late 2021. Just 16 days before the report, on 3 November, the Reserve Bank of Australia (RBA) had lifted its cash rate to 4.85% in a 6-3 vote. With CommBank already forecasting an unchanged rate at the 7-8 December meeting, analysts now consider the hiking cycle finished.
At 4.85%, Australia's rate remains higher than the Fed's 3.75%-4.00% range. However, expectations of a Fed increase on 9 December, against an anticipated RBA hold, narrow the Australian Dollar's interest-rate advantage. This comes in a session in which US stocks declined 2% and the Pound also reached a 2026 low.
3% China rate forecast leads Friday's calendar
At 01:15 GMT on Friday, the People's Bank of China (PBoC) will deliver its rate decision, with forecasts pointing to no change at 3%. No Australian data releases are due that day. China remains the largest buyer of Australia's exports.
Friday's US schedule starts with Fed Governor Waller speaking at 13:25 GMT, followed by the University of Michigan's November survey at 15:00 GMT and remarks from Fed Governor Cook at 17:15 GMT. The survey's one-year inflation expectations are forecast to stay at 4.3%, with five-year expectations at 3.4%. These readings will inform the Fed's 9 December decision, with the US side of the rate differential still shifting.
400-pip slide puts AUD/USD momentum in oversold territory
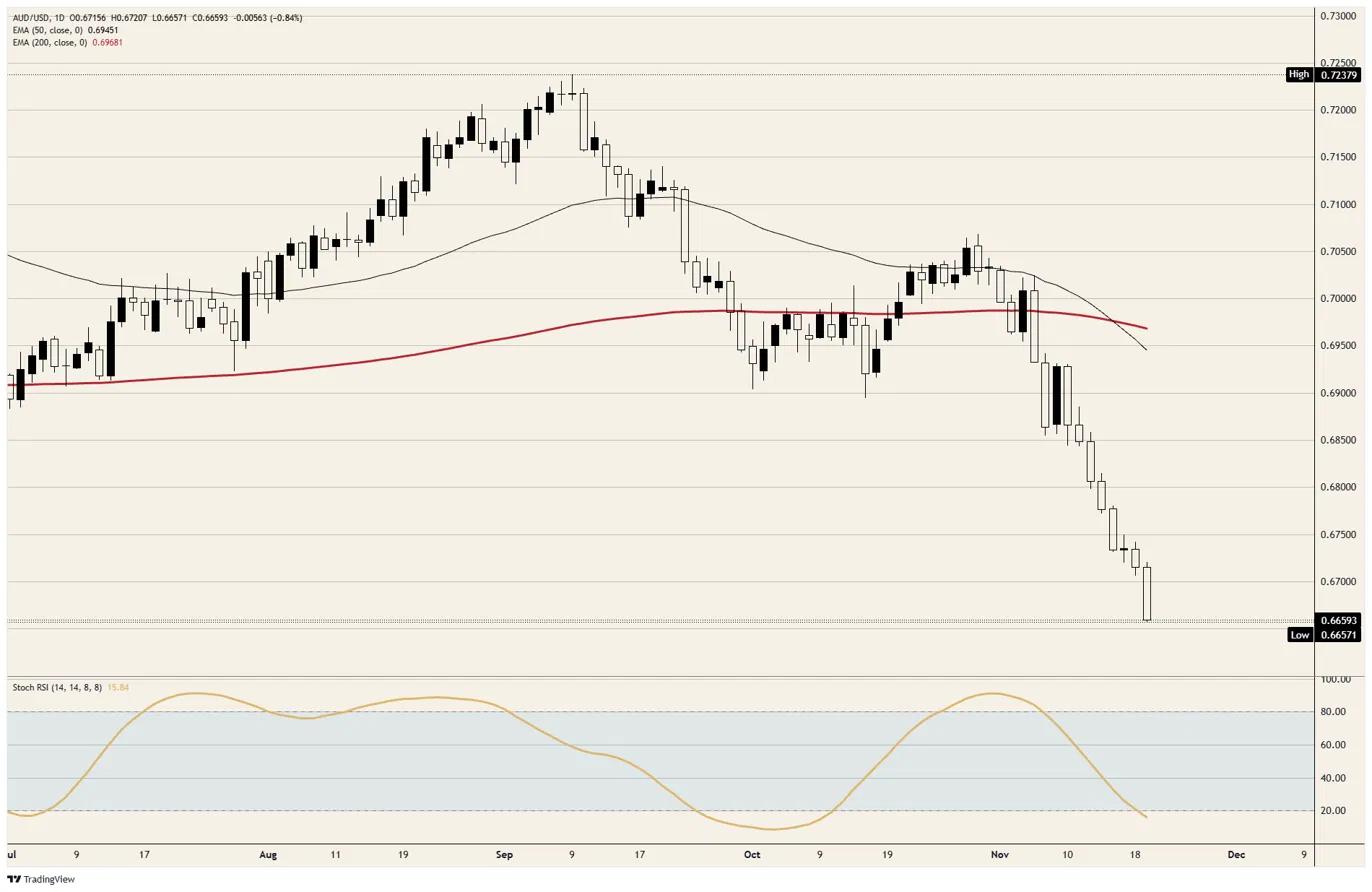
Over three weeks, AUD/USD has shed about 400 pips from its 29 October peak near 0.7050. It broke away from the 0.6900 zone on 6 November after that area had held twice in October. Near 0.6950, the 50-day Exponential Moving Average (EMA) has moved below the 200-day EMA. The pair now stands about 8% below its September peak near 0.7250, while daily momentum has entered oversold territory for the first time since early October.
AUD/USD: daily price chart
Australian Dollar: frequently asked questions
Interest rates set by the Reserve Bank of Australia (RBA) are among the strongest influences on the Australian Dollar (AUD). Australia's resource-rich economy also makes the price of Iron Ore, its largest export, a key driver. Other influences include economic conditions in China, Australia's biggest trading partner, alongside domestic inflation, economic growth and the Trade Balance. Investor appetite for risk matters too. A shift towards riskier assets (risk-on) generally supports AUD, while a preference for safe havens reflects risk-off sentiment.
By setting the interest rate at which Australian banks lend to one another, the Reserve Bank of Australia (RBA) influences borrowing rates across the economy and, in turn, the Australian Dollar (AUD). Its primary objective is stable inflation of 2-3%, pursued through increases or reductions in interest rates. Rates that are relatively high compared with those of other major central banks support AUD; relatively low rates have the reverse effect. Quantitative easing and quantitative tightening offer further ways for the RBA to affect credit conditions. Easing is negative for AUD, whereas tightening is positive.
As Australia's biggest trading partner, China has a substantial influence on the Australian Dollar (AUD). A strong Chinese economy buys more Australian raw materials, goods and services, increasing demand for AUD and raising its value. When Chinese growth falls short of expectations, the reverse applies. Chinese growth figures that surprise either positively or negatively therefore often affect the Australian Dollar and its currency pairs directly.
At $118 billion annually, according to 2021 data, Iron Ore is Australia's biggest export, with China the main destination. This makes its price an important potential influence on the Australian Dollar. Rising Iron Ore prices generally increase overall demand for AUD, lifting the currency; falling prices generally have the opposite effect. More expensive Iron Ore also tends to improve the likelihood of an Australian Trade Balance surplus, providing further support for AUD.
Another influence on the Australian Dollar is the Trade Balance: export earnings minus expenditure on imports. Strong foreign demand for Australian exports can lift the currency through the excess demand generated by overseas buyers relative to Australia's spending on imports. A positive net Trade Balance therefore strengthens AUD, while a negative balance has the reverse effect.
POPULAR ARTICLES
114-month low: gold slips below $3,650 as hawkish Fed signals weigh243.5K jobs lost in Australia: Aussie dollar drops to 2026 low32026 low: Pound at fresh trough ahead of UK retail sales4$62,000 breached: Bitcoin falls while AI tokens outperform after Anthropic IPO5Near 160.00 again: Yen awaits Japan's October CPI release61.10 remains out of reach for Euro as Dollar shrugs off weak US data7Over 1,000 points: Dow Jones Industrial Average slides as Anthropic IPO takes centre stage8Below $1,800: Ethereum (ETH) price forecast as Anthropic debuts9Indonesian Rupiah: BI’s hawkish shift raises risk of further tightening – Commerzbank

Get Started!
Sign up and access the Global Markets in less than 3 minutes

Connect With Us









Contacts
Phone: +61 2 8036 8388
Fax: +61 2 8036 8388
Email: support@tmgm.com



The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved