

Trading
Explore a wide range of markets with competitive pricing, deep liquidity, and advanced trading tools.
Learn More 
Platform
Trade seamlessly with TMGM's powerful platform, built for speed, precision, and a superior trading experience.
Learn More Trading Platform
Academy
Learn the fundamentals of trading with beginner-friendly resources, including guides, webinars, and market insights.
Learn More News & Analysis
Get real-time market updates and expert analysis to stay ahead of trading opportunities
Learn More News & Analysis
About
Learn what sets TMGM apart — our global presence, regulatory strength, and commitment to innovation in trading.
Learn More Why Choose TMGM
Sponsorship
Below 1.12: Euro faces Fed and ECB decisions a day apart
- Below 1.1200: EUR/USD closes at its low for the first time since 14 October.
- 91.6 Ifo expectations reading fails to sustain EUR/USD gains, erased within 11 bars.
- Thursday's ECB decision is expected to leave rates unchanged, following the Fed's on Wednesday.
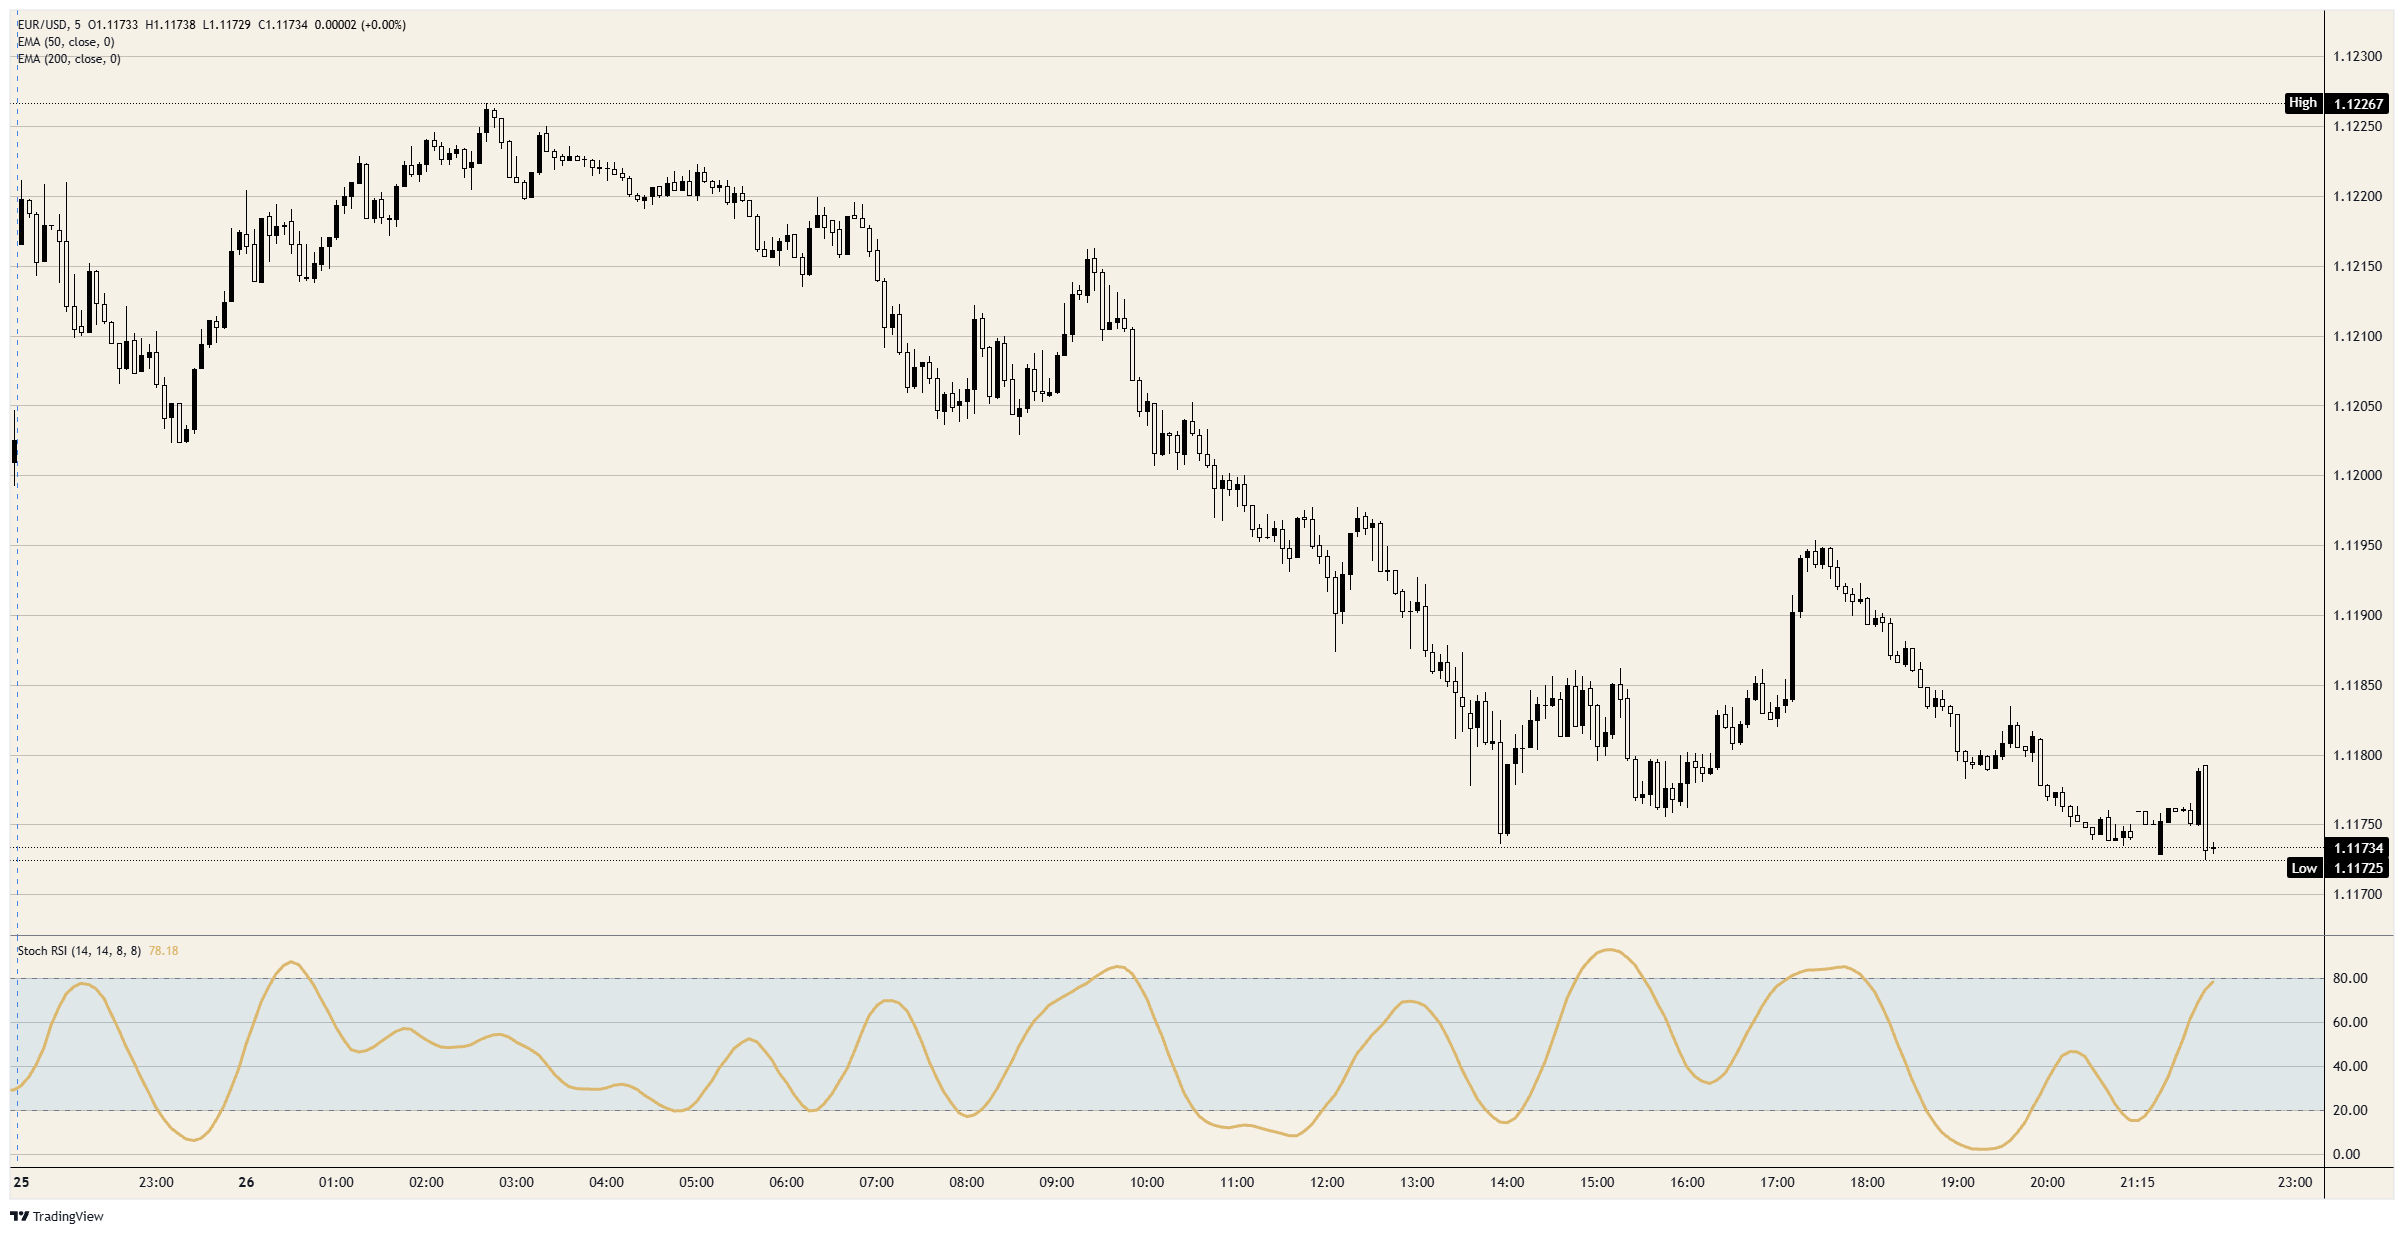
EUR/USD closed below 1.1200 for the first time since 14 October. The pair finished at its low after Dollar buying ahead of the Federal Open Market Committee (FOMC) meeting, which concludes Wednesday, pushed it to its weakest level since 15 October. Earlier on Monday, Germany's Ifo survey exceeded forecasts, but EUR/USD had slipped below its pre-release level by the 11th five-minute bar.
About 4.71% was the level reached by the US two-year yield ahead of the Fed meeting. At 3.75%-4.00%, the Fed's rate range already stands well above the European Central Bank (ECB) deposit rate of 2.50%. Futures imply a near 80% probability of a December Fed increase, which would extend the rate advantage favouring the Dollar.
A rise to 90.2 took the Ifo business climate above the 89.8 forecast. Expectations climbed from 90.4 to 91.6, while the current assessment slipped from 89.5 to 88.8. The stronger German outlook reinforces the case for an ECB rate increase in December, as expected by 64 of 73 economists surveyed by Reuters. The subsequent EUR/USD decline was more than four times the size of its initial advance on the release.
Key policy and data releases
A 0.6% increase is forecast for US durable goods orders, due Tuesday at 12:30 GMT, following a 0.1% decline. On Wednesday, the Fed is expected to announce unchanged rates in its 18:00 GMT statement. Fed Chair Warsh will take questions at 18:30 GMT, with a December increase still unresolved.
Tuesday's ECB bank lending survey at 09:00 GMT precedes a speech by ECB President Lagarde at 17:00 GMT. The rate announcement follows on Thursday at 13:15 GMT, with the deposit rate expected to remain at 2.50%. For the Euro, the ECB's December decision will determine its side of the interest-rate gap.
EUR/USD technical picture
About three-fifths of the rebound from the 14 October low, just above 1.1100, to the 16 October high, just above 1.1250, was erased by Monday's decline. EUR/USD trades beneath both its 50-day Exponential Moving Average (EMA), just above 1.1350, and its 200-day EMA, just below 1.1500. Both averages have declined in every session since mid-September.
EUR/USD chart: 5-minute timeframe
Euro: key questions answered
Used by the 20 European Union countries within the Eurozone, the Euro ranks second only to the US Dollar in global currency trading. Its share of all foreign exchange transactions was 31% in 2022, with daily turnover averaging more than $2.2 trillion. An estimated 30% of all transactions involve EUR/USD, making it the world's most actively traded currency pair. Next are EUR/JPY (4%), EUR/GBP (3%) and EUR/AUD (2%).
Based in Frankfurt, Germany, the European Central Bank (ECB) serves as the Eurozone's reserve bank, setting interest rates and directing monetary policy. Maintaining price stability is its core mandate, whether through containing inflation or supporting growth. Interest-rate increases and cuts are its main policy instrument. The Euro generally benefits from relatively high rates, or expectations of higher rates, while the reverse also applies. Monetary policy is decided by the ECB Governing Council at eight meetings each year. The decision-makers comprise the heads of Eurozone national banks and six permanent members, among them ECB President Christine Lagarde.
Measured by the Harmonised Index of Consumer Prices (HICP), Eurozone inflation is a key economic indicator for the Euro. A stronger-than-expected rise in inflation, particularly above the ECB's 2% target, requires the central bank to increase interest rates to restore control over prices. By making the region a more attractive destination for global investors' funds, interest rates that are relatively high compared with those of its counterparts generally support the Euro.
The Euro can respond to economic releases because they indicate the economy's health. GDP, Manufacturing and Services PMIs, employment figures and consumer sentiment surveys can all shape the single currency's direction. By drawing in more foreign investment and potentially prompting the ECB to raise interest rates, a strong economy supports the Euro. Higher rates would directly strengthen the currency. Weak economic figures, by contrast, are likely to weigh on the Euro. Particular importance attaches to data from Germany, France, Italy and Spain, the euro area's four largest economies. Together, they represent 75% of the Eurozone economy.
For the Euro, the Trade Balance is another important economic release. Over a specified period, it records the difference between a country's export earnings and its spending on imports. Strong overseas demand for a country's exports creates additional demand for its currency as foreign buyers seek to purchase those goods, lifting the currency's value. A positive net Trade Balance therefore supports a currency, whereas a negative balance has the opposite effect.
POPULAR ARTICLES
1Above $4,000: gold rebounds on hopes of easing US‑Iran tensions2Half its gain erased: Yen retreats ahead of expected BoJ hold on Friday30.70 rally falters for Aussie Dollar ahead of Fed, RBA inflation tests4Third straight RBNZ hike priced in by New Zealand Dollar traders5Below 1.12: Euro faces Fed and ECB decisions a day apart6Pound retreats from its high ahead of UK Budget and Fed decision7Anthropic's filing boosts tech while Dow Jones Industrial Average trails8211.10 in bulls’ sights: GBP/JPY Price Forecast as bearish trend continues9Iran peace hopes buoy sentiment as Mexican Peso withstands Dollar strength
LIVE QUOTES


Get Started!
Sign up and access the Global Markets in less than 3 minutes

Connect With Us









Contacts
Phone: +61 2 8036 8388
Fax: +61 2 8036 8388
Email: support@tmgm.com



The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved