

Trading
Explore a wide range of markets with competitive pricing, deep liquidity, and advanced trading tools.
Learn More 
Platform
Trade seamlessly with TMGM's powerful platform, built for speed, precision, and a superior trading experience.
Learn More Trading Platform
Academy
Learn the fundamentals of trading with beginner-friendly resources, including guides, webinars, and market insights.
Learn More News & Analysis
Get real-time market updates and expert analysis to stay ahead of trading opportunities
Learn More News & Analysis
About
Learn what sets TMGM apart — our global presence, regulatory strength, and commitment to innovation in trading.
Learn More Why Choose TMGM
Sponsorship
Further oil price rises erase Indian Rupee’s weekly gains
- Higher oil prices drive further Indian Rupee losses against the US Dollar.
- Energy supplies remain at risk as Middle East tensions persist.
- October’s flash HSBC Global PMI readings show continued strength in India.
USD/INR jumps towards 94.92. Extending Thursday’s decline against the US Dollar (USD), the Indian Rupee gives up almost all of its earlier gains this week on Friday. Oil prices surging on Middle East tensions have put the Indian currency under heavy pressure.
Early trading sees the MCX Crude Oil contract for November 19 expiry rise 0.65% to around Rs. 9,550. That leaves the price near its recent high of Rs. 9,661 reached earlier this week.
For economies such as India, heavy reliance on imported oil to meet energy needs makes higher crude prices a negative for their currencies.
Saudi Drone Attack Escalates Middle East Tensions
The impact on crude ultimately remained contained, according to Commerzbank analysts, despite Middle East tensions that “intensified after a drone attack on Saudi Arabia's Shaybah oil field killed two people and injured two others,” they report. Describing the initial reaction, they note that “oil prices briefly jumped on reports suggesting a wider withdrawal of US diplomatic personnel from the Gulf,” but the rally faded after “Washington clarified that the order was limited to Saudi Arabia,” leading the market to trim its earlier gains.
Fears of a further escalation in military aggression in Iran have followed the withdrawal of US non-emergency personnel from the Gulf.
October Private Sector Output Holds Firm in India
At 56.7, India’s Composite PMI exceeds September’s final reading of 55.9. Preliminary HSBC Global Purchasing Managers’ Index (PMI) figures for October show stronger overall business activity, with robust services activity driving the significant rise in the composite measure.
Pranjul Bhandari, Chief India Economist at HSBC, said: “Private-sector manufacturing activity continued to expand, with growth of output and new orders broadly unchanged at last month’s levels. However, the steady pace of new order growth masks the fastest increase in new export orders since June 2025. Manufacturers responded by increasing their stocks of purchases and finished goods. Input cost inflation eased, while the rise in selling prices softened to its weakest in almost four years,”
13:45 GMT: US Flash PMI Due
The preliminary October US S&P Global PMI release is due at 13:45 GMT, with investors awaiting the figures. Expectations point to another expansion in both manufacturing and services activity, though at a moderate pace.
USD/INR: Technical Outlook
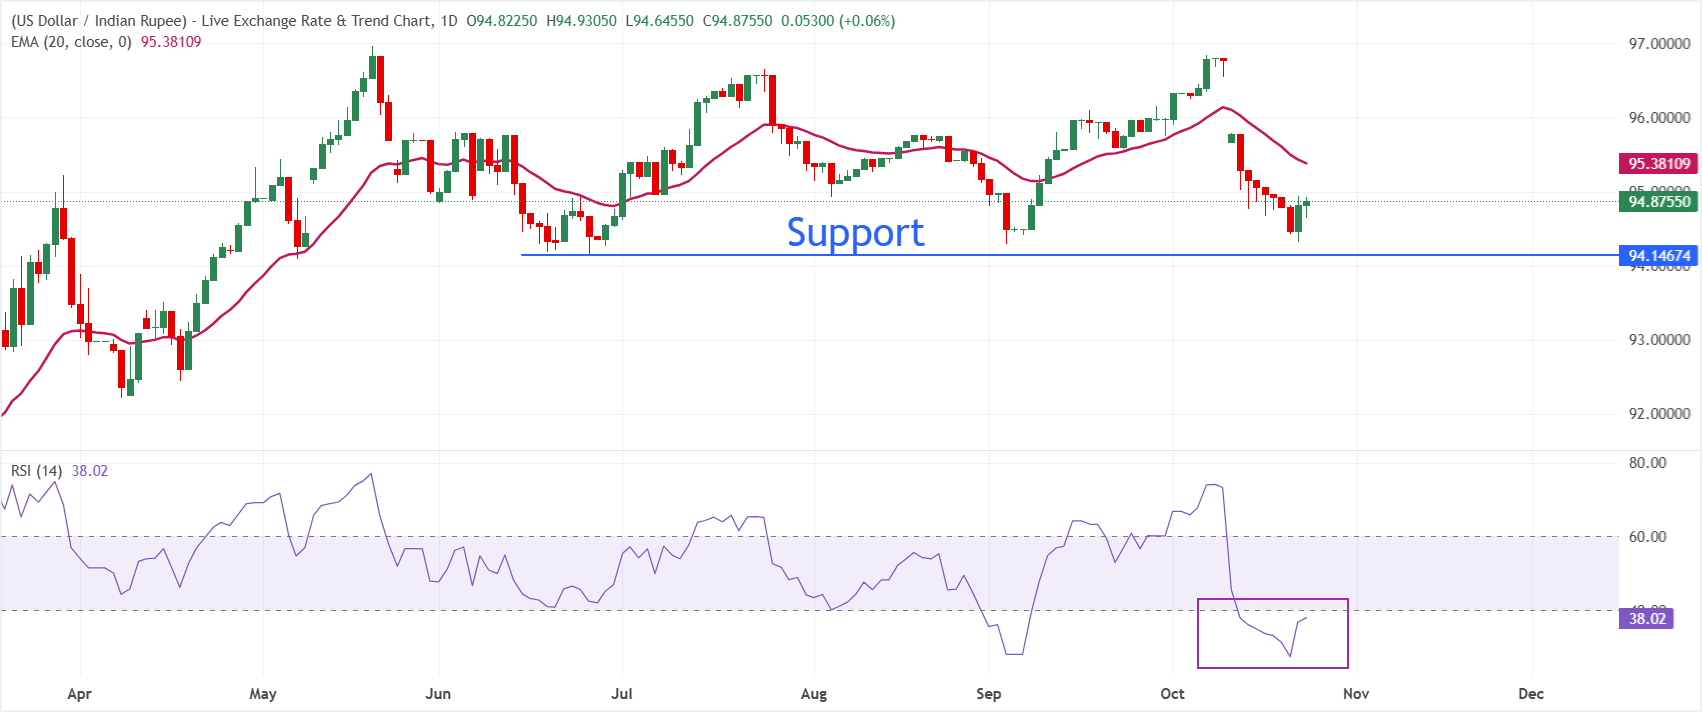
At 94.92 on the daily chart, USD/INR remains below its 20-day exponential moving average (EMA) of 95.38, preserving a bearish short-term bias.
Following a steep pullback from recent highs, the pair’s Relative Strength Index (14) stands at 37.94, just above oversold territory. Downward momentum therefore persists, although selling pressure may be easing.
A recovery must first clear immediate resistance at the 20-day EMA near 95.38 to reduce the prevailing downside bias. This level continues to limit rebounds. On the downside, key support lies at 94.15, the June 25 low.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
Indian Rupee: Frequently Asked Questions
External developments have a particularly strong influence on the Indian Rupee (INR). Key drivers include Crude Oil prices, given India’s heavy dependence on imported Oil; the US Dollar’s value, as most trade is settled in USD; and foreign investment levels. The Reserve Bank of India (RBI) also plays a major role through direct FX market intervention aimed at stabilising the exchange rate and through the interest rates it sets.
To support trade through exchange-rate stability, the Reserve Bank of India (RBI) intervenes actively in forex markets. Interest-rate adjustments are another tool, used to keep inflation at its 4% target. Higher rates typically support the Rupee through the ‘carry trade’: investors borrow in lower-interest-rate countries and invest in those offering relatively higher rates, earning the difference.
Inflation, interest rates, GDP growth, the trade balance and foreign investment inflows all help determine the Rupee’s value. Faster economic growth can attract additional overseas investment and lift demand for the currency. A narrowing trade deficit will eventually strengthen the Rupee, while higher interest rates, particularly real rates after subtracting inflation, are also supportive. Greater risk appetite can encourage inflows of Foreign Direct and Indirect Investment (FDI and FII), further benefiting the currency.
For the Rupee, higher inflation is generally unfavourable, especially when it exceeds that of India’s peers, because it signals devaluation through excess supply. By raising export costs, inflation also results in more Rupees being sold to buy foreign imports, adding pressure on the currency. However, rising inflation typically prompts the Reserve Bank of India (RBI) to increase interest rates. The resulting demand from international investors can support the Rupee. Lower inflation has the reverse effect.
POPULAR ARTICLES
1Above $100: WTI oil climbs on renewed supply disruption concerns2Euro loses ground to US Dollar as risk concerns weigh - Danske Bank3Gold: Prices under pressure from energy-driven inflation – ING4Forex Today: Key PMI data in focus as choppy trading persists5BoJ policy and capital flows support Japanese Yen gains against US Dollar - Commerzbank6Soft UK Retail Sales fail to deter British Pound buyers71.4000: USD/CAD Price Forecast as pair trades near level with bearish bias intact8Hormuz risks and freight costs lift oil prices – Rabobank9Near one-month highs: British Pound holds steady despite weak UK Retail Sales data


Get Started!
Sign up and access the Global Markets in less than 3 minutes

Connect With Us









Contacts
Phone: +61 2 8036 8388
Fax: +61 2 8036 8388
Email: support@tmgm.com



The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved