

Trading
Explore a wide range of markets with competitive pricing, deep liquidity, and advanced trading tools.
Learn More 
Platform
Trade seamlessly with TMGM's powerful platform, built for speed, precision, and a superior trading experience.
Learn More Trading Platform
Academy
Learn the fundamentals of trading with beginner-friendly resources, including guides, webinars, and market insights.
Learn More News & Analysis
Get real-time market updates and expert analysis to stay ahead of trading opportunities
Learn More News & Analysis
About
Learn what sets TMGM apart — our global presence, regulatory strength, and commitment to innovation in trading.
Learn More Why Choose TMGM
Sponsorship
3.7% YoY: New Zealand Q3 CPI Inflation Slows, Below 3.8% Expected
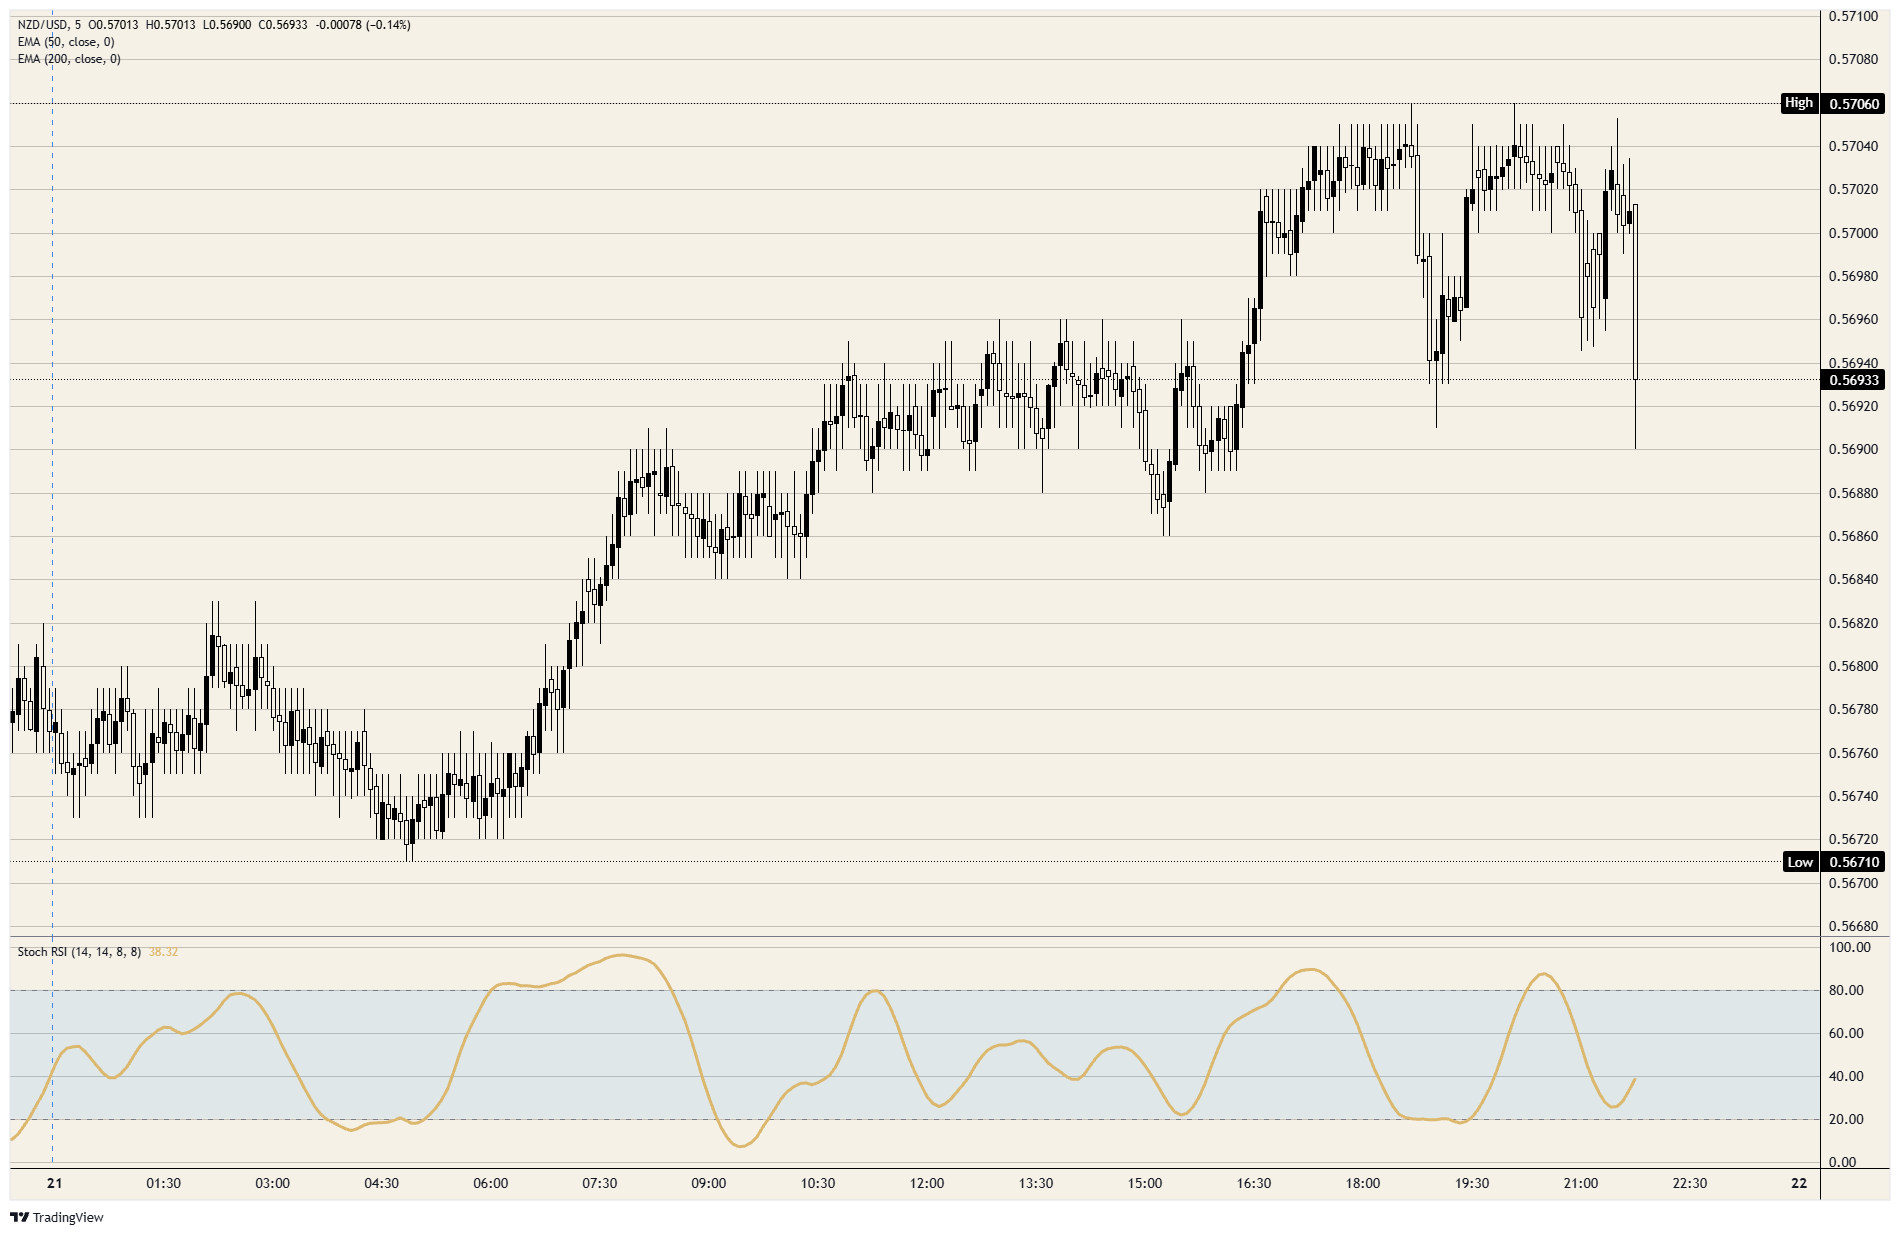
NZD/USD slipped back below 0.5700. New Zealand's third-quarter Consumer Price Index (CPI) undershot forecasts by a tenth on both the quarterly and annual readings, knocking the Kiwi off its four-week high. On the release bar, the pair moved from just above 0.5700 to just below it, returning to where it had traded before breaking through that level earlier in the session.
Annual inflation slowed from 4.1% to 3.7%, below the 3.8% forecast. Quarterly prices increased 0.7%, against expectations of 0.8%. In September, the Reserve Bank of New Zealand (RBNZ) had forecast 3.9%. Based on that projection, the Kiwi's five-session advance had priced in a rate increase on 28 October. The latest figures have weakened that case.
Tradable prices, which include petrol and diesel, accounted for the weakness. Non-tradable prices increased 1.0% quarter on quarter and 3.3% year on year. Westpac estimated that fuel subtracted about 0.4 points from the quarterly rate. The only bank in the survey to predict 3.7%, Westpac had described the decline as a temporary reprieve before the figures were published.
NZD/USD gives back a tenth of its five-session gain
About a tenth of the five-session advance from the 14 October low just above 0.5550 has been erased following the release. Before the data, daily momentum had approached overbought territory. The rally had stalled below the 50-day Exponential Moving Average (EMA), which sits just above 0.5700. NZD/USD has remained below that average since early September.
5-minute chart: NZD/USD
Inflation: key questions answered
A rise in the cost of a representative basket of goods and services is measured as inflation. The headline rate is generally reported as a percentage change month on month (MoM) and year on year (YoY). By excluding more volatile components, including food and fuel, core inflation removes items whose prices can swing with geopolitical and seasonal factors. Economists focus on this core measure. It is also the rate targeted by central banks, whose mandate is to maintain manageable inflation, typically around 2%.
Changes in the cost of a basket of goods and services over a given period are tracked by the Consumer Price Index (CPI). The measure is generally reported as a percentage change month on month (MoM) and year on year (YoY). Central banks target Core CPI because volatile food and fuel components are excluded. A Core CPI reading above 2% usually leads to higher interest rates; a reading below 2% usually has the reverse effect. Higher rates support a currency, so rising inflation typically strengthens it. Falling inflation generally has the opposite effect.
Higher inflation tends to lift a country's currency, while lower inflation tends to weaken it, despite this relationship seeming counter-intuitive. The reason is the central bank's usual response: raising interest rates to curb stronger inflation. Those higher rates draw more capital from global investors seeking attractive returns on their money.
Investors historically sought Gold during periods of high inflation for its ability to retain value. They still often buy it as a safe haven during extreme market turmoil, but it is not usually their response to inflation. Central banks generally counter high inflation by raising interest rates. For Gold, higher rates are a negative: they raise the opportunity cost of holding the metal rather than an interest-bearing asset or money in a cash deposit account. Lower inflation, by contrast, tends to support Gold by bringing interest rates down and making the metal a more viable investment alternative.
POPULAR ARTICLES
1Below $4,150: gold holds steady as traders weigh Fed rate path and Middle East risk2Bank of Japan deputy highlights inflation risk as Japanese Yen holds steady3113.50 in View: AUD/JPY Price Forecast Points to Double-Bottom Upside46.6640: UOB sees gradual Chinese Yuan gains against US Dollar5Below 212.00: GBP/JPY Price Forecast as Doji challenges bullish conviction6Euro awaits PMIs first, then France’s credit rating over the weekend7RBA hike bets double: Australian Dollar shrugs off Iran war fears8November hike already priced in as British Pound awaits retail sales93.7% YoY: New Zealand Q3 CPI Inflation Slows, Below 3.8% Expected
LIVE QUOTES


Get Started!
Sign up and access the Global Markets in less than 3 minutes

Connect With Us









Contacts
Phone: +61 2 8036 8388
Fax: +61 2 8036 8388
Email: support@tmgm.com



The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved