

Trading
Explore a wide range of markets with competitive pricing, deep liquidity, and advanced trading tools.
Learn More 
Platform
Trade seamlessly with TMGM's powerful platform, built for speed, precision, and a superior trading experience.
Learn More Trading Platform
Academy
Learn the fundamentals of trading with beginner-friendly resources, including guides, webinars, and market insights.
Learn More News & Analysis
Get real-time market updates and expert analysis to stay ahead of trading opportunities
Learn More News & Analysis
About
Learn what sets TMGM apart — our global presence, regulatory strength, and commitment to innovation in trading.
Learn More Why Choose TMGM
Sponsorship
160.00 holds as Tokyo’s warnings support third session of yen gains
- 160.00 has capped USD/JPY. The pair is heading for a third consecutive lower close.
- The Yen strengthened as US equities declined, while expectations for a December BoJ rate rise remain intact.
- Tuesday brings Japan's trade figures, followed by national inflation data on Thursday.
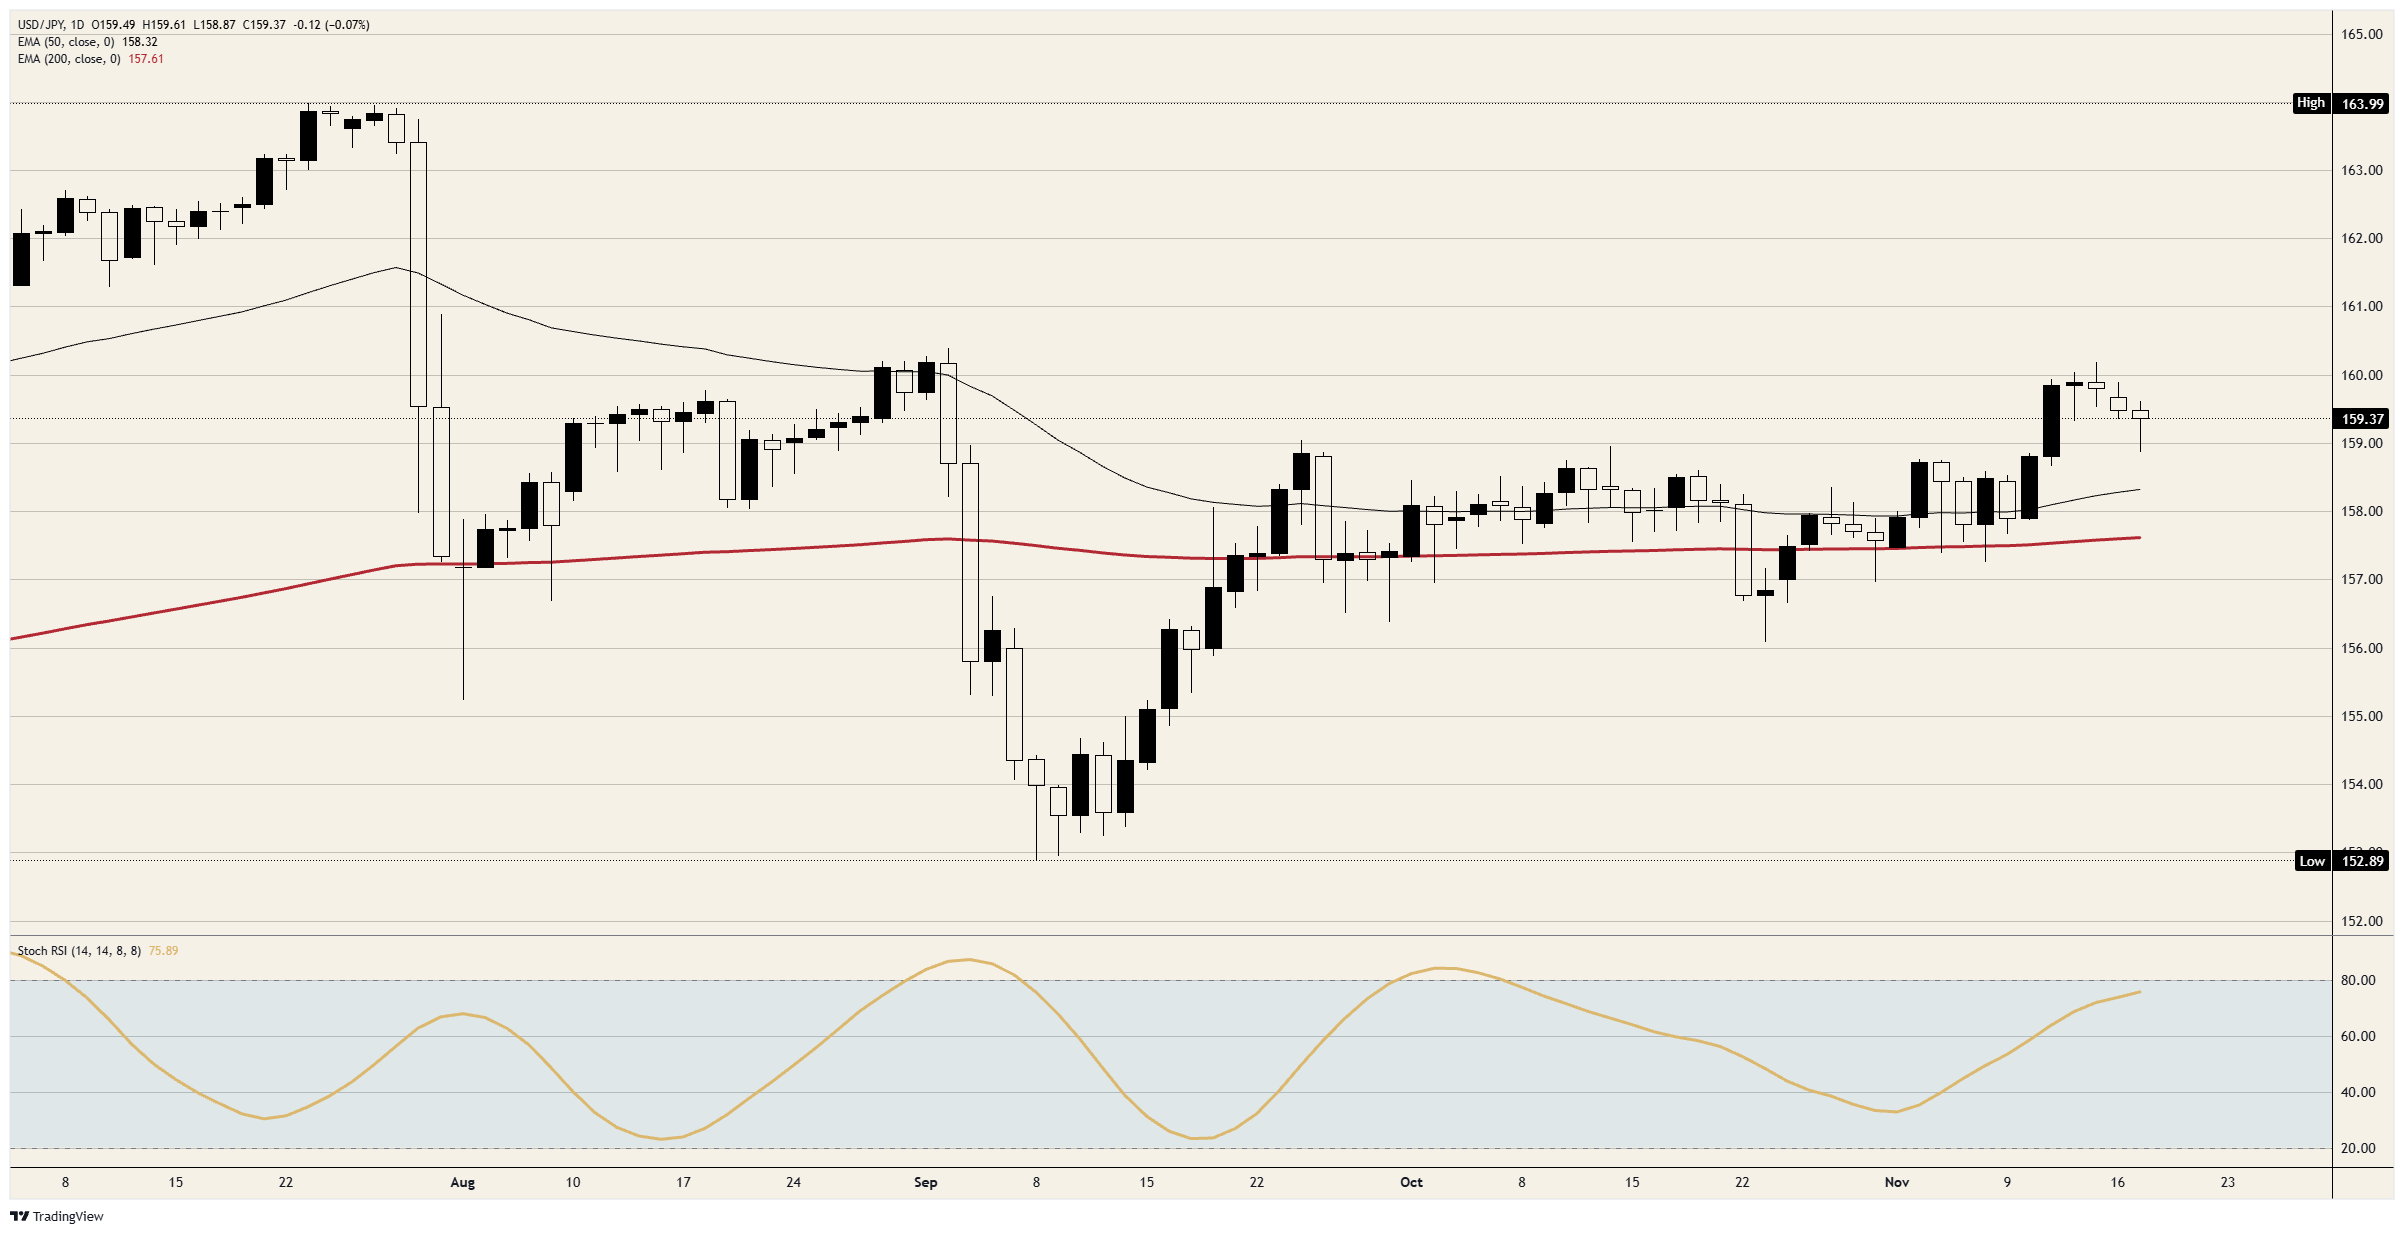
160.00 halted the USD/JPY advance on 12 and 13 November. The pair subsequently slipped to just below 159.00 on Tuesday and now trades just under 159.50. The Yen is strengthening against the Dollar for a third session; during the first two, the Dollar gained against almost every other currency.
Since USD/JPY reached 160.00, Tokyo has cautioned against selling the Yen. Japan's finance ministry says it is monitoring one-sided moves and communicating with the US Treasury. In late July, Tokyo bought Yen when the pair traded near 164.00. This time, verbal intervention alone has kept all daily closes below 160.00.
A second session of losses for US equities on Tuesday supported demand for the Yen as a haven, according to analysts at Brown Brothers Harriman. They attributed USD/JPY's position below 160.00 to risk aversion. Despite Japan's third-quarter economic contraction, most economists continue to expect the Bank of Japan (BoJ) to lift its 1.25% rate on 17–18 December. Markets price in a Fed increase from its 3.75%-4.00% rate nine days before that. A quarter-point rise by each central bank would therefore leave the differential unchanged at 2.50-2.75 percentage points.
20% Export Growth Forecast; Fed Minutes Ahead
At 23:50 GMT on Tuesday, Japan releases its October trade data. Forecasts put annual export growth at 20%, following 16.7%, and import growth at 25.8%, following 18.9%. October national inflation figures arrive on Thursday at 23:30 GMT. Inflation excluding fresh food is projected at 2.3%, up from 2.1%. Both releases will inform the BoJ's 17–18 December meeting.
Wednesday's release of the Fed's October meeting minutes is scheduled for 19:00 GMT. Fed Governor Waller then speaks at 13:25 GMT on Friday. With the probability of a December Fed rate rise priced at nearly 96%, the main question for both events is whether traders price in a second increase.
50-Day EMA Nears 158.50
After climbing from just below 158.00 on 10 November to its 13 November peak, USD/JPY surrendered roughly a third of that advance. The pair has since recouped most of Tuesday's decline, having touched its lowest level since 11 November during the session. The rising 50-day Exponential Moving Average (EMA) now sits just below 158.50, above the 200-day EMA at slightly over 157.50.
USD/JPY chart: daily timeframe
Japanese Yen: Key Questions
Among the world's most actively traded currencies, the Japanese Yen (JPY) takes its broad direction from Japan's economic performance. More specific influences include Bank of Japan policy, the gap between Japanese and US bond yields, and traders' appetite for risk, alongside other factors.
Currency control forms part of the Bank of Japan's mandate, making its actions a major influence on the Yen. On occasion, the BoJ has intervened directly in foreign exchange markets, usually to weaken the currency. Political concerns among Japan's principal trading partners, however, discourage frequent intervention. From 2013 to 2024, its ultra-loose monetary policy drove the Yen lower against major peers as the policy gap between the BoJ and other leading central banks widened. The gradual withdrawal of that ultra-loose stance has more recently provided the Yen with some support.
The BoJ's commitment to ultra-loose monetary policy over the past decade increasingly set it apart from other central banks, notably the US Federal Reserve. That divergence helped widen the yield gap between 10-year US and Japanese bonds, supporting the US Dollar against the Japanese Yen. The differential is now narrowing as the BoJ implements its 2024 decision to exit ultra-loose policy gradually, while other major central banks cut interest rates.
Investors often regard the Japanese Yen as a safe haven. During periods of market stress, its perceived stability and reliability make them more inclined to allocate funds to the currency. Such turbulence is therefore likely to lift the Yen against currencies considered riskier investments.
POPULAR ARTICLES
1Australian Dollar steadies at a 10-month low after split RBA minutes2160.00 holds as Tokyo’s warnings support third session of yen gains3Five-session slide ends for Pound on UK jobs data and softer Dollar41.10: Euro inches back from 19-month low as Dollar softens551% of Bitcoin supply underwater as sell-off intensifies6Dow Jones Industrial Average Falls on NSA Outage Before Nvidia Beats Expectations7US natural gas demand decline brings limited relief to Europe - Commerzbank8UOB: Chinese Yuan likely to extend gains against US Dollar92028 Outlook: Copper Set for Gradual Gains – Commerzbank


Get Started!
Sign up and access the Global Markets in less than 3 minutes

Connect With Us









Contacts
Phone: +61 2 8036 8388
Fax: +61 2 8036 8388
Email: support@tmgm.com



The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved