
News & AnalysisCareer

At around 157.80 against the US Dollar (USD), the Japanese Yen (JPY) is little changed in Thursday’s European session. With attention turning to Friday’s monetary policy announcement from the Bank of Japan (BoJ), USD/JPY remains in consolidation.
Yen markets look beyond BoJ holding decision to December signals
With little change expected at this week’s meeting, investors are looking towards the year-end policy outlook. Commerzbank analysts say markets anticipate “the overnight rate remaining at 1.25%, and none of the economists surveyed by Bloomberg expects a hike this week,” keeping the focus on what follows.
December guidance matters more for currency markets, according to Commerzbank, which argues that “the more important question will therefore be what the BoJ signals about December.” The analysts point out that “markets currently price an around 80% probability of a rate hike by then, in line with our own expectation that the BoJ will raise the policy rate to 1.5%.” Their assessment is that “recent BoJ communication, alongside the economic backdrop, increasingly suggests that the next step towards policy normalization is approaching.”
An unusual source lends weight to that assessment: Commerzbank identifies “additional support for this view” in the BoJ’s semi-annual report on financial system risks, calling it “hardly the most obvious source of monetary policy signals.” Nevertheless, the bank emphasises that “the report suggests that higher rates should remain manageable for Japan's financial system.” More specifically, the analysts note that “in its stress test, the BoJ finds that even a rise in the policy rate to 2% should not pose major problems for Japanese banks and companies.” They also observe that “the increase to 1.25% has already been absorbed without significant disruption, as has the rise in longer-term government bond yields.”
This should not be read as policy guidance, Commerzbank cautions, pointing out that “the BoJ stresses that the 2% assumption is not a forecast but merely part of the stress test scenario.” Nevertheless, its analysts consider that “the message for FX markets is noteworthy: financial stability does not appear to be a binding constraint on further policy normalization.” Although they acknowledge that “Friday itself may therefore provide only limited fresh momentum for the yen,” their conclusion is that “our structurally constructive view on the Japanese currency remains intact.”
October’s Tokyo Consumer Price Index (CPI), due on Friday before the BoJ announces its monetary policy decision, will also draw market attention. The year-on-year (YoY) rate for Tokyo CPI excluding fresh food is expected to ease to 2.6% from September’s 2.7%.
Ahead of the United States (US) flash Q3 Gross Domestic Product (GDP) figures and September’s Personal Consumption Expenditure (PCE) Price Index, the US Dollar is edging higher. Both releases are scheduled for 12:30 GMT.
At the time of writing, a gain of 0.1% leaves the US Dollar Index (DXY) near 102.20. The index measures the Greenback against six major currencies.
TD Securities expects the forthcoming figures to confirm that "Q3 GDP [will] show robust underlying growth," explaining that "GDP growth [having] picked up in Q3 to 2.5% from 2.2% previously with underlying activity remaining robust." On the components of growth, the firm says "consumption likely remained resilient while decelerating slightly," while "fixed investment [was] also strong in large part due to AI." However, it cautions that "net exports likely acted as a major drag on GDP growth while being partially offset by a rebound in inventories," pointing to solid overall growth but an uneven performance beneath the headline figure.
Wednesday saw a correction in the US Dollar following the Federal Reserve’s (Fed) monetary policy announcement. As expected, the central bank left interest rates unchanged within the 3.75%-4.00% range.
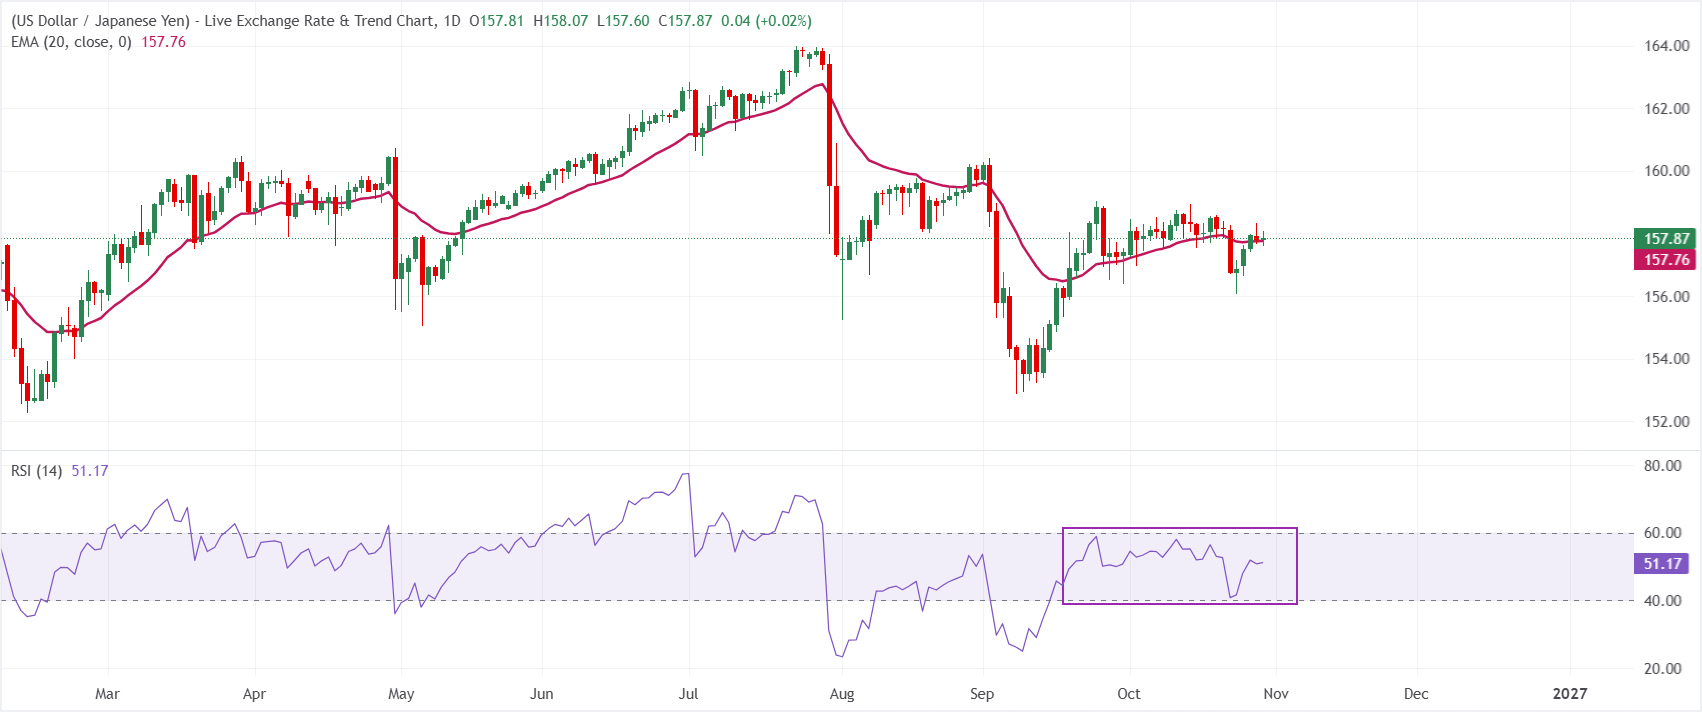
Trading at 157.87 on the daily chart, USD/JPY remains above its 20-period exponential moving average (EMA) of 157.76. This provides immediate trend support, preserving a mildly bullish near-term bias. A Relative Strength Index (RSI) reading around 51 points to neutral to slightly positive momentum: buyers retain a modest edge, but the pair is not overbought.
The first support on a decline lies around 157.76, where the 20-day EMA sits. A daily close beneath that level would suggest a deeper correction towards recent lows. Conversely, provided USD/JPY continues to close above this moving average, the broader constructive outlook is likely to hold, allowing room to test higher levels that nearby technical resistance has yet to define.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
After each of its eight scheduled meetings a year, the Bank of Japan (BoJ) publishes its interest rate decision. A rate increase accompanied by a hawkish assessment of the economy’s inflation outlook is generally supportive of the Japanese Yen (JPY). Conversely, when the BoJ takes a dovish view of the Japanese economy and either leaves rates unchanged or lowers them, the outcome is usually negative for JPY.
Find out more.Next scheduled release: Fri 30 Oct 2026 03:00
Release frequency: At irregular intervals
Consensus forecast: 1.25%
Previous reading: 1.25%
Data source: Bank of Japan







Phone: +61 2 8036 8388
Fax: +61 2 8036 8388
Email: support@tmgm.com



The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved


