

Trading
Explore a wide range of markets with competitive pricing, deep liquidity, and advanced trading tools.
Learn More 
Platform
Trade seamlessly with TMGM's powerful platform, built for speed, precision, and a superior trading experience.
Learn More Trading Platform
Academy
Learn the fundamentals of trading with beginner-friendly resources, including guides, webinars, and market insights.
Learn More News & Analysis
Get real-time market updates and expert analysis to stay ahead of trading opportunities
Learn More News & Analysis
About
Learn what sets TMGM apart — our global presence, regulatory strength, and commitment to innovation in trading.
Learn More Why Choose TMGM
Sponsorship
Below 1.1000: Euro trades ahead of upcoming remarks from ECB President Lagarde
- Below 1.1000: EUR/USD extends losses to a low not seen for at least five months.
- Another rate increase is expected by nearly all Fed officials, the minutes reveal.
- Thursday and Friday bring speeches from ECB President Lagarde; US jobless claims are also due.
EUR/USD reached just above 1.0950, its lowest in at least five months. The pair opened at its session high just above 1.1000 before retreating, and now trades between those levels. Losses have occurred in six of the last seven sessions. An upward revision to Eurozone core inflation failed to support the Euro, as the Federal Reserve's debate has shifted from whether to raise rates in December to the size of the increase.
A couple of officials were open to a December increase of more than a quarter-point, according to the Federal Open Market Committee (FOMC) minutes. In October, the committee voted 10-2 to leave rates at 3.75%-4.00%. Before the rate decision was released, Fed Governor Waller advocated a half-point rise on CNBC. Traders already regard an increase on December 9 as certain. At 2.50%, the European Central Bank (ECB) rate sits at least 1.25 points below the Fed's. The Dollar Index, meanwhile, climbed to its highest level since April 2025.
October core inflation was revised to 2.6% from an initial 2.5% in Eurostat's final release. Headline inflation was confirmed at 4.0%, a three-year high. Markets anticipate an ECB rate rise on December 17, eight days after the expected Fed increase. Should both banks raise rates in the same month, the gap between their rates would remain unchanged.
December 17 decision: key calendar events
Thursday's speech by ECB President Lagarde is scheduled for 13:30 GMT, followed by another at 08:30 GMT on Friday. Bundesbank President Nagel then speaks at 13:00 GMT on Friday. November's Eurozone consumer confidence reading follows at 15:00 GMT, with a forecast of -17.9, unchanged from October. All will inform the ECB's December 17 decision, which determines the European side of the rate differential.
Thursday at 13:30 GMT brings US initial jobless claims, expected at 197K versus the previous 200K. The Philadelphia Fed manufacturing survey is forecast to ease to 20 from 20.9. Both releases will help shape the size of the Fed's December 9 rate increase.
6% below August high: EUR/USD technical picture
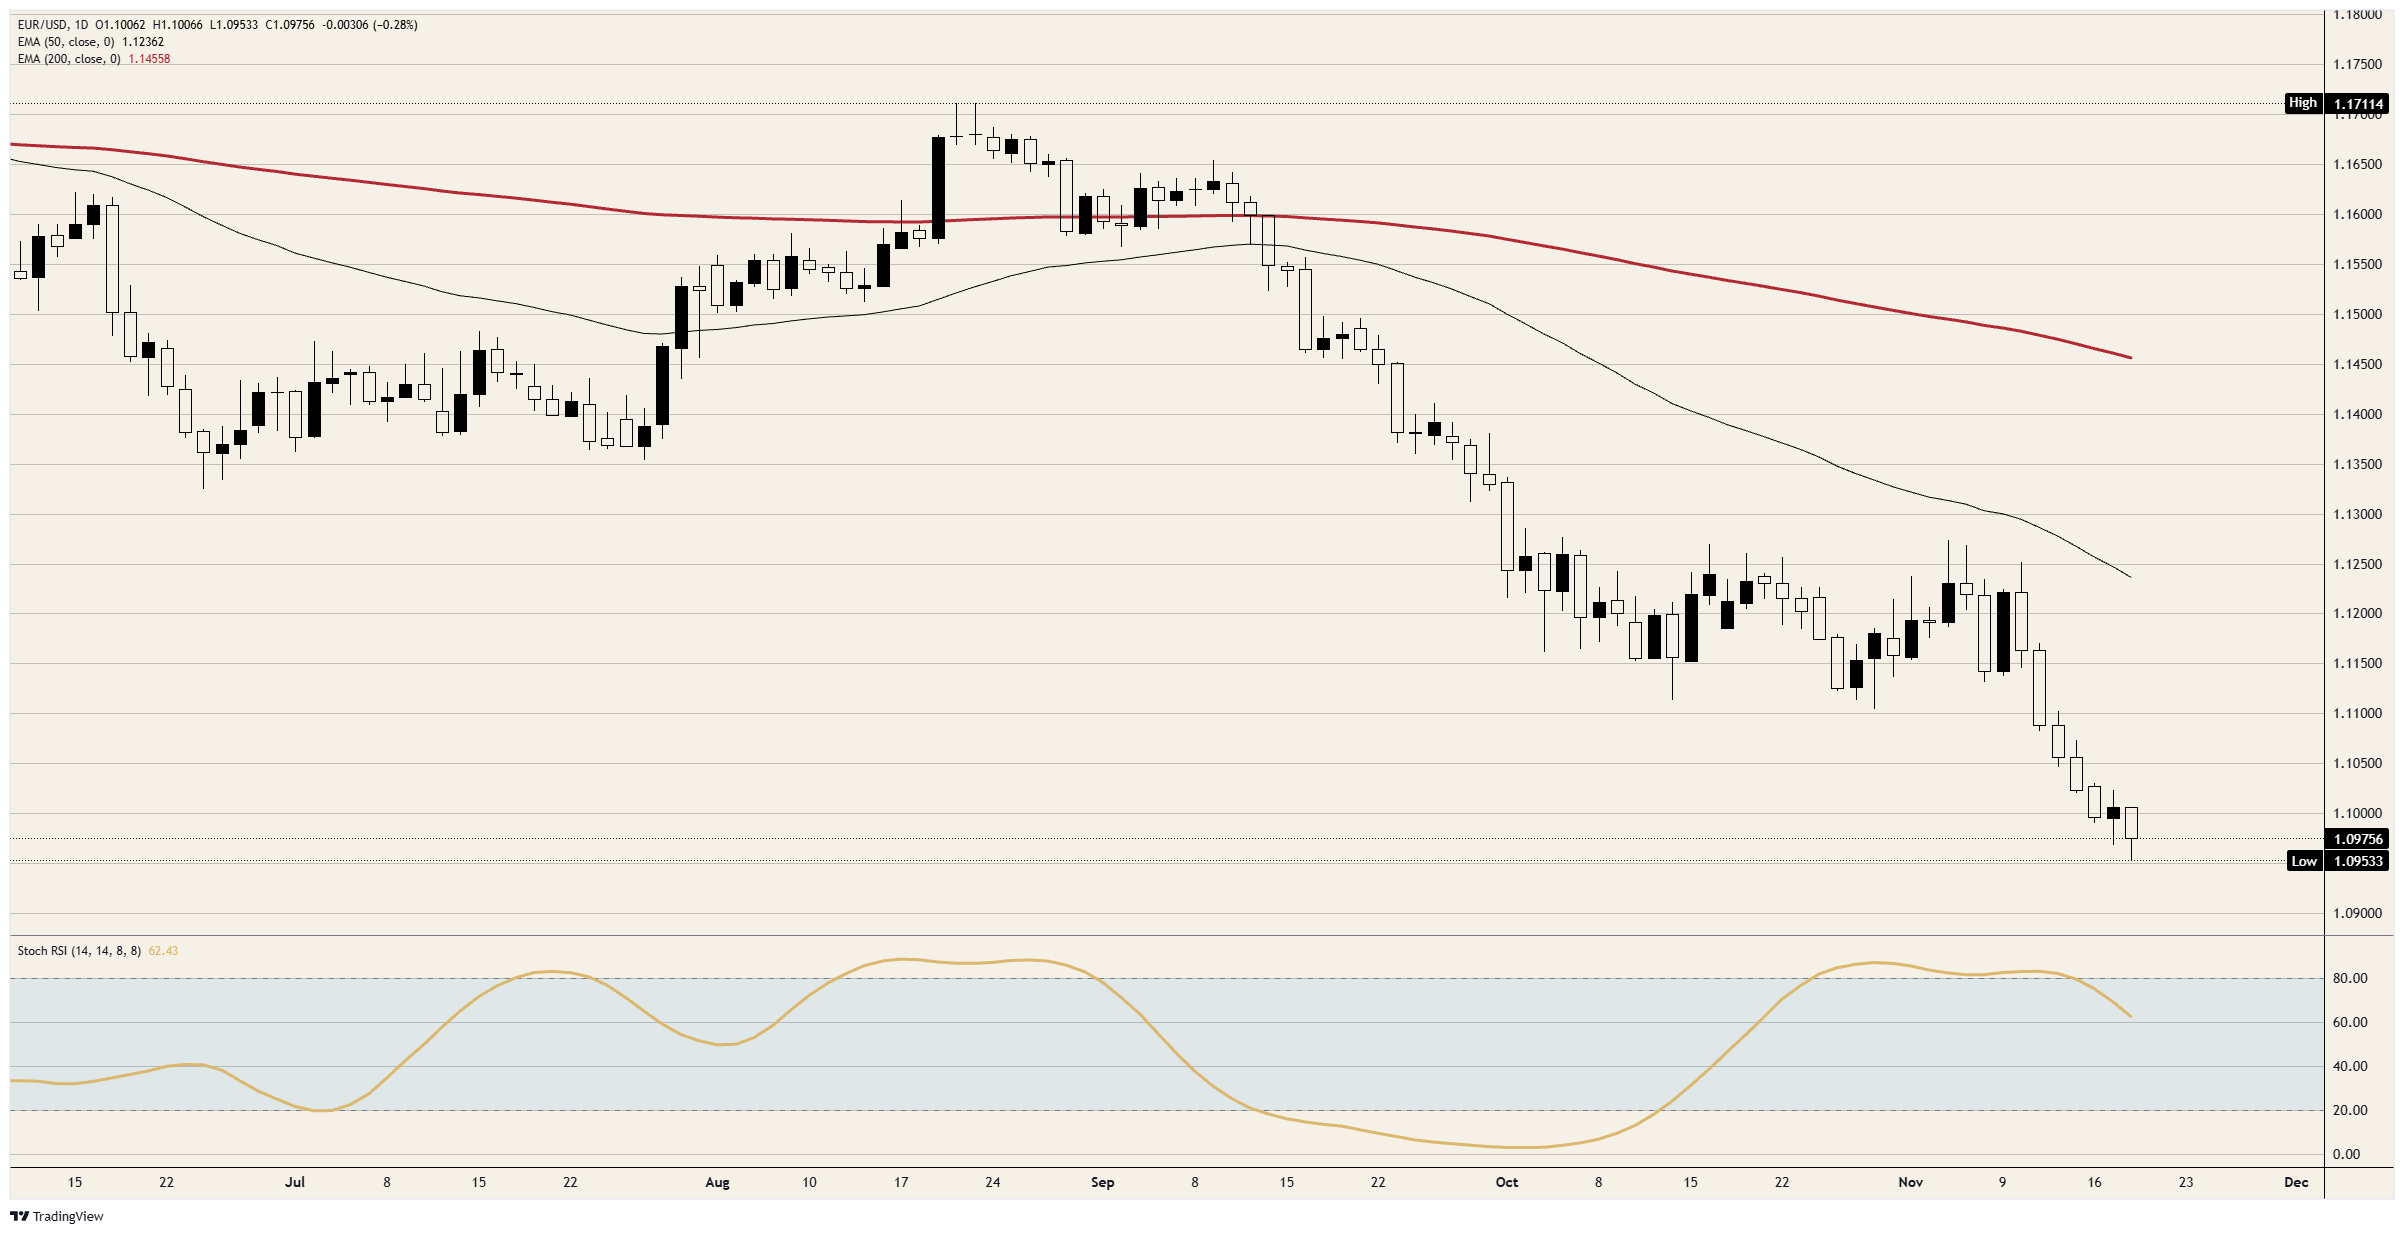
Since breaking lower on November 11, EUR/USD has closed consistently beneath the range of 1.1100 to just above 1.1250 that held from early October. The pair now stands about 6% below its August peak just above 1.1700. Just under 1.1250, the 50-day Exponential Moving Average (EMA) aligns with the upper end of that former range. The 200-day EMA sits near 1.1450.
Daily chart: EUR/USD
Euro: frequently asked questions
Used by the 20 European Union countries in the Eurozone, the Euro ranks second only to the US Dollar in global currency trading. Its share of all foreign exchange transactions reached 31% in 2022, with average daily turnover exceeding $2.2 trillion. An estimated 30% of all transactions involve EUR/USD, making it the world's most actively traded currency pair. EUR/JPY follows with 4%, ahead of EUR/GBP at 3% and EUR/AUD at 2%.
Based in Frankfurt, Germany, the European Central Bank (ECB) serves as the Eurozone's reserve bank, setting interest rates and directing monetary policy. Maintaining price stability is its main mandate, requiring it either to contain inflation or to stimulate growth. Interest rate increases and cuts are its principal policy tool. Higher rates relative to other economies, or expectations of rate increases, generally support the Euro; the reverse also applies. Monetary policy is decided by the ECB Governing Council at eight meetings each year. The decision-makers comprise the heads of Eurozone national banks and six permanent members, among them ECB President Christine Lagarde.
Measured through the Harmonised Index of Consumer Prices (HICP), Eurozone inflation is a key economic gauge for the Euro. An above-forecast increase, particularly beyond the ECB's 2% target, requires the central bank to raise interest rates to regain control of inflation. By making the region a more attractive destination for global capital, interest rates that are relatively high compared with those of its counterparts generally strengthen the Euro.
The Euro can respond to economic releases because they indicate the economy's condition. GDP, Manufacturing and Services PMIs, employment figures and consumer sentiment surveys can each affect the single currency's direction. Economic strength supports the Euro by attracting additional foreign investment. It may also prompt the ECB to raise interest rates, directly strengthening the currency. Weak figures, by contrast, are likely to weigh on the Euro. Particular importance attaches to releases from Germany, France, Italy and Spain. As the euro area's four largest economies, they represent 75% of the Eurozone's economy.
The Trade Balance is another release with significant implications for the Euro. Over a specified period, it records the difference between a country's export earnings and its import spending. Strong overseas demand for a country's exports creates additional demand for its currency as foreign buyers seek to purchase those goods, lifting its value. A positive net Trade Balance therefore supports a currency, while a negative balance has the opposite effect.
POPULAR ARTICLES
1October low revisited as pound returns ahead of UK retail sales2Below 1.1000: Euro trades ahead of upcoming remarks from ECB President Lagarde3UnitedHealth and Nvidia declines weigh on Dow Jones Industrial Average4400K BTC demand contraction: Bitcoin’s bearish signals intensify5$1,800 Recovery Eludes ETH After Futures and Spot Distribution: Ethereum Price Forecast633.00: Taiwan Dollar Shows Signs of Recovery Against US Dollar – OCBC74.7%: Australia’s unemployment rate expected to hold steady8Singapore Dollar: Export support underpins stable trading range outlook – Commerzbank9Indonesian Rupiah: Limited pressure relief from surprise BI rate hike – BBH


Get Started!
Sign up and access the Global Markets in less than 3 minutes

Connect With Us









Contacts
Phone: +61 2 8036 8388
Fax: +61 2 8036 8388
Email: support@tmgm.com



The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved